Actual Cash Value vs Replacement Cost Auto Payouts
Understand actual cash value vs replacement cost auto insurance payout and protect your finances after a total loss. Call (833)-275-7533 for guidance.
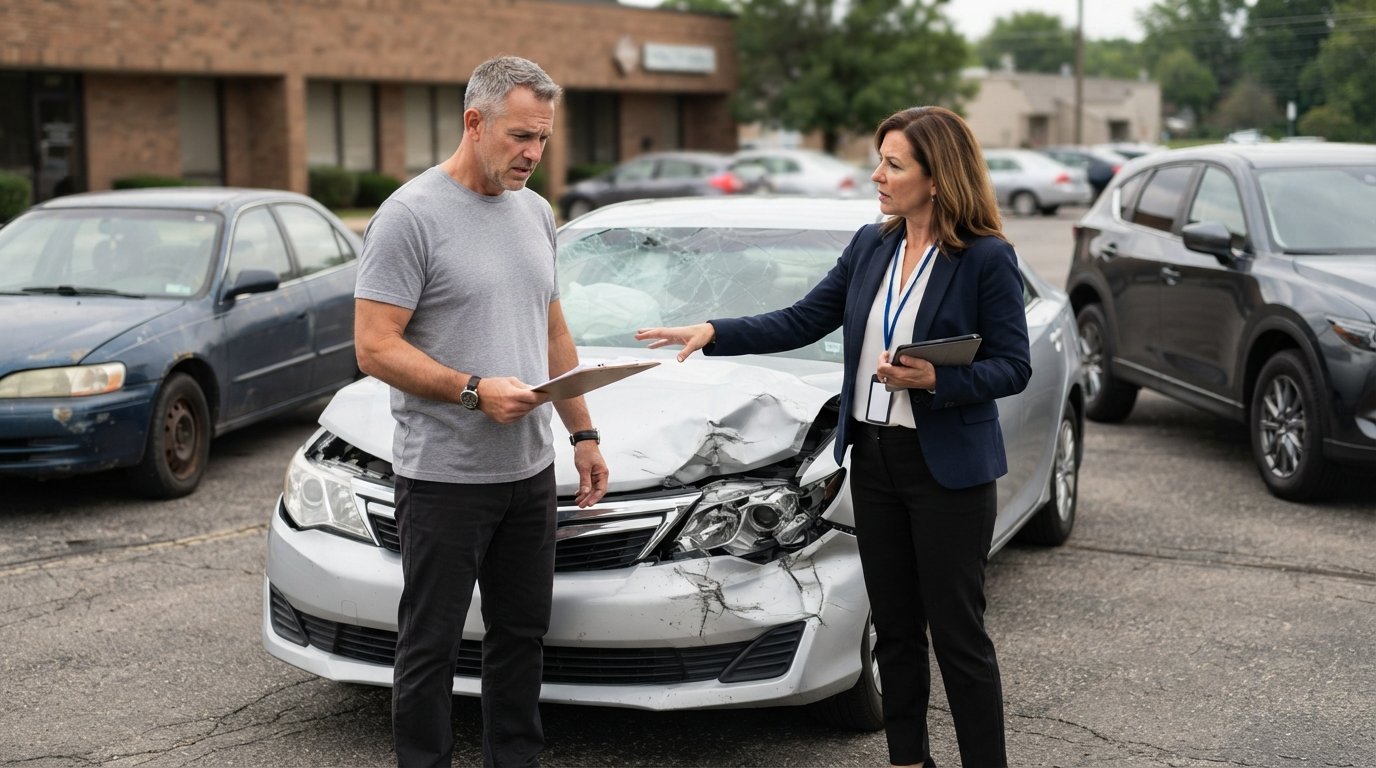
Your car is totaled. The insurer says it will pay actual cash value, but you owe more than that on your loan, and you are not sure how you will replace the vehicle. This is one of the most stressful moments in auto insurance, and the difference between actual cash value and replacement cost can mean thousands of dollars out of your pocket. Understanding how each payout method works, how depreciation is calculated, and what questions to ask before you accept a settlement can help you protect your finances when you need it most.
Actual Cash Value and Replacement Cost Defined in Plain Terms
Actual cash value (ACV) is the amount your vehicle is worth right before a covered loss, taking into account its age, mileage, condition, and local market demand. In other words, ACV is what you could have sold the car for on the day it was damaged. Replacement cost is the amount it would take to buy a comparable vehicle (same make, model, year, and condition) at current market prices, without deducting for depreciation. Replacement cost is almost always higher than actual cash value because a new or newer vehicle costs more than a used one with wear and tear.
Most standard personal auto policies pay actual cash value for total losses. Replacement cost coverage is less common on autos than on homeowners policies, but some carriers offer it as an endorsement or as part of a new car replacement program. If you finance or lease a vehicle, the gap between ACV and what you owe can be significant, which is why lenders often require gap insurance. Knowing which valuation method applies to your policy is the first step in predicting your payout.
Here is a simple way to think about the two terms:
- Actual cash value: What your car is worth today, after depreciation. If your 2018 sedan has 90,000 miles and a scratched bumper, ACV reflects those factors.
- Replacement cost: What it would cost to buy a similar car today from a dealer or private seller, without subtracting for age or mileage.
The distinction matters most after a total loss, because that is when the insurer writes a check for the vehicle's value rather than paying for repairs. If you are comparing quotes or reviewing your current policy, ask the agent explicitly whether total loss settlements are based on ACV or replacement cost. Many drivers assume they have replacement cost coverage when they actually have ACV, and they only find out after a crash.
How Depreciation Is Calculated on a Totaled Vehicle
Depreciation is the decline in your vehicle's value over time due to age, mileage, wear, and market conditions. Insurers use a variety of methods to calculate it, but most rely on industry valuation services that analyze local market data, recent sales, and vehicle history. The adjuster will also inspect the car for pre-existing damage, aftermarket modifications, and condition issues that affect value. The result is a settlement offer that reflects what the vehicle was worth immediately before the loss.
Several factors drive the depreciation calculation. Age and mileage are the biggest, but condition, maintenance records, options, and even color can influence the final number. For example, a well-maintained vehicle with documented service records may appraise higher than an identical model with no maintenance history. Aftermarket additions like a new stereo or lift kit may add value only if they were permanently installed and the insurer agrees they contribute to the vehicle's worth. Most standard policies exclude coverage for custom equipment unless it is specifically listed.
To see how depreciation works in practice, consider a simplified example. Suppose you bought a new SUV three years ago for $38,000. Today, a comparable used model sells for $24,000 in your area, and the insurer determines your vehicle's ACV is $23,500 after accounting for mileage and a small dent. If you have ACV coverage, your payout is $23,500 minus your deductible. If you have replacement cost coverage, the insurer might pay the cost to buy a comparable three-year-old SUV, which could be closer to $26,000 or more, depending on the local market. The difference of $2,500 or more comes directly out of your pocket with ACV.
Depreciation is not always linear, and market conditions can shift quickly. During periods of high used-car demand, ACV settlements may come closer to replacement cost because used prices rise. During soft markets, the gap can widen. This is why it helps to review the insurer's valuation report carefully and compare it with listings for similar vehicles in your area. If you find comparable cars selling for more than the offer, you can submit those listings as evidence to support a higher settlement.
Why ACV Payouts Often Fall Short of Loan Balances
Vehicles depreciate fastest in the first few years of ownership, which is exactly when many buyers finance them. If you put little money down or financed a vehicle with a long loan term, you can easily owe more than the car is worth for months or even years. When a total loss occurs, the ACV payout goes to the lender first, and if the check is smaller than the remaining loan balance, you are still responsible for the difference. This situation is called being upside down or underwater on your auto loan.
Gap insurance is designed to cover that shortfall. It pays the difference between the ACV settlement and the remaining loan or lease balance, up to policy limits. Gap coverage is often offered by dealers at the time of purchase, but it can also be added to some auto insurance policies or purchased separately. If you are financing a new car with a small down payment, gap coverage can be a smart safeguard. Without it, you could be making payments on a vehicle you no longer have, or you could face collection activity from the lender.
Consider this scenario: you owe $18,000 on a car with an ACV of $14,000. Your insurer pays $14,000 minus your deductible, and the lender applies that to your loan. You still owe roughly $4,000, which you must pay out of pocket unless you have gap coverage. For many households, that is a significant unexpected expense on top of the cost of finding a replacement vehicle. Gap insurance does not cover your deductible, and it typically does not cover late fees or extended warranties, so review the terms carefully.
If you are not sure whether you have gap coverage, check your policy declarations page or call your lender. Some automakers include gap coverage automatically in lease agreements, while others offer it as an optional add-on. When you compare auto insurance quotes, ask about gap coverage and new car replacement options so you can weigh the cost against the risk of a total loss.
When Agreed Value or Stated Value Policies Make Sense
Agreed value and stated value policies are alternatives to ACV that can provide more predictable payouts for certain vehicles. An agreed value policy sets a specific value for the vehicle at the time the policy is written, and that amount is paid in the event of a total loss, often without depreciation. Stated value policies list a value on the declarations page, but the insurer may still apply depreciation or pay the lesser of the stated value or actual cash value. These policies are most common for classic cars, collectibles, and custom vehicles where standard ACV valuations do not reflect true worth.
Agreed value coverage can be valuable if you own a vehicle that appreciates or holds its value, such as a restored classic or a limited-production model. It can also make sense for a heavily modified vehicle where the cost to replace custom parts exceeds what a standard policy would pay. Stated value policies are less protective than agreed value because the insurer can still adjust the payout downward, so read the fine print carefully. For everyday drivers, agreed value is rarely necessary and often costs more than standard coverage.
If you are shopping for coverage on a specialty vehicle, ask carriers whether they offer agreed value and what documentation they require, such as an appraisal or photos. For daily drivers, the more practical choice is usually ACV with optional gap coverage, or replacement cost coverage if your carrier offers it. The right answer depends on your vehicle, your loan balance, and your budget for premiums.
Questions to Ask Before Accepting a Total Loss Settlement
When your vehicle is declared a total loss, the insurer will make an offer based on its valuation. You are not obligated to accept the first number, and asking the right questions can help you confirm whether the offer is fair. Start by requesting a copy of the valuation report, which should show the comparables the insurer used, the adjustments made for mileage and condition, and the final ACV. Review it for errors, such as incorrect trim level, missing options, or inaccurate mileage.
Before you sign anything, work through a checklist of questions and evidence. The following steps can help you negotiate with confidence:
- Ask the adjuster to explain how the ACV was calculated and which valuation service was used.
- Request the list of comparable vehicles and verify that they match your car's make, model, year, trim, and options.
- Gather your own evidence, including recent maintenance records, receipts for new tires or parts, and listings for similar vehicles in your area.
- Confirm whether your policy includes replacement cost, gap coverage, or new car replacement benefits that could increase the payout.
- Ask about rental reimbursement and storage fees, and confirm how long those benefits last while you shop for a replacement.
If the offer seems low, submit your evidence in writing and ask for a revised valuation. Many insurers will adjust the offer when presented with credible comparables or receipts for recent work. If you cannot reach an agreement, you may have the right to invoke an appraisal clause or file a complaint with your state insurance department. Keep records of all communications, and do not cash the settlement check until you are satisfied with the terms, because cashing it may release the insurer from further liability.
It also helps to understand your state's rules on total loss thresholds and salvage titles. Some states require insurers to declare a vehicle a total loss when repairs exceed a certain percentage of its value, and the salvage process can affect your payout. If you retain the salvage, the insurer will deduct its salvage value from the settlement. Ask the adjuster to walk you through these details so you can decide whether keeping the salvage makes sense for your situation.
Finally, consider how the payout will affect your overall financial picture. If you still owe on a loan, coordinate with your lender to ensure the settlement is applied correctly and to find out whether gap coverage applies. If you own the car outright, the settlement is yours to use toward a replacement. In either case, having a clear plan for the money before you accept the offer can reduce stress and help you avoid costly mistakes.
For drivers who want to compare coverage options and understand how different payout methods affect premiums, independent resources can help. For example, NewAutoInsurance offers consumer guidance and comparisons that explain coverage types and savings opportunities, which can be useful when you are deciding between ACV, replacement cost, and gap coverage. The key is to ask questions early, review your policy language, and shop around for quotes that match your risk tolerance and budget.
Understanding actual cash value vs replacement cost auto insurance payout is ultimately about knowing what you are buying before a loss happens. ACV coverage costs less but leaves you responsible for depreciation, while replacement cost and agreed value options cost more but can reduce out-of-pocket costs after a total loss. Gap coverage fills the space between ACV and your loan balance, and a careful review of your settlement offer can help you recover the full amount you are owed. Take time to review your policy, ask the right questions, and compare quotes from multiple carriers so you can choose coverage that protects your finances when it matters most.