Car Insurance After Bankruptcy Filing: Rates and Coverage
Get car insurance after bankruptcy filing without overpaying. Call (833)-275-7533 to compare quotes and find coverage that fits your budget.
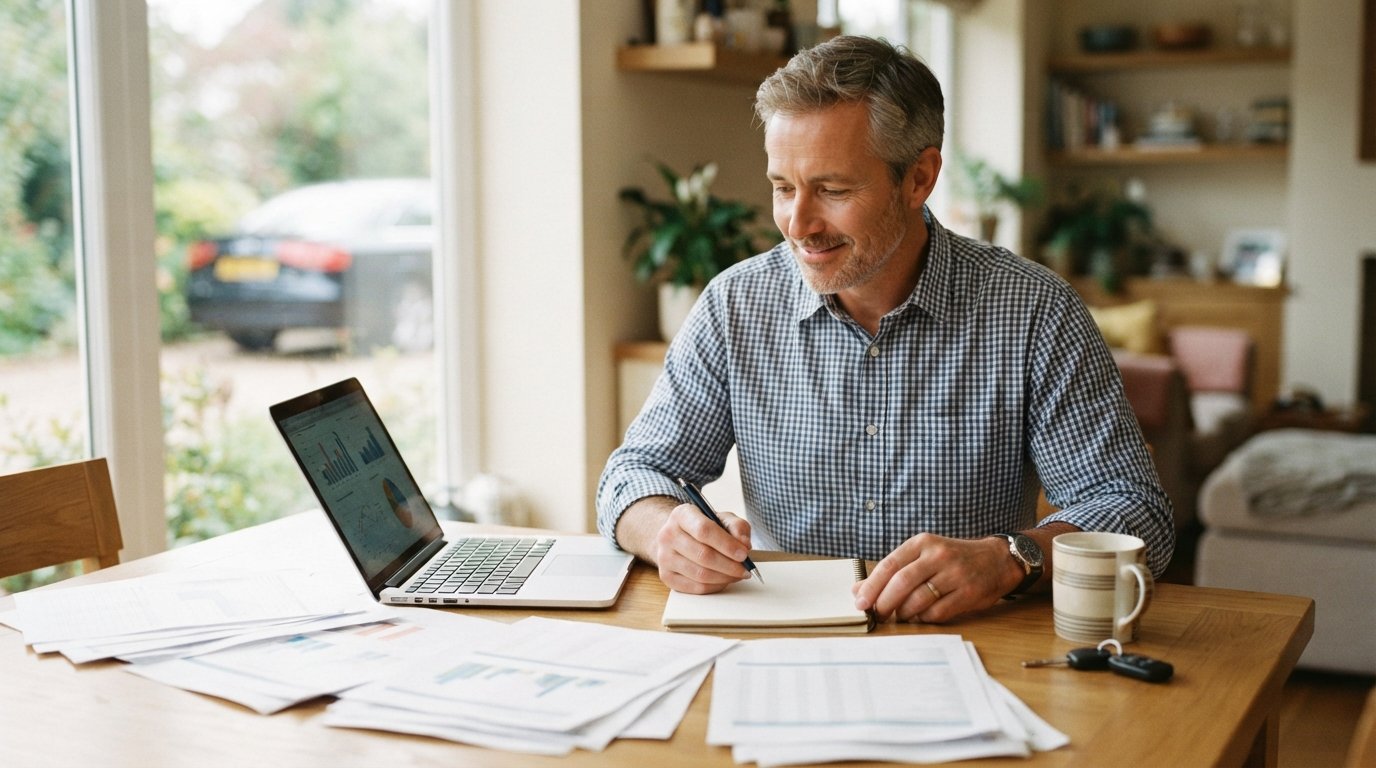
Filing for bankruptcy can feel like a financial earthquake, but it is not the end of your driving life. If you are wondering how to secure car insurance after bankruptcy filing, the short answer is that you can still get covered, and in many cases, you can find competitive rates. Insurers look at bankruptcy as one piece of a larger financial puzzle, and while it may signal higher risk to some carriers, it does not automatically lock you out of affordable coverage. Understanding how insurance companies view bankruptcy, how state laws shape what they can charge, and how to rebuild your insurance profile will help you move forward with confidence. Whether your bankruptcy was recently discharged or you are still in the process, the strategies below will help you navigate the road ahead.
How Bankruptcy Shows Up in Insurance Scoring and Rating
Most major auto insurance carriers use credit-based insurance scores as part of their rating formula. These scores are calculated from information in your credit report, including payment history, outstanding debt, and public records such as bankruptcies. A bankruptcy filing can remain on your credit report for seven to ten years, depending on the chapter and the credit bureau, and its presence can lower your insurance score. However, the impact is not uniform across all insurers. Some companies weigh bankruptcy more heavily than others, and the effect tends to diminish over time as you rebuild positive credit habits.
Insurance scoring models treat bankruptcy differently from a simple late payment because it represents a broader pattern of financial distress. Still, many carriers recognize that a discharged bankruptcy often marks a fresh start. Once your debts are resolved, you become less of a risk than someone who is still accumulating unpaid bills. The key is to demonstrate that you have turned a corner. That means paying every bill on time, keeping credit card balances low, and avoiding new negative marks. Over time, these positive behaviors can offset the weight of the bankruptcy in your insurance score.
It is also worth noting that not all states allow insurers to use credit information for auto insurance rating. In states like California, Hawaii, Massachusetts, and Michigan, credit-based insurance scores are either banned or heavily restricted. If you live in one of these states, your bankruptcy filing may have little to no effect on your car insurance premiums. In other states, the impact can be more pronounced, but it is still just one factor among many, including your driving record, age, location, and the type of vehicle you drive.
Does a Discharged Bankruptcy Affect Eligibility?
A discharged bankruptcy does not make you ineligible for car insurance. In fact, every state requires drivers to carry at least a minimum level of liability insurance, and insurers cannot refuse to sell you a policy solely because you have filed for bankruptcy. However, some carriers may choose not to offer you their most competitive rates or may place you in a higher-risk tier. That said, there are plenty of insurers that specialize in covering drivers with past credit issues, and many mainstream carriers will still offer standard policies.
The timing of your bankruptcy matters. If your case is still open and not yet discharged, some insurers may be more cautious, but you can still obtain coverage. Once your discharge is finalized, your financial picture becomes clearer, and insurers can see that you have resolved your debts. At that point, you may find that more carriers are willing to offer you standard rates. It is important to be honest on your insurance application: failing to disclose a bankruptcy when asked can be considered misrepresentation and could lead to a denied claim or policy cancellation.
If you are having trouble finding coverage with a standard insurer, consider working with an independent insurance agent who can shop your policy among multiple carriers. Our guide on car insurance for new drivers with no credit history explains how limited credit can affect your options, and the same principles apply after bankruptcy. An agent can help you identify companies that are more forgiving of past credit issues and can explain how each insurer's rating system works.
State Rules Limiting Credit-Based Insurance Pricing
As mentioned, a handful of states restrict or prohibit the use of credit information in auto insurance underwriting and rating. These rules can significantly change how a bankruptcy affects your premiums. For example, California's Proposition 103 prohibits insurers from using credit history to set rates, so a bankruptcy filing would not directly impact your car insurance there. Massachusetts and Hawaii have similar bans, and Michigan limits the use of credit information for certain purposes. If you live in one of these states, you can focus on other factors, such as your driving record and claims history, to keep your rates low.
In states without such restrictions, insurers may use credit-based insurance scores, but they must still comply with state laws that require rates to be fair and non-discriminatory. Some states also have specific rules about how long a bankruptcy can be used against you. For instance, a bankruptcy that is more than seven years old may be excluded from your insurance score in certain jurisdictions. It is a good idea to check with your state's department of insurance to understand your rights and the specific rules that apply to you.
Even in states where credit is used, the impact of a bankruptcy is not permanent. As time passes and you build a positive payment history, its effect on your insurance score will gradually fade. Many insurers also offer programs or discounts for drivers who complete financial education courses or who demonstrate responsible behavior after a bankruptcy. These can help you offset the negative impact and lower your premiums.
Building a Clean Payment History Post-Bankruptcy
One of the most effective ways to improve your car insurance rates after bankruptcy is to build a clean payment history. Insurers like to see that you can manage your finances responsibly, and a consistent record of on-time payments can go a long way toward rebuilding your insurance score. Start by setting up automatic payments for your car insurance premium so you never miss a due date. Then, focus on paying all your other bills on time, including utilities, rent or mortgage, and any new credit accounts you open.
Consider opening a secured credit card or a credit-builder loan to establish positive credit history. Use the card for small purchases and pay the balance in full each month. This demonstrates that you can handle credit responsibly and can help raise your credit score, which in turn may improve your insurance score. Keep your credit utilization low (below 30% of your available credit) and avoid applying for multiple new credit accounts at once, as hard inquiries can temporarily lower your score.
Another strategy is to maintain continuous car insurance coverage. Gaps in coverage are viewed unfavorably by insurers and can lead to higher rates. If you are struggling to afford your premium, talk to your agent about adjusting your coverage or increasing your deductible rather than letting your policy lapse. Many insurers also offer discounts for loyalty, safe driving, and bundling multiple policies, which can help you save money while you rebuild your financial profile.
Comparing Quotes and Choosing Adequate Liability Limits
After a bankruptcy, it is more important than ever to compare car insurance quotes from multiple carriers. Rates can vary significantly from one insurer to another, and the company that offers you the best rate may not be the one you expect. Use an online comparison tool or work with an independent agent to gather quotes from at least three to five insurers. Be prepared to provide information about your bankruptcy, your driving record, and your vehicle, and be honest about your situation.
When comparing quotes, do not focus solely on price. Make sure you are comparing apples to apples by looking at the coverage limits and deductibles. After a bankruptcy, you may be tempted to purchase only the state minimum liability coverage to save money, but that can be a risky choice. If you are involved in an accident and are found at fault, minimum limits may not be enough to cover the other party's medical bills or property damage, leaving you personally responsible for the excess. In many cases, it is worth paying a little more for higher liability limits to protect your assets as you rebuild.
Consider the following when choosing liability limits:
- State minimum requirements: Know what your state requires and treat that as a floor, not a ceiling.
- Your assets: If you have savings or equity in a home, higher limits can shield those assets from a lawsuit.
- Future income: Even if you have few assets now, a serious accident could lead to wage garnishment if your limits are too low.
- Cost difference: The jump from minimum to moderate limits is often smaller than you might think, so get quotes for several coverage levels.
Also, ask about discounts that may apply to you, such as safe driver, multi-policy, or good student discounts. Some insurers offer discounts for completing a defensive driving course, which can be especially helpful for high-risk drivers. And remember that you can always adjust your coverage as your financial situation improves.
Practical Steps to Get Covered After Bankruptcy
If you are ready to start shopping for car insurance after bankruptcy filing, follow these steps to streamline the process. First, gather your documents: your bankruptcy discharge papers, your driver's license, vehicle registration, and current insurance policy if you have one. Having this information handy will make it easier to get accurate quotes. Next, use a comparison platform like Free Auto Insurance Quotes Online to request quotes from multiple carriers. You can fill out a simple form and receive personalized quotes from licensed agents without any obligation to buy.
When you receive quotes, review them carefully and ask questions about how the bankruptcy affected your rate. Some insurers may be willing to reconsider your rate after a certain period, so ask about their policies for re-rating. You can also inquire about any programs for drivers rebuilding credit. Finally, choose a policy that balances affordability with adequate protection, and set up automatic payments to avoid lapses. For additional resources and educational content about auto insurance, you can visit NewAutoInsurance, which offers guides and comparisons for drivers in the United States.
Remember that bankruptcy is a temporary setback, not a permanent label. With time, responsible financial habits, and smart shopping, you can find affordable car insurance and rebuild your financial standing. Stay proactive, compare quotes regularly, and don't hesitate to seek advice from insurance professionals who understand your situation.