Car Insurance for Drivers with an International License
Find car insurance for drivers with an international license. Compare quotes from multiple carriers and get covered fast. Call (833)-275-7533 for help.
By Althea Monroe
Moving to the United States with a foreign driver's license can feel like a crash course in bureaucracy. Between finding housing, setting up utilities, and learning local driving laws, securing car insurance for drivers with an international license often gets pushed to the bottom of the list. But skipping this step can lead to costly fines, denied claims, or even being turned away at a rental counter. The good news is that U.S. auto insurers do write policies for international license holders, provided you understand the rules and present the right documents. This guide walks you through what carriers expect, how your foreign driving record affects pricing, and how to compare quotes when your U.S. record is thin.
Do U.S. Carriers Accept a Foreign Driver's License?
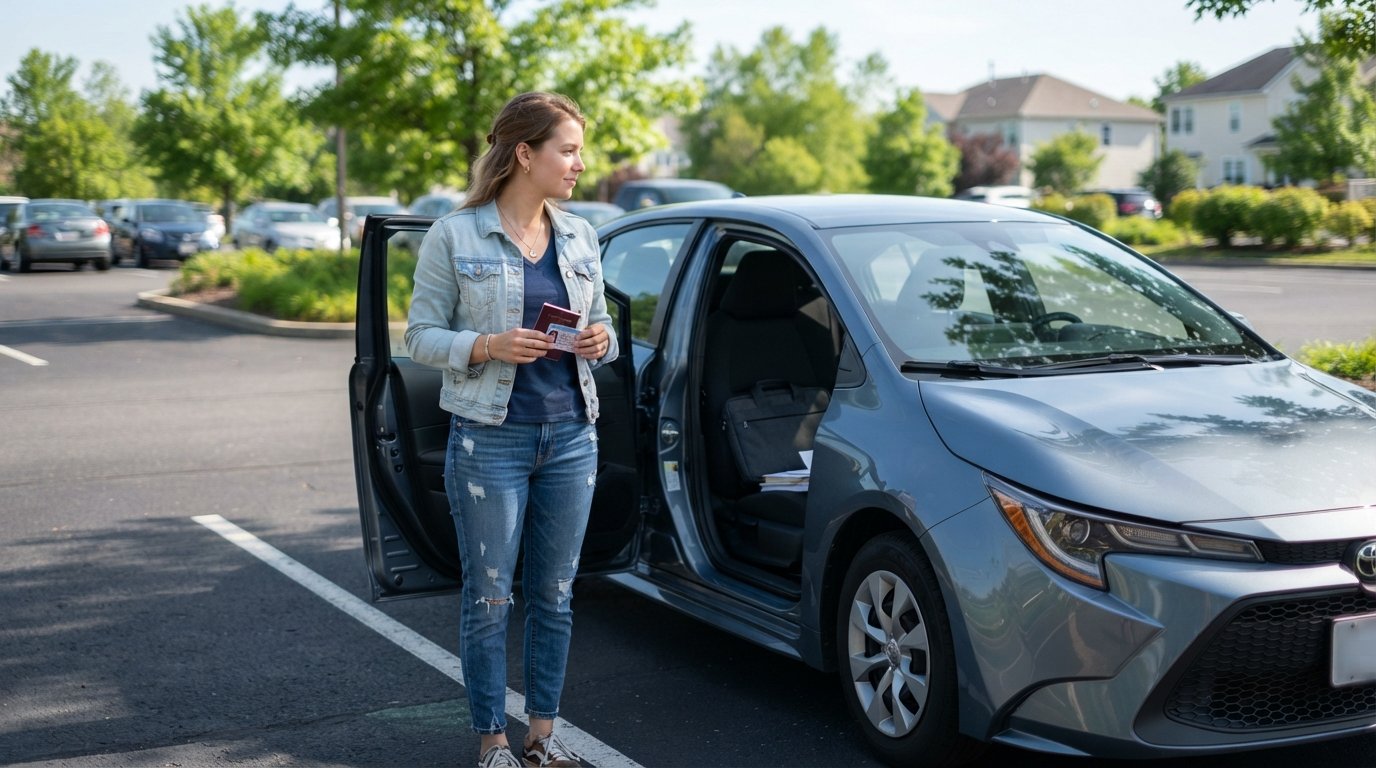
The short answer is yes, but with conditions. Most U.S. auto insurance companies will accept a valid foreign driver's license as proof of driving competency for a limited period, typically ranging from 30 to 90 days after you establish residency in a state. After that window, many states require you to obtain a state-issued license. Insurers follow state regulations closely, so the exact grace period depends on where you live. For example, California allows new residents to drive with a foreign license for up to 10 days after becoming a resident, while Texas gives you 90 days. New York requires you to exchange your foreign license for a New York license within 30 days of establishing residency.
Even during the grace period, some carriers may decline to issue a policy if you only hold an international driving permit (IDP). An IDP is a translation document, not a standalone license. Insurers typically want to see the underlying foreign license from your home country. If you present both an IDP and your original license, you improve your chances of acceptance. However, a handful of carriers will only write policies for drivers with a U.S. license, so you may need to shop around. Working with a comparison platform that understands international drivers can save you hours of phone calls.
One practical note: if you are renting a car immediately after arrival, your foreign license plus an IDP is usually sufficient for the rental company. But for a long-term policy on a car you own or lease, insurers will want to see your foreign license and may ask for a translation if it is not in English. Getting a certified translation before you apply can speed up the process.
Documents Insurers Typically Request from International Drivers
When you apply for car insurance for drivers with an international license, expect to provide more documentation than a typical U.S. applicant. Insurers are assessing risk, and without a U.S. driving history, they rely on alternative evidence to decide whether to offer coverage and at what price. The exact list varies by carrier, but most will ask for the following items. Gathering them in advance prevents delays and helps you get accurate quotes.
- Valid foreign driver's license: The original license from your home country, plus a certified English translation if it is not in English.
- International Driving Permit (IDP): Often requested as a supplement, though it does not replace your home license.
- Passport or visa: Proof of legal presence in the United States, such as a passport with a valid visa stamp or a green card.
- Proof of residency: A lease agreement, utility bill, or mortgage statement showing your U.S. address.
- Driving record or letter of experience: A translated copy of your home country's driving record or a letter from your previous insurer confirming your claims history.
Some insurers may also ask for a Social Security Number (SSN) or an Individual Taxpayer Identification Number (ITIN). If you do not have an SSN, many carriers will still issue a policy using your passport number or ITIN, but you should confirm this before applying. Providing a letter of experience from your previous insurer is especially valuable because it can prove years of claim-free driving, which may qualify you for a good-driver discount even without a U.S. record. If you are a high-risk driver due to a foreign violation or a lapse in coverage, you may face higher rates, but specialized non-standard carriers can still help. For more on that, see our guide to cheap car insurance for high-risk drivers in Florida, which explains how non-standard markets work.
How Foreign Driving History Affects Eligibility and Pricing
U.S. insurers base premiums on a range of factors, and your driving record is one of the most significant. When you have no U.S. history, carriers cannot verify your claims or violations through domestic databases. As a result, many treat you as a new driver, which typically means higher rates. However, some insurers are more flexible and will consider a clean foreign driving record as evidence of low risk. The key is to provide documentation: a translated motor vehicle report (MVR) from your home country or a letter of experience from your previous insurer showing the number of years you held a license and any claims you filed.
Pricing also depends on other variables. Your age, the type of vehicle you drive, your coverage limits, and your credit score (in most states) all play a role. If you have a credit history in the U.S., even a short one, it can help. If not, some carriers use alternative scoring models. The table below summarizes how different factors typically influence premiums for international license holders, though actual rates vary by state and carrier.
| Factor | Impact on Premium |
|---|---|
| Clean foreign driving record (documented) | May reduce premium by 5-15% compared to no record |
| No U.S. driving history | Often treated as new driver, higher base rate |
| Foreign violations or accidents | Can increase premium significantly, depending on severity |
| Years of licensed driving abroad | Some carriers offer discounts for 5+ years |
| Vehicle safety features | Discounts for airbags, anti-theft devices, etc. |
It is also worth noting that some states, such as California, prohibit the use of credit scores in auto insurance pricing, which can work in your favor if your U.S. credit file is thin. Conversely, states like Texas allow credit-based insurance scores, so maintaining a good credit history can lower your rates over time. Always ask carriers how they handle foreign driving records and whether they offer any international-specific discounts.
Non-Owner and Temporary Policy Options While Waiting for a State License
If you do not own a car but still need to drive occasionally (for example, using a car-sharing service or borrowing a friend's vehicle), a non-owner car insurance policy can be a smart solution. Non-owner policies provide liability coverage and sometimes uninsured motorist coverage, but they do not cover physical damage to a vehicle you do not own. They are ideal for international drivers who need to maintain continuous coverage to avoid a lapse, or who want to establish a U.S. insurance history before buying a car. Many carriers offer non-owner policies to holders of foreign licenses, though you may need to provide the same documentation listed above.
For those who buy a car immediately upon arrival, a temporary policy or a standard six-month policy may be available. Some insurers offer short-term policies (one to three months) designed for new residents, which can bridge the gap until you obtain a state license. These policies are often more expensive per month than annual policies, but they provide peace of mind and keep you legal. If you are waiting for your state license appointment, you can usually keep your foreign-license-based policy active, but you must notify your insurer once you receive your state license, as your rate may change (often downward, since a U.S. license reduces uncertainty).
When comparing temporary options, pay attention to the coverage limits. State minimum liability limits may be too low to protect your assets if you cause an accident. Consider higher limits if you have significant savings or income. Also, ask whether the policy includes uninsured/underinsured motorist coverage, which is crucial in states with many uninsured drivers. For a deeper dive into coverage types and to compare quotes from multiple carriers, you can use the resources at NewAutoInsurance, an independent consumer guide that explains coverage options and savings strategies.
Steps to Compare Quotes When Your Record Is Thin or Foreign
Comparing car insurance for drivers with an international license requires a bit more legwork than a standard quote comparison, but it is manageable. Follow these steps to streamline the process and avoid surprises.
- Gather your documents: Collect your foreign license, IDP, passport/visa, proof of residency, and any foreign driving record or letter of experience. Having these ready ensures you can provide consistent information to each insurer.
- Determine your state's requirements: Check the minimum liability limits and any special rules for international license holders. The state DMV website is the authoritative source.
- Use a comparison platform: Instead of calling each carrier individually, use a service that provides free, no-obligation quotes from multiple insurers. This saves time and helps you see which carriers are friendly to international drivers.
- Ask about international-specific discounts: Some carriers offer discounts for drivers with advanced safety features, defensive driving courses, or continuous coverage abroad. Inquire explicitly.
- Review quotes carefully: Compare not just the premium but also deductibles, coverage limits, and exclusions. A low premium with minimal coverage may cost you more in the long run.
After you receive quotes, verify that each insurer will accept your foreign license and that the policy will remain valid until you obtain a state license. Some carriers may require you to switch to a U.S. license within a specific timeframe, so clarify that upfront. Finally, once you get your state license, update your policy. In many cases, your rate will drop because you now have a verifiable U.S. driving record, even if it is brand new.
For personalized assistance, you can call (833)-275-7533 to speak with a licensed agent who can answer questions about international licenses and help you compare quotes from multiple carriers. The call is free and there is no obligation to purchase.
Securing car insurance for drivers with an international license does not have to be a headache. With the right documents, a clear understanding of state rules, and a willingness to compare quotes, you can find coverage that protects you and your vehicle while you transition to a U.S. license. Start by gathering your paperwork, then use a trusted comparison tool to see offers from multiple insurers side by side. The effort you put in now will pay off with lower rates and peace of mind on the road.