Common Misconceptions About Auto Insurance Renewals
Debunk common misconceptions about auto insurance renewals and learn how to avoid surprise premium hikes. Call (833)-275-7533 for expert guidance.
By Juniper Sloane
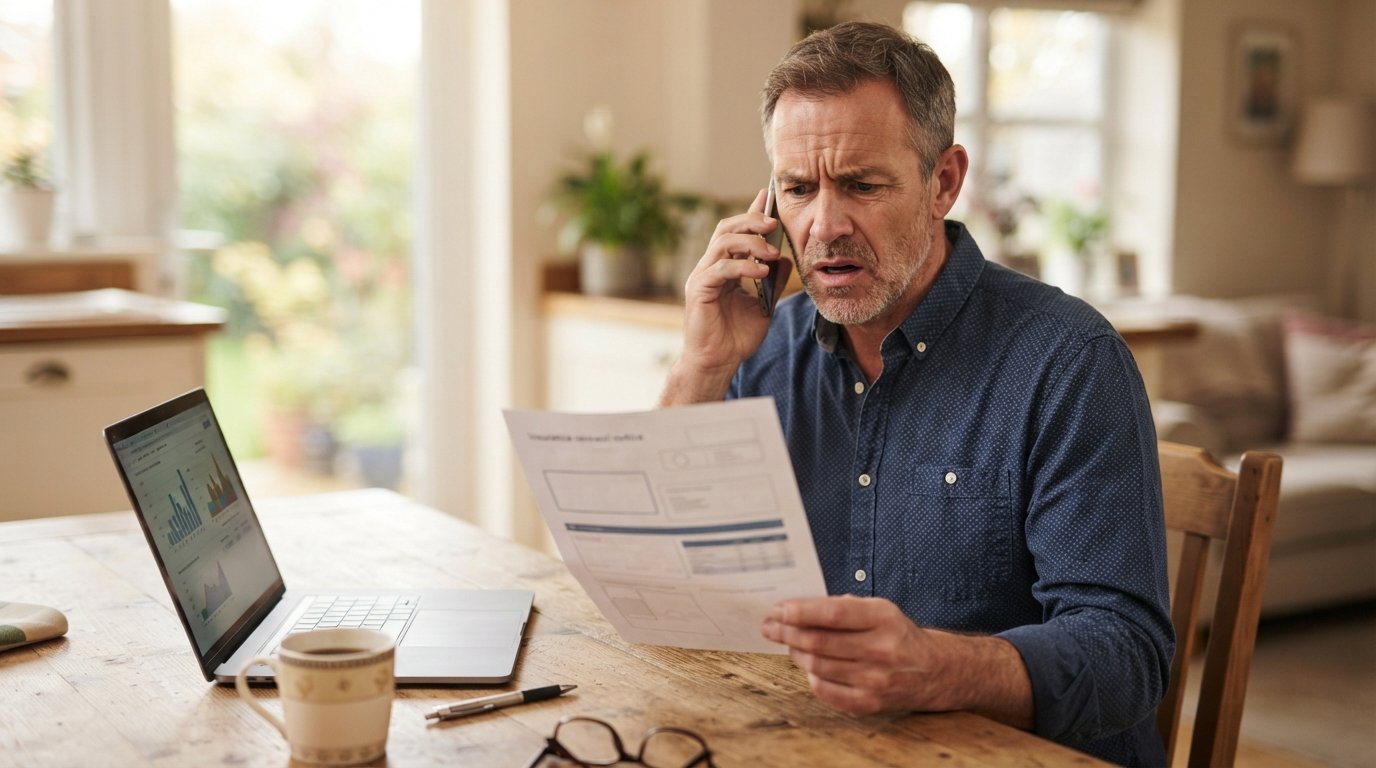
Your auto insurance renewal notice arrives, and the premium has jumped by 18 percent. You have not had a ticket or a claim in years, so you assume it must be a mistake. You call your agent, and they explain something you have never heard before: insurers can raise rates for reasons that have nothing to do with your personal driving record. This scenario plays out for thousands of policyholders every single day, and it usually stems from a handful of persistent myths about how renewals actually work. Understanding what really happens at renewal, and what does not, can save you hundreds of dollars and protect you from coverage gaps you never saw coming.
Why Renewal Premiums Rise Without Tickets or Claims
The most common misconception about auto insurance renewals is that a clean driving record guarantees a stable premium. Policyholders often believe their rate should stay flat or even drop as long as they avoid accidents and violations. In reality, your renewal premium is recalculated using a broad set of factors, and only some of them are under your control.
Insurers file rates with state regulators, and those rates reflect the expected cost of paying claims across an entire pool of drivers. When medical costs rise, when repair shops charge more for parts and labor, or when severe weather drives up comprehensive claims in your region, the insurer adjusts its base rates. Those adjustments apply to renewals across the board, regardless of whether you personally filed a claim. A driver in a hail-prone state may see a renewal increase simply because the insurer paid out thousands of roof and hood claims the previous season.
Other factors that can move your renewal premium include changes in your credit-based insurance score, a new address, a different vehicle, or even a change in how many miles you drive. Some states also allow insurers to consider inflation in medical payments coverage when setting renewal rates. The key takeaway is that renewal pricing is dynamic, and a clean record only protects you from the portion of the increase tied to your individual risk profile.
If your renewal quote seems high, the productive response is not to assume an error but to compare fresh quotes. Our guide on comparing Texas auto insurance quotes walks through how to line up multiple offers side by side, and the same approach works in every state. You can also visit NewAutoInsurance for independent educational resources that explain how rates are built and what factors you can influence.
The Loyalty Myth: Does Staying Put Earn You the Best Rate?
A second widespread belief is that long-term customers automatically receive the insurer's best available rate. Many policyholders stay with the same carrier for a decade or more, convinced that loyalty discounts and tenure rewards will keep their premium competitive. The reality is more complicated, and often less favorable to the consumer.
Insurers do offer loyalty discounts in many states, but those discounts are typically modest, often in the range of 5 to 10 percent. Meanwhile, the base rate for a new customer in the same profile may be substantially lower because the insurer is running a promotional acquisition campaign. This phenomenon, sometimes called price optimization or dual pricing, means that loyal customers can end up paying more than new customers for identical coverage. Several states have moved to restrict or ban the practice, but it remains common in many markets.
The practical lesson is that loyalty should never replace shopping. At every renewal, you have a natural opportunity to check whether your current carrier still offers competitive value. A simple comparison of three or four quotes takes about fifteen minutes and can reveal savings that far exceed any loyalty discount. Treat renewal as a scheduled review, not a set-and-forget event.
Coverage Limits Do Not Automatically Rise With Inflation
Perhaps the most financially dangerous misconception about auto insurance renewals is the assumption that coverage amounts adjust upward automatically to keep pace with inflation. They do not. Your policy limits are contractual figures that remain fixed unless you specifically request a change.
Consider a driver who chose 50,000 dollars in bodily injury liability coverage per person and 100,000 dollars per accident five years ago. Medical costs have risen significantly since then, and a serious accident today could easily exceed those limits. If the driver never revisits the policy, the gap between their coverage and actual costs grows wider with every renewal. The same logic applies to property damage liability, uninsured motorist coverage, and medical payments coverage.
At each renewal, review whether your limits still reflect the current cost of medical care, vehicle repair, and legal defense in your state. Increasing liability limits often costs surprisingly little, sometimes just a few dollars per month, and it provides a critical safety net. Do not assume your insurer will prompt you to make this adjustment. The declarations page will show your limits, and it is your responsibility to confirm they remain adequate.
Review the Declarations Page for Accuracy at Every Renewal
The declarations page, often called the dec page, is the summary document that lists your vehicles, drivers, coverage types, limits, deductibles, and endorsements. Many policyholders file it away without reading it, assuming the renewal simply continues the prior policy unchanged. That assumption can be costly.
Errors and outdated information creep onto declarations pages in several common ways. A teenager who was added as an occasional driver may now be listed as a primary driver. A vehicle you sold last year may still appear on the policy. A garage address may be wrong after a move. A deductible may have changed without clear communication. Each of these issues can affect your premium and, more importantly, your coverage in the event of a claim.
Set aside ten minutes at each renewal to review the declarations page line by line. Confirm that every vehicle is correctly described, every household driver is listed accurately, and the coverage limits and deductibles match your intentions. If something looks wrong, contact your agent before the renewal takes effect. Correcting errors after a claim is far more difficult than catching them at renewal.
Use Renewal as a Trigger to Compare Fresh Quotes
The renewal notice is not just a bill; it is a strategic checkpoint. Insurers price policies based on risk pools and competitive positioning, and those factors shift constantly. A carrier that offered you a great rate three years ago may now be mid-pack or worse. Conversely, a carrier that once seemed expensive may have sharpened its pricing for your profile.
Comparing quotes at renewal does not require you to switch. It simply gives you information. You can use a competing quote to negotiate with your current insurer, or you can confirm that your existing policy remains a solid deal. Either outcome is valuable. Many drivers discover savings of 15 to 30 percent simply by running a fresh comparison every year or two.
Here is a simple renewal review framework you can follow:
- Read the renewal declarations page and confirm all vehicles, drivers, and coverage details are accurate.
- Check whether your liability limits still match the current cost of medical care and repairs in your area.
- Collect two or three fresh quotes from other carriers using identical coverage amounts.
- Compare the total annual premium, not just the monthly payment, and note any differences in deductibles or endorsements.
- Decide whether to stay, negotiate, or switch before the renewal date.
This process takes less than an hour and puts you in control of the outcome. It also protects you from the passive drift that leads so many policyholders to overpay year after year. For a broader set of money-saving tactics, explore our resources on auto insurance discounts and rate comparison strategies.
Other Renewal Myths Worth Correcting
Beyond the major misconceptions, several smaller myths circulate about renewals. One is that a lapse in coverage is harmless if you do not drive during the gap. In reality, even a one-day lapse can trigger higher rates at the next renewal and may create eligibility problems with some carriers. Another myth is that adding a new driver mid-term automatically raises your renewal premium by a predictable amount; the actual impact depends on the driver's record, age, and the vehicles they access.
A third myth is that renewal is the only time you can change your policy. You can typically adjust coverage, add or remove vehicles, and update driver information at any time during the policy term. Do not wait for renewal if your circumstances change. Prompt updates prevent coverage disputes and keep your premium aligned with your actual risk.
Finally, some drivers believe that filing a small claim will not affect their renewal because the insurer will forgive a first claim. Most carriers do offer accident forgiveness in certain circumstances, but the rules vary widely, and a claim can still influence your rate at renewal even if it does not trigger an immediate surcharge. Ask your agent how a claim would affect your specific policy before you decide whether to file.
Understanding these common misconceptions about auto insurance renewals puts you in a stronger position at every policy cycle. Renewal is not a passive event; it is an invitation to verify, compare, and optimize. Read the declarations page, question the loyalty assumption, confirm your limits, and shop the market. Those four habits alone can protect your finances and your peace of mind.