Debunking Myths About Filing Small Auto Insurance Claims
Debunking myths about filing small auto insurance claims helps you avoid needless premium hikes. Call (833)-275-7533 for a personalized coverage review.
By Beckett Nolan
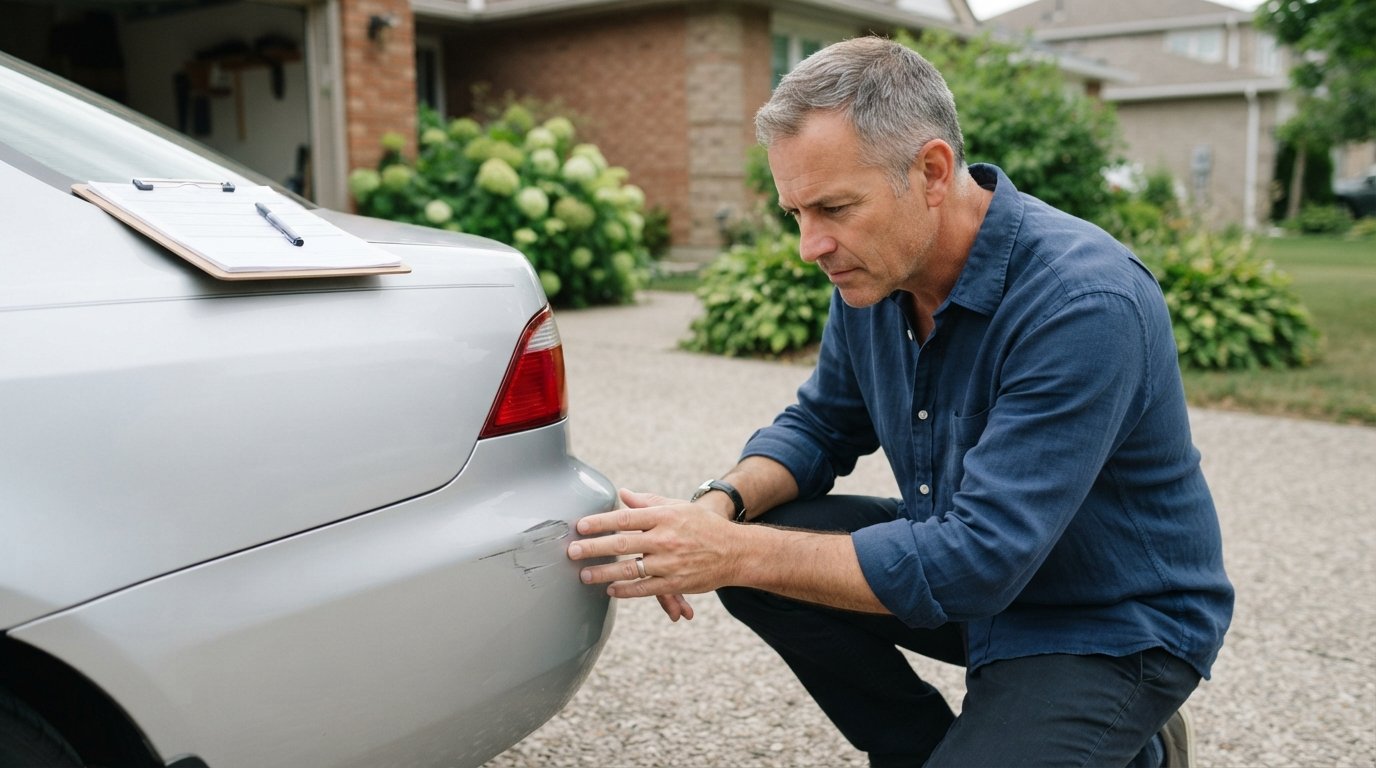
You notice a fresh scrape on your bumper or a small crack in the windshield. The repair estimate is modest, but a nagging voice asks: is it worth filing a claim? Many drivers automatically answer no, having absorbed a steady stream of warnings that small claims will wreck their insurance rates, follow them forever, and cost far more than paying out of pocket. Some of that caution is justified. Much of it is not. The gap between insurance folklore and actual claims reality costs drivers real money every year, in unreimbursed repairs, unnecessary premium hikes, and decisions made on fear rather than facts.
This guide walks through the most persistent misconceptions about small auto claims and replaces them with how the system actually works. You will see how insurers really evaluate claim frequency versus severity, how at-fault and not-at-fault claims differ, what happens when you switch carriers, and how your deductible should drive the decision. By the end, you will have a practical framework for deciding whether to file, pay out of pocket, or split the difference.
Myth 1: Any Claim You File Will Send Your Premiums Soaring
The most common belief is that filing even a minor claim triggers an immediate and dramatic rate increase. In reality, insurers price risk based on patterns, not isolated events. A single small comprehensive claim, such as a cracked windshield or a stolen side mirror, often has little or no effect on your renewal premium, especially if you have a clean history and the claim falls under comprehensive coverage.
What actually moves rates is a combination of fault, claim frequency, claim severity, and your overall risk profile. A $600 comprehensive claim is not treated the same as a $6,000 at-fault collision. Insurers look at whether the payout was recoverable through subrogation, whether you were responsible, and whether the claim suggests a habit of carelessness. A one-time, no-fault event is usually priced as noise. A pattern of small claims, however, signals something different and gets weighted accordingly.
That said, the myth is not entirely harmless fiction. Some states allow surcharges for at-fault claims above a certain dollar threshold, and insurers in competitive markets may apply them more aggressively. The smarter takeaway is not to assume every claim is dangerous, but to understand which claims actually carry weight in your state and with your carrier.
Myth 2: Claim Size Is What Matters Most
Drivers often assume a $500 claim is harmless and a $5,000 claim is catastrophic. From an underwriting perspective, the opposite can be closer to the truth. Frequency, meaning how often you file, is frequently a stronger predictor of future losses than the size of any single claim. Insurers have decades of data showing that a driver who files three small claims in two years is statistically riskier than one who files a single larger claim and then goes quiet.
This is why a string of minor incidents can hurt more than one moderate one. Each claim adds a data point, and the pattern matters more than the dollar figure attached to any individual event. If you are tempted to file for every small ding because "it is covered anyway," that habit can quietly erode your standing with carriers. Conversely, absorbing a small repair yourself and keeping your claims record clean preserves your negotiating position at renewal.
The practical rule: treat your claims history as a scarce resource. Spend it on events that genuinely strain your budget or involve another party, not on every minor scrape that comes along.
Myth 3: Not-at-Fault Claims Are Always Harmless
There is a widespread belief that if you were not at fault, filing a claim cannot affect you. That is only partly true. Liability and surcharges are typically tied to fault, so a not-at-fault claim usually will not trigger a surcharge the way an at-fault claim can. But insurers still track all claims, including not-at-fault ones, and some carriers use claim frequency in their rating algorithms regardless of fault.
Where this matters most is in states with no-fault systems or when you file under your own collision or comprehensive coverage instead of pursuing the other driver's liability coverage. In those cases, your insurer pays first, and the claim is recorded against your policy even if fault clearly rests elsewhere. Subrogation may recover the money later, but the claim event still exists in your history.
The better approach is to ask a direct question before filing: will this claim be recorded as at-fault, not-at-fault, or comprehensive? The answer determines whether a surcharge is likely and whether the claim could influence your renewal. If the other driver's insurer accepts liability quickly, pursuing their coverage directly can keep your own policy clean.
Myth 4: A Minor Claim Follows You Forever
Drivers often resist filing because they believe a small claim will haunt them for life. In practice, claims have a shelf life. Most insurers look back three to five years when pricing policies, and many states limit how long a claim can be used to justify a surcharge. A minor comprehensive claim from four years ago typically carries little or no weight today.
The more relevant question is whether the claim will follow you if you switch insurers. The answer is yes, but with nuance. Most carriers share claims data through industry databases, so a new insurer can see recent claims when you apply. However, they also see the context: fault, type of coverage, amount paid, and how long ago it occurred. A single small not-at-fault claim from two years ago is unlikely to be a dealbreaker. A cluster of recent at-fault claims is a different story.
If you are planning to shop for coverage, timing matters. Filing a claim right before you compare rates can complicate the process, while waiting until a claim ages off your record can improve your options. This is one reason it helps to review your claims history before requesting new quotes, so you know exactly what carriers will see.
Myth 5: Your Deductible Is the Only Number That Matters
The deductible is the most visible number in the claims decision, and it is genuinely important. If your deductible is $1,000 and the repair is $1,200, filing a claim nets you $200 while adding an event to your record. Most financial advisors would tell you to pay out of pocket in that scenario. But the deductible is not the only factor, and treating it as the sole test can lead to bad calls in both directions.
Consider what the claim actually involves. A comprehensive claim for a stolen catalytic converter or a cracked windshield often has minimal rating impact, so filing may make sense even when the payout is modest. An at-fault collision claim involving another vehicle carries more weight and may justify absorbing a higher cost yourself. Liability exposure also matters: if the incident injured someone or damaged property beyond your car, letting your insurer handle it is usually the right move regardless of the deductible.
Here is a simple framework for weighing the decision:
- Estimate the total repair cost, including rental car needs and any related expenses.
- Subtract your deductible to see the actual payout you would receive.
- Ask whether the claim will be recorded as at-fault, not-at-fault, or comprehensive.
- Check your state rules on surcharges and lookback periods for claims.
- Compare the payout against the likely premium impact over the next three years.
If the net payout is small and the claim type is one that insurers weigh heavily, paying out of pocket is often the cheaper path. If the claim is comprehensive, the other driver is clearly at fault, or the repair cost is genuinely burdensome, filing deserves serious consideration.
How Small Claims Actually Affect Your Policy Over Time
Insurers do not apply a single flat penalty for every claim. They build a risk profile that combines your driving record, claims history, credit-based insurance score where permitted, location, vehicle, and coverage choices. A small claim enters that profile as one data point among many, and its effect depends on how it interacts with everything else.
In practice, the drivers who see meaningful premium increases after small claims are usually those with multiple recent claims, at-fault incidents, or other risk factors already pushing their rates up. A driver with a clean record who files one comprehensive claim often sees little change at renewal. That is why blanket advice to never file small claims is misleading: it ignores the specifics that determine the outcome.
It also helps to understand that premiums are negotiable at renewal in ways many drivers never test. If a claim led to an increase, asking your agent how the claim was rated and whether any discounts apply can sometimes soften the impact. Shopping competing quotes is the stronger lever, and it is worth doing periodically regardless of claims history.
The Role of State Rules and Your Specific Policy
Insurance is regulated at the state level, so the rules that govern surcharges, lookback periods, and claims reporting vary significantly. Some states restrict how insurers can use not-at-fault claims, while others give carriers more latitude. Some require surcharges to phase out after a set number of years. Your policy language and your state's regulations together determine what a small claim actually costs you.
This is why generic advice found online often fails. A strategy that works well in one state may be unnecessary in another. Before making a decision, check your state insurance department's consumer guidance and read the claims-related sections of your policy. If the language is unclear, a quick call to your agent can clarify how a specific claim would be rated.
For drivers who want a broader picture of how rates vary by region and how to compare offers effectively, resources such as this guide to comparing Texas auto insurance quotes illustrate how location and carrier choice shape what you pay. The same principles apply nationwide: the more quotes you compare, the better your sense of what a fair rate looks like for your profile.
When Paying Out of Pocket Beats Filing
Paying out of pocket is often the smarter choice, but not always. The clearest cases for self-pay are small repairs close to your deductible, incidents where no other party is involved and the claim would be recorded as at-fault, and situations where you already have a recent claim on your record. In those scenarios, the payout is small relative to the risk of adding another event to your history.
There are also cases where filing is clearly better. If the repair cost substantially exceeds your deductible, if another driver was at fault and their insurer is slow to respond, if the incident involves injuries or property damage beyond your vehicle, or if the claim falls under comprehensive coverage with minimal rating impact, filing protects you from a large out-of-pocket hit and ensures the insurer handles any liability exposure.
A useful middle path is to get a repair estimate before deciding. Many body shops provide free estimates, and the number gives you a concrete basis for comparison. With the estimate in hand, you can run the deductible math and make a decision grounded in facts rather than fear.
Practical Steps to Make the Right Call
When a minor incident happens, a short sequence of steps keeps the decision clean and defensible. First, document the damage with photos and notes, including the date, location, and any other parties involved. Second, get a repair estimate from a reputable shop. Third, review your policy to confirm your deductible and how the claim would be classified. Fourth, check your state's rules on surcharges and claims lookback. Fifth, compare the net payout against the likely premium impact and make the call.
If you decide to file, contact your insurer promptly and provide complete information. If you decide to pay out of pocket, keep receipts and notes in case the issue resurfaces later. Either way, avoid filing and then withdrawing the claim repeatedly, since that pattern can create administrative complications and may still appear in claims databases.
It also pays to revisit your coverage choices annually. Raising your deductible can lower your premium, but it also changes the math on small claims. For drivers who rarely file, a higher deductible paired with a healthy emergency fund is often the most cost-effective structure. For drivers who value predictability, a lower deductible may be worth the higher premium.
Understanding these tradeoffs is part of a broader education in how coverage works. Independent resources such as NewAutoInsurance consumer guidance can help you compare coverage types and understand what different policies actually include, so you can make decisions that fit your budget and risk tolerance rather than reacting to myths.
Building a Claims Strategy That Fits Your Life
The best claims strategy is not a rigid rule like never file small claims. It is a personal framework built around your deductible, your claims history, your state rules, and your financial cushion. Drivers with emergency savings can comfortably absorb small repairs and preserve a clean claims record. Drivers without that cushion may reasonably use insurance for moderate claims, accepting a possible premium impact as the cost of avoiding debt.
What matters is making the decision deliberately rather than reflexively. Debunking myths about filing small auto insurance claims is ultimately about replacing fear with information. Once you know how frequency, fault, coverage type, and state rules interact, you can evaluate each incident on its merits and stop overpaying for repairs out of unfounded worry, or filing claims that quietly cost more than they return.
Take a few minutes today to review your policy's deductible, check your state's claims rules, and note your last few years of claims history. That small investment of time will make every future claims decision faster, clearer, and more likely to save you money.