Defensive Driving Course Discount Auto Insurance Guide
A defensive driving course can trim 5 to 15 percent off your auto insurance premium. See how the discount works and how to claim it.
By Kieran Maddox
You can lower your auto insurance premium by completing a state-approved defensive driving course, but the size of that discount and how long it lasts depend on your state, your insurer, and your driving record. Most drivers see savings between 5 and 15 percent, and in some states the discount is mandatory when you meet the requirements. That means a $1,500 annual premium could drop by $75 to $225 simply because you spent a few hours sharpening your driving skills. The catch is that not every insurer advertises this discount, and some apply it only to certain coverage types, so you need to know how to ask for it and how to verify the savings.
How a Defensive Driving Course Discount Auto Insurance Works
Defensive driving courses, sometimes called traffic safety courses or mature driver improvement courses, teach collision avoidance, hazard recognition, and safe following distance. Insurance companies reward drivers who complete them because statistically those drivers file fewer claims. The discount is a recognition that you present less risk than the average driver in your profile.
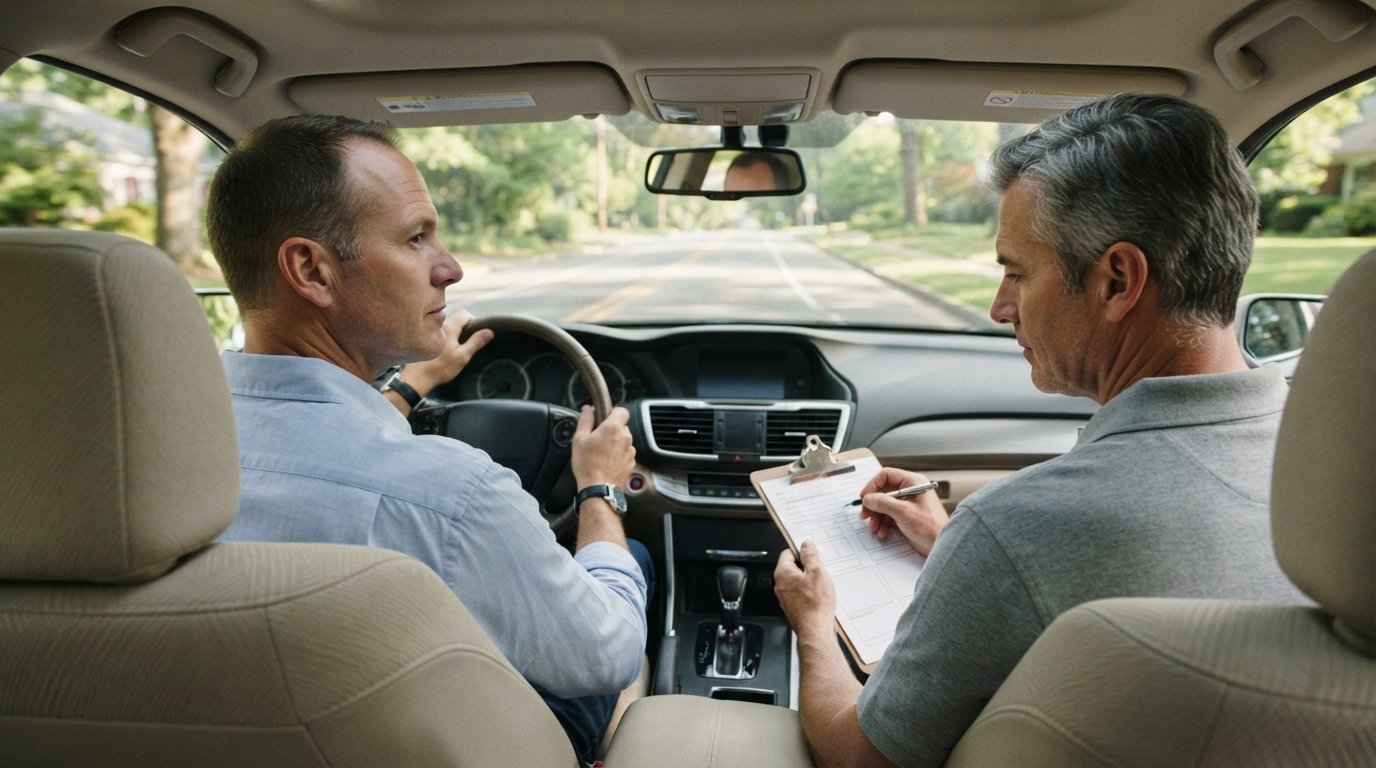
The mechanics are straightforward. You enroll in a course approved by your state's department of insurance or motor vehicles, complete the required hours (typically 4 to 8 hours, depending on the state and whether you take it online or in a classroom), and receive a certificate of completion. You then submit that certificate to your insurer. The insurer applies a discount to your premium, usually at your next renewal.
Discount amounts vary widely. Some carriers offer a flat percentage, while others use a tiered structure based on your age or the number of years since your last violation. In states like New York, California, and Texas, the discount is regulated, so insurers must offer a specific minimum percentage if you meet the criteria. In other states, the discount is voluntary, and the insurer decides whether to offer it and how much to give.
Here is what typically determines your eligibility and savings:
- State regulations: Some states mandate the discount, others allow it but do not require it, and a few do not recognize defensive driving for insurance purposes at all.
- Your driving record: A clean record usually qualifies you for the standard discount; a recent violation may require the course as a condition for reinstatement rather than a discount.
- Insurer policies: Each company sets its own percentage, renewal requirements, and which coverage the discount applies to (liability, collision, comprehensive, or the entire premium).
- Course approval: The course must be approved by your state; an unapproved online course will not qualify.
After you submit your certificate, the discount usually stays on your policy for three years, though some insurers require you to retake the course every two or three years to keep it. If you change insurers, you will generally need to submit the certificate again, and the new insurer may have a different discount percentage.
Which States Require Insurers to Offer the Discount
Several states have laws that require insurers to provide a defensive driving discount to qualifying drivers. New York, for example, mandates a 10 percent reduction on liability and collision premiums for three years for drivers who complete an approved accident prevention course. California requires insurers to offer a discount to drivers 55 and older who complete a mature driver course, though the amount varies by insurer. Texas does not mandate a specific percentage but does require insurers to offer a discount to drivers who complete a state-approved defensive driving course, and many carriers in Texas advertise discounts between 5 and 10 percent.
Other states, including Florida, Georgia, and Virginia, have similar provisions, but the details matter. In Florida, the discount is mandatory for drivers 55 and older who complete a state-approved course, and it applies to both liability and personal injury protection. In Georgia, insurers must offer a discount to drivers who complete a defensive driving course, but the percentage is not fixed. In Virginia, the discount is available to drivers who complete a course, but it is not mandatory for all insurers.
If you live in a state without a mandate, you can still ask your insurer whether it offers a voluntary discount. Many national carriers, including some of the largest, provide a defensive driving discount in most states even when not required by law. The key is to ask before you enroll, so you know whether the course will actually save you money.
How Much Can You Actually Save?
Savings from a defensive driving course discount auto insurance program typically range from 5 to 15 percent, but the exact amount depends on your base rate and the insurer's formula. A driver paying $1,200 per year might save $60 to $180 annually. A driver paying $2,500 per year (common for high-risk drivers or those with multiple vehicles) could save $125 to $375.
Some insurers apply the discount only to certain coverage lines. For example, an insurer might discount your liability premium by 10 percent but not your collision premium. Others apply the discount to the entire policy premium. You should ask your agent or customer service representative exactly how the discount is calculated and which coverages it affects.
It also helps to compare the discount against the cost of the course. State-approved online courses usually cost between $20 and $50, while classroom courses can run $50 to $100. If your discount saves you $100 per year for three years, that is a $300 return on a $30 investment, which is a strong return. However, if your insurer offers only a 3 percent discount on a $900 premium ($27 per year), the course may barely break even after the first year.
Here is a simple framework to evaluate whether the course is worth it for you:
- Ask your insurer for the exact discount percentage and which coverages it applies to.
- Multiply that percentage by your current annual premium to estimate your annual savings.
- Multiply the annual savings by the number of years the discount lasts (usually three).
- Subtract the cost of the course from that total to see your net savings.
If the net savings are positive and meaningful to you, the course is worth taking. If not, you may want to focus on other discounts or compare rates with other carriers instead.
How to Get the Discount: A Step-by-Step Approach
Getting the discount requires a bit of paperwork and follow-through, but the process is not complicated. Start by confirming that your insurer offers the discount and that the course you plan to take is approved in your state. Then complete the course, submit your certificate, and verify that the discount appears on your next billing statement.
Here are the steps in order:
- Check with your insurer. Call or log into your account and ask whether a defensive driving discount is available, what percentage it is, and which courses qualify.
- Find an approved course. Your state's department of insurance or motor vehicles website lists approved providers. Many are online and self-paced.
- Complete the course and get your certificate. Keep a digital copy and a printed copy in case your insurer asks for verification.
- Submit the certificate to your insurer. This can often be done by email, fax, or through your online account. Ask for confirmation that it was received.
- Verify the discount on your next renewal. Check your declarations page or billing statement to confirm the discount was applied. If it is missing, follow up immediately.
One common mistake is assuming the discount will be applied automatically. In most cases, you must submit the certificate yourself. Another mistake is taking a course that is not approved in your state, which means your insurer will not accept it. Always verify approval before you pay for the course.
If you are shopping for a new policy, mention the completed course when you request quotes. Some insurers will factor it into your quote immediately, while others will apply it after you provide the certificate. Either way, it can make your quote more competitive and help you secure a lower rate from the start.
Combining the Discount With Other Savings
A defensive driving discount is just one of many ways to lower your auto insurance premium. You can often stack it with other discounts, such as a multi-car discount, a safe driver discount, a paperless billing discount, or a pay-in-full discount. Stacking can turn a modest 8 percent savings into a 20 percent or larger reduction when combined with other offers.
For example, a driver in Texas might qualify for a 10 percent defensive driving discount, a 15 percent multi-car discount, and a 5 percent paperless discount. On a $1,500 premium, those three discounts could save $450 per year. The key is to ask your insurer which discounts you qualify for and how they interact. Some insurers cap the total discount percentage, so you will want to know the limits.
If you have not compared rates recently, a defensive driving course is also a good trigger to shop around. Different insurers weight discounts differently, so the same course might yield a larger discount with one carrier than another. You can use an independent comparison resource to review coverage options and see how rates vary by carrier. For example, NewAutoInsurance provides consumer guidance and educational content that can help you understand coverage choices and potential savings before you request quotes.
When you request quotes, be ready to provide your course certificate and ask each insurer how the discount applies. That way, you can compare the net cost of each policy after all discounts, not just the sticker price.
Who Benefits Most From the Discount
The defensive driving discount is especially valuable for certain driver profiles. High-risk drivers who have had a violation or accident may find that the course not only provides a discount but also helps them requalify for standard coverage. Young drivers and first-time drivers can use the course to demonstrate responsibility and offset some of the higher premiums that come with inexperience. Senior drivers, particularly those 55 and older, often qualify for mandated discounts in several states.
Drivers with multiple vehicles or families with teen drivers can also benefit because the discount applies per policy or per driver, depending on the insurer. If you have three drivers on your policy and two of them complete the course, some insurers will apply the discount to those drivers' portions of the premium. That can add up quickly.
Even if you are not in a high-risk category, the course can be a simple way to reduce your premium without changing your coverage or increasing your deductible. It is one of the few discounts that rewards you for something you can control: your driving knowledge and behavior.
Common Myths About the Defensive Driving Discount
There are several misconceptions about how the discount works. One myth is that any online course will qualify. In reality, the course must be approved by your state, and the provider must issue a certificate that your insurer recognizes. Another myth is that the discount applies forever. Most insurers require you to retake the course every two to three years to keep the discount active.
A third myth is that the discount is the same for everyone. The percentage can vary by insurer, by state, and by your driving record. Some insurers offer a higher discount to drivers who have a violation, as an incentive to improve, while others offer a lower discount to those same drivers. You should always confirm the specifics with your own insurer.
Finally, some drivers believe the discount will automatically lower their rate at renewal without any action on their part. As noted earlier, you usually need to submit the certificate. If you do not, the discount will not appear. Set a reminder to follow up after you complete the course so you do not miss out on the savings.
Maximizing Your Savings: Next Steps
To get the most from a defensive driving course discount auto insurance program, start by calling your insurer and asking three questions: Do you offer the discount, what percentage is it, and which courses are approved? Then find a state-approved course, complete it, and submit your certificate promptly. After the discount is applied, review your policy to confirm the savings and ask about other discounts you may qualify for.
If your current insurer does not offer a competitive discount, or if you want to see whether another carrier will give you a better rate, take a few minutes to compare quotes. You can request free, no-obligation quotes from multiple carriers and see how the defensive driving discount affects your options. The combination of a lower base rate and a stackable discount can lead to meaningful annual savings.
Defensive driving courses do more than lower your premium. They refresh your knowledge of safe driving practices, which can help you avoid accidents and tickets in the future. That, in turn, keeps your insurance costs down over the long term. Whether you are a high-risk driver looking to recover from a violation, a senior driver seeking a mandated discount, or a parent adding a teen to your policy, the course is a practical step toward safer driving and lower rates.