Hit by an Uninsured Driver in a No-Fault State: Next Steps
Hit by an uninsured driver in a no-fault state? Learn how PIP and UM coverage pay, and call (833)-275-7533 for expert guidance on your next steps.
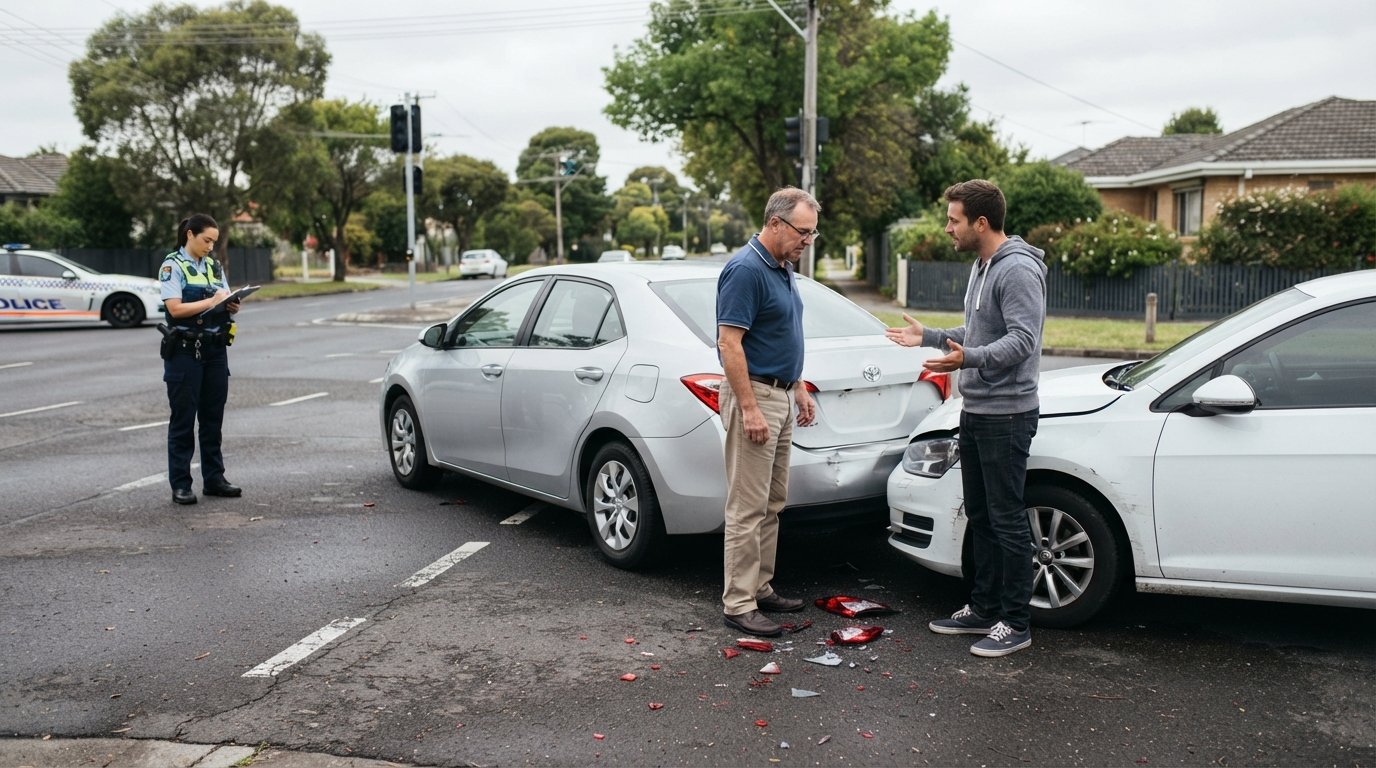
Your heart drops when the other driver admits they have no insurance. In a no-fault state, the situation feels even more confusing: you file with your own insurer first, but will your policy really cover everything? The answer depends on your coverage, your state's rules, and the steps you take in the first 48 hours. This guide walks you through exactly what to do if you are hit by an uninsured driver in a no-fault state, from the police report to the civil claim, so you can protect your recovery and avoid surprise bills.
How No-Fault Insurance Changes the Game After a Crash
In a no-fault state, your own personal injury protection (PIP) coverage pays for your medical bills and related expenses after an accident, regardless of who caused it. This is the cornerstone of the no-fault system: your insurer handles your injuries up to your PIP limit, and you generally cannot sue the other driver for pain and suffering unless your injuries meet a serious threshold. The trade-off is speed and simplicity, but when the other driver is uninsured, that simplicity can feel like a trap. Your PIP coverage may be modest, and the at-fault driver has no liability insurance to pick up the rest.
Twelve states (plus Puerto Rico) use no-fault rules in some form: Florida, Hawaii, Kansas, Kentucky, Massachusetts, Michigan, Minnesota, New Jersey, New York, North Dakota, Pennsylvania, and Utah. Each sets its own PIP minimums, deadlines, and lawsuit thresholds. For example, Florida requires $10,000 in PIP, while Michigan historically required unlimited PIP before recent reforms. The key takeaway is that in a no-fault state, you start by filing a claim with your own insurer, even when the other driver is clearly at fault.
That first-party claim is your lifeline, but it is not the end of the story. If your PIP benefits run out, or if you have injuries that qualify for a liability claim, you may need to look to other coverage, such as uninsured motorist (UM) or underinsured motorist (UIM) protection. Understanding this hierarchy is essential when you are hit by an uninsured driver in a no-fault state.
Immediate Steps at the Scene and in the First 48 Hours
What you do in the minutes and hours after the crash can determine how smoothly your claim proceeds. Even in a no-fault state, you need to document the fact that the other driver was uninsured and establish the extent of your damages. Start by ensuring everyone is safe and calling 911 if there are injuries. Then, gather information methodically.
- Call the police and get a report. A police report is crucial evidence, especially when the other driver lacks insurance. It creates an official record of the crash, the parties involved, and any citations issued. Ask the responding officer for the report number and how to obtain a copy.
- Exchange information and confirm insurance status. Collect the other driver's name, contact details, license plate, and vehicle information. If they admit to having no insurance, note that in your phone or a notebook. Do not argue or accuse; simply document.
- Photograph everything. Take pictures of vehicle damage, the scene, road conditions, and any visible injuries. If there are witnesses, ask for their contact information.
- Notify your insurer promptly. Most policies require prompt notice of an accident. Call your insurer's claims line, report the crash, and open a PIP claim. Mention that the other driver was uninsured so they can note it for potential UM/UIM claims.
- Seek medical attention. Even if you feel fine, some injuries (like whiplash or concussions) appear later. A medical record also strengthens your PIP claim and any future liability claim.
These steps create a paper trail that supports your version of events. Without a police report or timely notice to your insurer, you risk delays or denials. In no-fault states, insurers are strict about deadlines, so act quickly and keep copies of everything you submit.
How PIP and Uninsured Motorist Coverage Work Together
In a no-fault state, PIP is your first source of recovery for medical expenses, lost wages, and sometimes other expenses, regardless of fault. But PIP limits vary widely. If your injuries are severe and your PIP coverage is exhausted, you may then turn to your uninsured motorist (UM) coverage. UM coverage is designed for situations exactly like this: the at-fault driver has no liability insurance. In some no-fault states, UM coverage may also apply to bodily injury claims that exceed the no-fault threshold.
UM coverage typically pays for medical bills, lost wages, and pain and suffering that would have been covered by the at-fault driver's liability insurance. UIM coverage, by contrast, applies when the at-fault driver has some insurance but not enough to cover your damages. Both are optional in some states and mandatory in others, so check your policy declarations page. If you do not have UM/UIM, you may still have a claim under your collision coverage for vehicle damage, but your injuries would be limited to PIP and any health insurance you carry.
One common pitfall: insurers may try to offset UM payments by the amount you received in PIP benefits. Policy language and state law govern whether such offsets are allowed. Review your policy carefully or consult a consumer advocate. The interplay between PIP and UM is one of the most misunderstood aspects of no-fault insurance, and it is where a knowledgeable agent or attorney can add real value.
Filing a Claim with Your Insurer: A Step-by-Step Walkthrough
Once you have notified your insurer, the claims process begins. In a no-fault state, your PIP claim should proceed without regard to fault, but you still need to provide documentation. Expect to submit medical records, bills, wage loss verification, and a police report. Keep a claim diary with dates, names, and what was discussed. If your insurer delays or denies benefits, ask for the denial in writing and the specific policy provision relied upon.
If you also have UM coverage, you may need to file a separate UM claim. Some insurers handle both under one claim number, but the UM claim will require proof that the other driver was uninsured. A police report or a statement from the other driver can serve this purpose. If the other driver's insurance status is unclear, your insurer may investigate. Be patient but persistent.
For vehicle damage, your collision coverage (if you have it) will pay for repairs, minus your deductible. Your insurer may then attempt subrogation against the uninsured driver, but recovery is often unlikely. That is why many drivers in no-fault states choose to carry UM/UIM and collision coverage, even though they are not always required. When you are hit by an uninsured driver in a no-fault state, your own policy is your primary safety net.
Can You Sue an Uninsured Driver in a No-Fault State?
Yes, but with limits. No-fault laws restrict lawsuits for pain and suffering unless your injuries meet a certain threshold, often described as serious, permanent, or disabling. If your injuries qualify, you may sue the at-fault driver for damages beyond PIP. However, collecting from an uninsured driver is another matter. Many uninsured drivers have few assets, so a judgment may be uncollectible. That said, a civil claim can still be worthwhile if the driver has assets or if you want to establish liability for other purposes.
Before suing, consider whether your UM coverage can compensate you without litigation. UM claims are typically faster and more reliable than pursuing an uninsured driver. If you do pursue a civil claim, consult an attorney who understands your state's no-fault threshold and statute of limitations. In most states, the statute of limitations for personal injury is two to three years, but no-fault claims may have shorter deadlines for PIP benefits.
It is also worth noting that some no-fault states allow lawsuits for economic damages (like medical bills) that exceed PIP limits, even if you do not meet the pain and suffering threshold. The rules are state-specific, so research your state or speak with a local professional.
Documenting Your Damages and Protecting Your Recovery
Whether you pursue a PIP claim, a UM claim, or a civil lawsuit, documentation is your strongest ally. Keep all medical records, receipts, pay stubs, and correspondence. Take photos of your injuries as they heal. If you miss work, get a note from your employer or doctor. If you incur travel costs for medical appointments, track them. These details add up and can make the difference between a fair settlement and a lowball offer.
Be cautious with recorded statements. Insurers may ask for a recorded statement early on. You are generally required to cooperate with your own insurer, but you can ask to review the statement or provide a written statement instead. Avoid speculating about fault or the extent of your injuries. Stick to the facts you know.
If your claim is complex, or if the insurer disputes coverage, consider consulting a consumer advocate or attorney. Many offer free consultations. For general guidance on related scenarios, such as when the other driver flees the scene, see our guide on hit-and-run with no insurance, which covers similar documentation and claim strategies.
Reviewing Your UM and UIM Limits for Future Protection
The best time to protect yourself from uninsured drivers is before an accident happens. If you are hit by an uninsured driver in a no-fault state, your UM and UIM limits determine how much compensation you can receive beyond PIP. Many drivers carry the state minimum, which may be far too low to cover serious injuries. When you shop for auto insurance, ask for quotes with higher UM/UIM limits. The cost is often modest compared to the potential benefit.
Also consider stacking UM coverage if your state allows it. Stacking combines the UM limits from multiple vehicles on your policy, increasing your available coverage. Not all states permit stacking, and insurers may charge extra, but it can be a valuable safeguard in no-fault states where PIP limits are low. For a broader look at coverage options and rate comparisons, you can explore independent resources like NewAutoInsurance, which provides educational content on auto insurance for U.S. drivers.
Finally, review your policy annually or after any major life change. Adding a new vehicle, moving to a different state, or changing your commute can affect your coverage needs. A quick review with a licensed agent can help you avoid gaps and ensure you have adequate protection if you are ever hit by an uninsured driver in a no-fault state.
When to Get Help and How to Compare Quotes
If your claim is denied, delayed, or undervalued, do not hesitate to escalate. Start with your insurer's claims supervisor, then your state's department of insurance. Many states offer consumer complaint portals. If you are considering a civil claim, an attorney can advise you on the merits and costs. Remember that no-fault laws are complex, and what works in Florida may not work in New York.
For most drivers, the most practical step is to ensure your own coverage is robust. Compare quotes from multiple carriers to find affordable UM/UIM and PIP options. Free Auto Insurance Quotes Online lets you request personalized quotes from licensed agents with no obligation. It takes minutes and could save you thousands if you are ever hit by an uninsured driver in a no-fault state.
Being hit by an uninsured driver is stressful, but you are not powerless. By acting quickly, documenting thoroughly, and understanding how PIP and UM coverage interact, you can maximize your recovery and protect your financial future.