How Advanced Driver Assistance Systems Affect Insurance
Advanced driver assistance systems affect insurance premiums in complex ways. Call 8332757533 to compare quotes and find out if your car's safety tech earns a discount.
By Evelin Cross
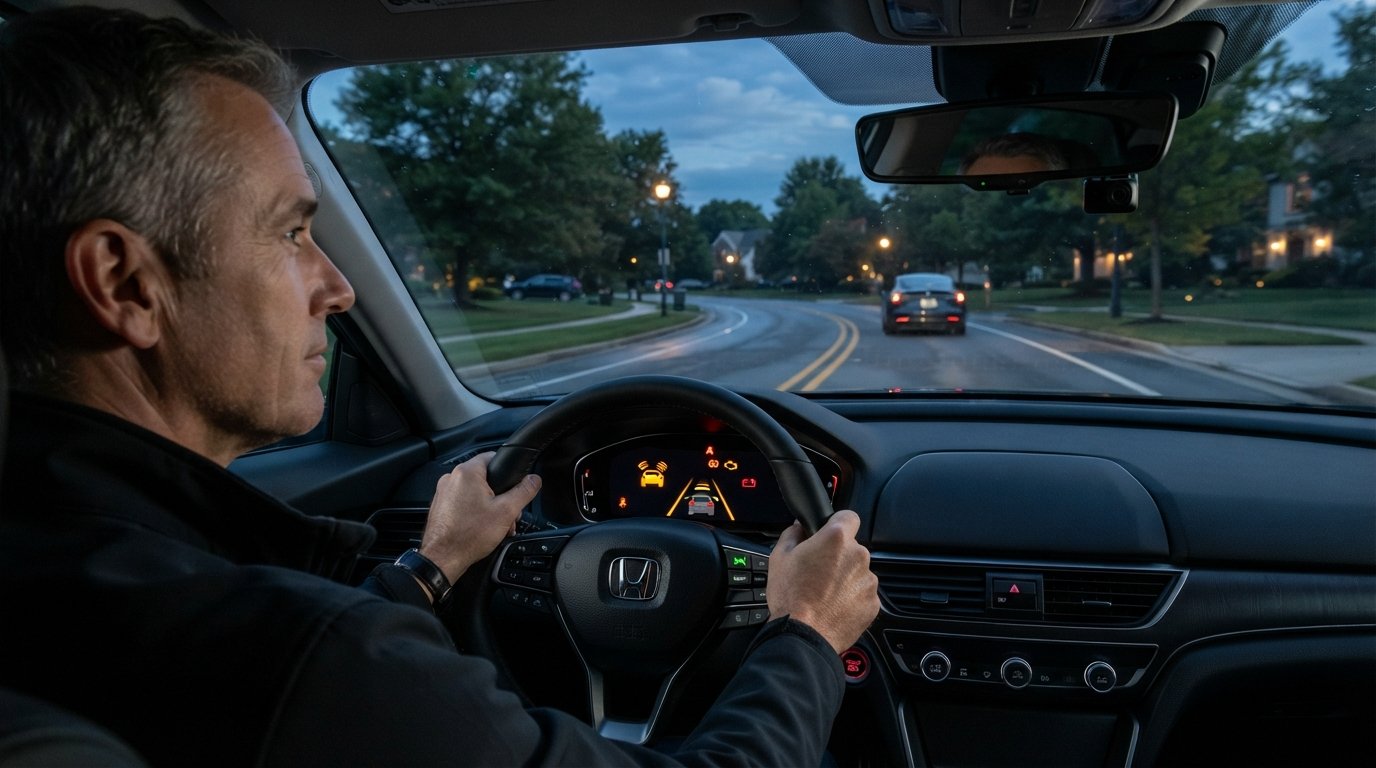
A car that brakes itself before you even see the hazard, a steering wheel that nudges you back into your lane, a dashboard that warns you someone is sitting in your blind spot: advanced driver assistance systems (ADAS) have quietly become standard equipment on most new vehicles sold in the United States. Automakers market these features as a path to fewer crashes, and federal regulators have even brokered voluntary agreements to make automatic emergency braking standard on nearly every new light vehicle. So it seems logical that drivers would expect a break on their car insurance premiums for owning a safer car. The reality is more complicated, and understanding how advanced driver assistance systems affect insurance premiums can save you money, prevent unpleasant surprises at renewal, and help you ask the right questions when you compare quotes.
What Counts as an Advanced Driver Assistance System?
ADAS is an umbrella term for a group of electronic safety features that either warn the driver about a hazard or actively intervene to prevent or reduce the severity of a crash. They rely on cameras, radar, lidar, ultrasonic sensors, and increasingly artificial intelligence to perceive the road environment in real time. The exact feature list varies by manufacturer, trim level, and model year, but most systems fall into a few recognizable categories.
The most common ADAS features you will encounter on a dealership lot or in a used-car listing include the following:
- Automatic emergency braking (AEB): detects an imminent front-end collision and applies the brakes if the driver does not respond in time.
- Forward collision warning: alerts the driver to a slowing or stopped vehicle ahead.
- Lane departure warning and lane keeping assist: alerts the driver when the car drifts out of its lane, and in some systems, gently steers it back.
- Blind spot monitoring: illuminates a warning in the side mirror or door pillar when another vehicle is in an adjacent lane.
- Adaptive cruise control: maintains a set speed while automatically adjusting to the pace of traffic ahead.
- Rear cross traffic alert and backup cameras: help drivers avoid collisions while reversing out of parking spaces and driveways.
Some vehicles add more advanced features such as driver attention monitoring, automatic high beams, pedestrian detection, and semi-autonomous highway driving assistants. Insurance companies generally treat these systems as safety equipment, similar to how they view airbags and electronic stability control, though the financial credit they extend for ADAS varies widely. It is important to note that ADAS is not the same as fully autonomous driving. Even the most sophisticated system on the road today requires an engaged driver who is ready to take control at any moment.
The Core Question: Do ADAS Features Lower Your Premium?
In theory, yes. Insurance premiums are fundamentally a reflection of risk. When a carrier believes a driver is less likely to file a claim, or that claims will be less expensive when they do occur, that carrier can offer a lower rate. Studies from the Insurance Institute for Highway Safety and other research organizations have found that certain ADAS features, particularly automatic emergency braking and forward collision warning, are associated with meaningful reductions in rear-end crashes and related injury claims. That is the mechanism through which ADAS can influence what you pay.
In practice, the answer is: sometimes, and usually not as much as drivers hope. Most major insurers do not advertise a standalone "ADAS discount" the way they advertise safe-driver, multi-policy, or good-student discounts. Instead, the value of ADAS tends to be baked into the base rate for a given vehicle, or reflected in how a carrier classifies your car's safety profile. A 2026 model with a full suite of standard safety technology may simply rate better than an older vehicle without it, even if no line item on your declarations page says "ADAS credit."
There are also exceptions. Some carriers do offer explicit credits or endorsement programs for vehicles equipped with specific safety systems, and a handful of insurers have filed new rating plans that reward vehicles with proven crash-avoidance technology. The catch is that these programs are not universal. Availability depends on your state, your carrier, and the specific features your vehicle has. That is why the most reliable way to find out whether your ADAS-equipped car earns a discount is to compare personalized quotes from multiple carriers rather than assume the savings will appear automatically. A platform like NewAutoInsurance can help you see how different insurers treat the same vehicle, which is often the fastest way to spot a carrier that actually rewards your car's safety technology.
Why ADAS Does Not Always Reduce Premiums
If ADAS prevents crashes, why would any insurer hesitate to lower rates? The answer lies in the economics of repairing modern vehicles. The same sensors, cameras, and radar units that help avoid collisions are expensive to replace when a collision does happen, and they must be recalibrated after even minor bodywork. A cracked windshield on a car with a forward-facing camera can turn a few-hundred-dollar glass replacement into a four-figure repair once calibration is included.
That reality has a direct effect on the two largest components of a typical auto insurance premium: collision coverage and comprehensive coverage. When repair costs rise, insurers pay more per claim, and those costs eventually flow back to policyholders in the form of higher base rates. Some industry analysts have described this as a tug-of-war between frequency and severity. ADAS may reduce how often claims happen, but it can increase how much each claim costs. Depending on which force is stronger for a given vehicle and driver, the net effect on premiums can be neutral, modestly positive, or even negative.
There are several other factors that complicate the picture:
- Driver behavior: some research suggests drivers with advanced safety features may take more risks or pay less attention because they trust the technology, a phenomenon known as risk compensation.
- System limitations: ADAS performs poorly in heavy rain, snow, direct sunlight, or poorly marked roads, which means real-world effectiveness can lag behind test-track results.
- Repair network constraints: not every body shop has the equipment or training to recalibrate ADAS sensors, which can lengthen repair times and increase rental car costs.
- Parts availability: sensor and camera modules are often proprietary, and supply chain issues can drive up both repair costs and total loss frequency.
In other words, ADAS is not a magic switch that automatically lowers your bill. It is one variable among many that carriers weigh when they set rates, and its impact depends heavily on the specific technology, the vehicle it is installed on, and the insurer's own claims experience.
How Insurers Actually Evaluate ADAS When Setting Rates
Insurance companies use a combination of actuarial data, vehicle symbol ratings, and proprietary claims analysis to decide what a particular car should cost to insure. When a new model year arrives, carriers look at crash test results, repair cost estimates, theft rates, and increasingly, the presence and performance of ADAS features. A vehicle that earns a Top Safety Pick designation from the Insurance Institute for Highway Safety, partly because of its crash-avoidance technology, often receives a more favorable rating than a comparable vehicle without those features.
Beyond the vehicle itself, insurers may consider how ADAS interacts with the driver. For example, a carrier might offer a small discount to policyholders who complete a defensive driving course that covers how to use ADAS properly, or it might factor in telematics data that shows a driver is using adaptive cruise control and lane keeping consistently. Some insurers have experimented with usage-based programs that reward safe driving patterns regardless of whether ADAS is present, effectively capturing the same benefit through a different mechanism.
It also matters whether the ADAS features were factory-installed or added after purchase. Factory equipment is easier for insurers to verify and is typically included in the vehicle identification number decode, which means it is automatically reflected in the rating. Aftermarket systems, by contrast, may not be recognized at all, and in some cases, they could even complicate a claim if they are deemed to have contributed to a crash or if their installation voided a warranty.
What to Tell Your Insurer About Your Vehicle's Safety Features
Many drivers never mention their ADAS features when they buy a policy, assuming the insurer already knows. That assumption is not always correct, especially for older vehicles that were retrofitted or for trims where a feature was optional. When you request quotes, be specific about what your car has. Instead of saying "it has safety features," list them: automatic emergency braking, blind spot monitoring, lane keeping assist, adaptive cruise control, rear cross traffic alert. Ask each carrier directly whether it offers a credit or rating adjustment for any of those systems.
If you are shopping for a new or used car, it also pays to think about insurability before you sign. Two vehicles with similar sticker prices can have very different insurance costs depending on their safety technology, repair costs, and theft history. Getting quotes on a specific make and model before you buy is one of the simplest ways to avoid a nasty surprise. You can start by requesting free, no-obligation quotes from multiple carriers and comparing how each one rates the vehicle you are considering.
Which ADAS Features Tend to Have the Biggest Impact?
Not all ADAS features are created equal in the eyes of insurers. The ones that have demonstrated the strongest real-world crash reduction tend to carry the most weight, while features that mainly improve convenience or comfort have little to no effect on premiums. Based on available research and insurer practices, the features most likely to influence your rate include automatic emergency braking, forward collision warning, blind spot monitoring, and rear cross traffic alert. Adaptive cruise control and lane keeping assist can help, but their insurance impact is usually smaller because they address crash types that are less frequent or less severe.
It is also worth noting that the effectiveness of any single feature depends on how it is calibrated and how the driver uses it. A well-tuned AEB system that works at both low and high speeds is more valuable than one that only operates in stop-and-go traffic. Similarly, a blind spot monitor that covers a wide area and provides both visual and audible alerts is more useful than one that only lights up a small icon. When you are comparing vehicles or talking to an insurer, ask about the specific capabilities of the system, not just whether it exists.
Practical Steps to Turn ADAS Into Real Savings
If you own a vehicle with advanced safety features, or you are about to buy one, there are concrete steps you can take to make sure you are not leaving money on the table. The goal is to make your car's safety technology visible to insurers and to compare enough quotes that you can identify which carriers actually reward it.
- Document your features: gather the window sticker, owner's manual, or a VIN decode report that lists every ADAS feature on your vehicle. This makes it easy to provide accurate information when you request quotes.
- Ask every carrier the same question: when you compare quotes, ask each insurer whether it offers a discount or rating adjustment for automatic emergency braking, blind spot monitoring, or any other system your car has.
- Compare at least three to five carriers: because ADAS credits are not standardized, the only way to know who rewards your vehicle is to get multiple quotes side by side.
- Re-shop at renewal: rating plans change, and a carrier that ignored ADAS last year may have filed a new program this year. A quick comparison at renewal can reveal new savings.
- Consider a telematics program: if your insurer does not offer an ADAS credit, a usage-based program that rewards safe driving may capture similar savings through a different route.
These steps are simple, but they require a little effort. The payoff can be meaningful, especially for drivers of newer vehicles where the gap between the cheapest and most expensive quote for the same car can be hundreds of dollars per year. Taking an hour to gather your feature list and request quotes from several carriers is often the highest-return activity in personal finance.
The Road Ahead: How ADAS and Insurance Will Evolve
As ADAS becomes more capable and more widespread, its relationship with insurance will continue to shift. Regulators are paying closer attention to how these systems perform in the real world, and some are considering rules that would require crash-avoidance technology to be standard equipment. Automakers are collecting enormous amounts of data from these systems, and in the future, insurers may be able to use that data to offer more precise rates based on how a specific vehicle's safety technology performs in specific conditions. At the same time, the cost of repairing and recalibrating sensors will keep pressure on premiums, particularly for collision and comprehensive coverage.
For drivers, the practical takeaway is that ADAS is neither a guaranteed discount nor a reason to expect higher rates. It is a factor that insurers weigh, sometimes explicitly and sometimes quietly, alongside your driving record, location, credit-based insurance score, and the vehicle itself. The best strategy is to stay informed, ask direct questions, and compare quotes from multiple carriers every time you shop. That approach puts you in the best position to benefit from whatever credits your vehicle qualifies for, while avoiding the trap of assuming that a safer car automatically means a cheaper policy.
Whether you are buying your first car with automatic emergency braking, adding a teenage driver to a policy, or simply wondering why your premium changed after trading in an older vehicle, understanding how advanced driver assistance systems affect insurance premiums gives you leverage. Use it to ask better questions, gather better quotes, and keep more of your money in your pocket.