Medical Payments Coverage vs Personal Injury Protection
Medical payments coverage vs personal injury protection: understand the key differences in coverage for medical bills and lost wages to choose the right policy for your needs.
By Dominic Ashby
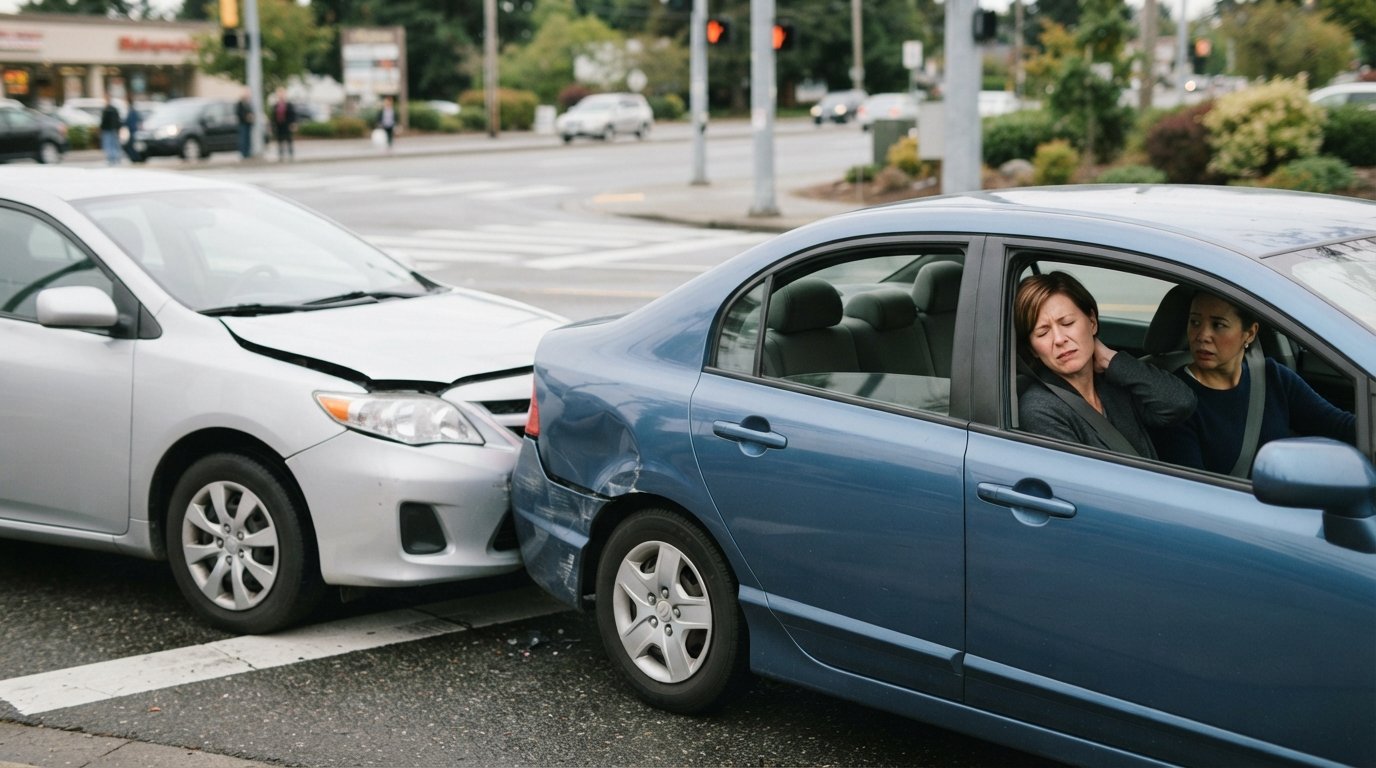
Imagine you are sitting at a red light, and suddenly, you hear screeching tires. Before you can react, another driver slams into the back of your car. In the chaos that follows, your immediate concern is not who is at fault or how much the repair will cost. Your first thought is likely about your physical well-being and that of your passengers. This is where the distinction between Medical Payments Coverage (MedPay) and Personal Injury Protection (PIP) becomes not just an insurance technicality, but a lifeline for your financial and physical recovery.
Many drivers assume that if they are not at fault, the other driver's insurance will immediately cover their medical bills. The reality is often much slower and more complicated. While you wait for liability to be determined, your own health insurance might demand copays, or you might face high deductibles. Understanding how MedPay and PIP function can mean the difference between focusing on your recovery and fighting with billing departments. For those looking to understand how these fit into a broader policy, exploring Understanding Full Coverage Auto Insurance Options provides a solid foundation.
What Is Medical Payments Coverage (MedPay)?
Medical Payments Coverage, commonly referred to as MedPay, is an optional addition to your auto insurance policy that helps pay for medical and funeral expenses for you and your passengers. This coverage applies regardless of who caused the accident. If you are driving, riding as a passenger in someone else's car, or even walking and struck by a vehicle, MedPay can step in to handle costs that your health insurance might not cover.
Think of MedPay as a health insurance supplement specifically for auto accidents. It is designed to be fast and efficient. Because it is fault-free, you do not have to wait for the other driver's insurance company to accept responsibility before your bills get paid. This speed is crucial for those who need immediate treatment, such as X-rays, ambulance rides, or emergency room visits. MedPay typically covers:
- Hospital visits and emergency room care
- Doctor and surgeon fees
- Ambulance and EMT services
- X-rays and diagnostic imaging
- Funeral expenses (up to the policy limit)
However, MedPay has limits. Standard limits often range from $1,000 to $10,000. Once the limit is reached, the coverage stops. It also does not typically cover lost wages or rehabilitation costs, which are significant considerations if you are unable to work while healing.
What Is Personal Injury Protection (PIP)?
Personal Injury Protection, or PIP, is a much broader coverage than MedPay. In states that require it (often called "no-fault" states), PIP is mandatory. Like MedPay, PIP pays out regardless of fault. However, its scope extends far beyond just medical bills. PIP is designed to cover the "human costs" of an accident, ensuring that injured parties can maintain some semblance of normalcy while they recover.
The primary difference is that PIP includes wage loss coverage. If you are seriously injured and cannot work for three months, PIP can replace a portion of that lost income (usually 60% to 80%). It also covers essential services you cannot perform yourself, such as cleaning, cooking, or childcare. Furthermore, PIP often covers rehabilitation costs, which can be extensive after a severe crash.
While PIP is mandatory in some states like Florida, New York, and Michigan, it is optional in others. In states where it is optional, drivers must weigh the higher premium cost against the comprehensive protection it offers. For families with multiple vehicles, the peace of mind that comes with wage-loss protection often justifies the expense.
Key Differences: MedPay vs. PIP
The most significant distinction lies in the breadth of coverage. MedPay is strictly for medical expenses, while PIP is a comprehensive package that includes medical, lost wages, and other essential services. This difference is critical when evaluating your financial exposure after a crash.
Another difference is cost. Because PIP offers more coverage, it generally comes with a higher premium than MedPay. In states where both are available, you might be asked to choose one or the other, or you may be able to purchase both. If you have excellent health insurance with low deductibles, you might feel that MedPay is sufficient to cover the gaps. However, if you are self-employed or your job does not offer paid sick leave, PIP is the safer bet to protect your income.
Here is a quick breakdown of how these coverages compare:
- Medical Expenses: Both cover this, but PIP often has higher limits.
- Lost Wages: Only PIP covers this critical expense.
- Essential Services: PIP covers chores like housekeeping; MedPay does not.
- Availability: MedPay is available in most states; PIP is mandatory in no-fault states and optional in others.
- Cost: MedPay is generally cheaper; PIP is more expensive due to broader coverage.
Understanding these nuances helps you tailor your policy to your lifestyle. For instance, a retiree on Medicare might find MedPay sufficient, while a young professional without sick days would benefit from PIP.
How State Laws Impact Your Choice
Where you live dictates your options. In "no-fault" states, PIP is the law. This system is designed to reduce lawsuits by ensuring everyone's medical bills are paid by their own insurer, regardless of who caused the crash. In these states, you cannot opt out of PIP; it is a standard part of every policy.
In "at-fault" or "tort" states, the driver who causes the accident is responsible for the damages. In these states, MedPay is usually the optional add-on available. Some states, like Texas, allow drivers to reject PIP coverage in writing, opting instead for MedPay or nothing at all. This flexibility means you must be proactive in selecting your coverage.
It is also worth noting that in some states, your health insurance may be the primary payer, and auto insurance is secondary. In others, auto insurance pays first. This coordination of benefits can be confusing. If you are unsure how your state handles this, it is wise to consult with a licensed agent who understands local regulations. You can also visit NewAutoInsurance for additional educational resources on navigating these complex insurance landscapes.
Why You Should Consider Adding MedPay or PIP
Even if your state does not mandate PIP or MedPay, adding it to your policy is often a smart financial move. Health insurance policies frequently have high deductibles and out-of-pocket maximums. A serious car accident can easily result in tens of thousands of dollars in medical bills. Without MedPay or PIP, you could be stuck paying those deductibles before your health insurance kicks in.
Furthermore, health insurance does not cover lost wages. If you are the primary breadwinner for your family and you are sidelined by an injury, the financial impact can be devastating. PIP ensures that the bills keep getting paid while you heal. It is a small price to pay for financial stability during a crisis.
For drivers with high-risk profiles or those seeking to lower their premiums, understanding the cost-benefit analysis of these coverages is essential. While you might be tempted to drop them to save a few dollars a month, the risk of being underinsured is far greater. A single accident can wipe out savings accumulated over years.
How to Choose the Right Coverage for You
Deciding between MedPay and PIP, or whether to buy them at all, depends on several personal factors. You need to assess your health insurance, your savings, and your income stability. If you have a robust emergency fund and generous health insurance, you might opt for a lower limit or skip it. But for most people, the protection is worth the cost.
To make the best decision, follow these steps:
- Review your health insurance: Check your deductible and copays. If they are high, you need MedPay or PIP.
- Evaluate your income: If you cannot afford to go weeks without a paycheck, you need PIP.
- Check your state laws: Determine if PIP is mandatory or optional where you live.
- Get quotes: Ask your insurer how much it costs to add these coverages. Often, the increase is minimal.
Once you have this information, you can make an informed decision. Remember that the goal of insurance is to transfer risk. By paying a small premium now, you transfer the massive risk of a medical catastrophe to the insurance company.
The Bottom Line on MedPay vs. PIP
Medical Payments Coverage and Personal Injury Protection are both designed to protect you after an accident, but they do so in different ways. MedPay is a focused tool for medical bills, while PIP is a comprehensive safety net that includes income replacement. The right choice for you depends on your state's laws, your health insurance, and your financial situation.
Do not wait until after an accident to realize you are underinsured. Take the time to review your policy today. Whether you need to add PIP for wage protection or MedPay to cover a high health insurance deductible, having the right coverage provides peace of mind. When you are ready to explore your options, you can get a quote to see how affordable adding these protections can be.