MedPay Coverage: Do You Need It With Health Insurance?
Medical payments coverage can fill gaps your health plan leaves after a crash, covering copays and passengers. Call (833)-275-7533 to compare quotes.
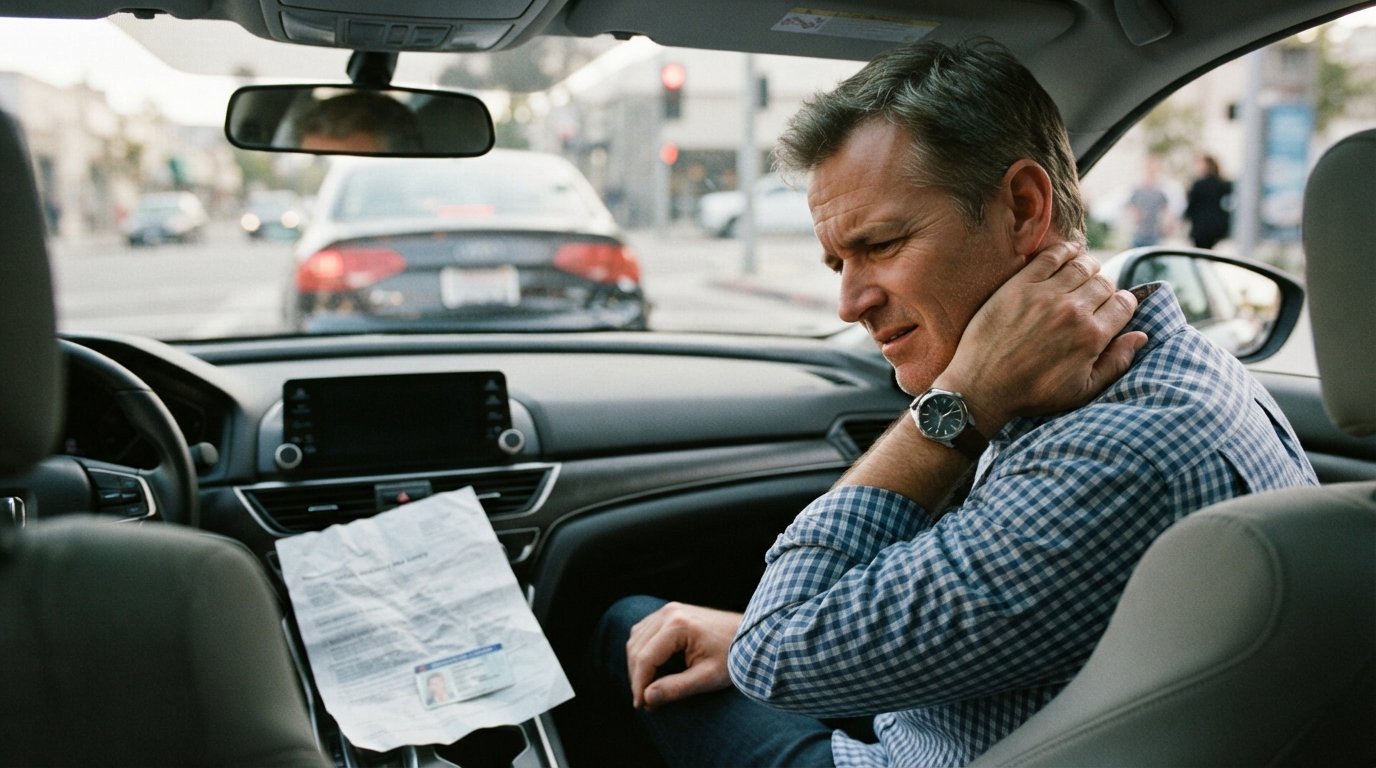
You are sitting at a red light when a distracted driver rear-ends your car. Everyone walks away, but the next morning your neck is stiff and your passenger has a splitting headache. Your health insurance card is in your wallet, so you assume you are covered. Then the bills start arriving: emergency room copays, imaging deductibles, and out-of-network charges. This is the exact moment many drivers discover the gap between what health insurance pays and what a car crash actually costs. Medical payments coverage, commonly called MedPay, exists to close that gap. But if you already pay for health insurance, is MedPay redundant? The answer depends on your health plan, your state, and how much risk you are willing to absorb. This guide breaks down what medical payments coverage is, how it interacts with health insurance, and how to decide whether you need it.
What Is Medical Payments Coverage?
Medical payments coverage is an optional add-on to an auto insurance policy that pays for medical and funeral expenses for you and your passengers after a car accident, regardless of who caused the crash. It is a no-fault benefit, meaning your insurer pays up to your chosen limit without waiting for a liability investigation or a court judgment. MedPay typically covers reasonable and necessary medical care such as ambulance rides, emergency room visits, doctor appointments, X-rays, surgery, hospital stays, and sometimes dental work caused by the accident. It can also cover health insurance copays and deductibles, which is where the coverage earns its keep for many families.
MedPay is sold in small increments, often $1,000, $2,500, $5,000, or $10,000 per person per accident. The cost is usually modest, sometimes just a few dollars a month for a few thousand dollars of protection. It follows the person, not just the car, in many policies, so it can cover you as a pedestrian or bicyclist struck by a vehicle. It also covers passengers in your car, including friends and family members who may not have their own health insurance. That combination of low cost and broad applicability is why many agents recommend it even when a driver already carries a health plan.
One important limitation: MedPay does not cover pain and suffering, lost wages, or property damage. It is strictly a medical expense benefit. It also has a per-person limit and a total per-accident limit, so a large family with multiple injured passengers could exhaust the coverage quickly. And it generally does not pay for injuries sustained in a collision while you are driving for work in a commercial capacity, depending on the policy language. Understanding these boundaries helps you decide how much MedPay, if any, makes sense for your household.
How MedPay Differs From Health Insurance
Health insurance and MedPay both pay medical bills, but they operate on completely different rules. Your health plan is designed to manage long-term health, often with networks, prior authorization requirements, deductibles, and copays. MedPay is a short-term, accident-specific benefit with no network restrictions and no deductible. When you use MedPay, you can see any licensed provider, and the insurer typically pays the bill up to your limit without haggling over in-network status. That flexibility matters in an emergency when the nearest hospital may be out of network.
Another key difference is speed. Health insurers may take weeks to process claims and may initially deny coverage if the injury is related to an auto accident, pending coordination of benefits. MedPay claims are usually processed quickly because the coverage is designed for exactly this scenario. Many auto insurers can pay medical providers directly, which means you may not have to front the money and wait for reimbursement. For a family with a high-deductible health plan, MedPay can act as a first-dollar layer that absorbs the initial costs of an accident before the health plan kicks in.
There is also the question of fault. Health insurance pays for your care no matter who caused the crash, but it may later seek reimbursement from a liability settlement through subrogation. MedPay pays regardless of fault and generally does not need to be repaid from a liability settlement in the same way, though rules vary by state and policy. That distinction can simplify your financial recovery after an accident. If you are comparing coverage options, understanding how each layer responds to a claim helps you avoid surprise bills and delays.
MedPay vs. PIP: What Is the Difference?
If you live in a no-fault state, you may already have personal injury protection, or PIP. PIP and MedPay sound similar, and both pay medical bills regardless of fault, but PIP is usually broader. In states like Florida, New York, and Michigan, PIP is required or heavily regulated and may cover lost wages, rehabilitation, and essential services such as childcare or housekeeping while you recover. MedPay is typically narrower and focuses on medical expenses only. In no-fault states, MedPay may be redundant if your PIP limit is high, or it may serve as a supplement if PIP limits are low.
In traditional fault states, PIP is not available, so MedPay is the main no-fault medical benefit on an auto policy. That makes the decision simpler: if you do not have PIP, MedPay is the only auto coverage that pays your medical bills immediately without a fault determination. Some drivers in fault states mistakenly believe their health insurance makes MedPay unnecessary, but health plans often come with deductibles and copays that MedPay can cover. The two coverages can work together rather than compete.
State rules matter a great deal here. A driver in Texas, for example, is not required to carry PIP or MedPay, but both may be offered. A driver in Florida must carry PIP, and MedPay may be optional or unavailable depending on the insurer. Before you decide, check your state's insurance department website or ask a licensed agent to explain how MedPay and PIP interact in your state. The answer can change the math on whether MedPay is worth the premium.
Do You Need MedPay If You Have Health Insurance?
The honest answer is: sometimes yes, sometimes no. MedPay is not legally required in most states, and it is not a substitute for health insurance. But it can fill gaps that health plans leave open. If your health insurance has a high deductible, significant copays, or a narrow network, MedPay can cover those out-of-pocket costs after a crash. If you regularly carry passengers who may not have health insurance, MedPay protects them too. And if you want the freedom to see any provider without network restrictions, MedPay offers that flexibility.
On the other hand, if you have robust health coverage with a low deductible, no network restrictions, and generous out-of-pocket maximums, MedPay may be less critical. Some health plans coordinate benefits with auto insurance and may require you to use MedPay first, which can actually simplify the claims process. But if your health plan is comprehensive and you have savings to cover copays, you might reasonably decide to skip MedPay and put the premium savings elsewhere. The decision is personal and depends on your financial cushion and risk tolerance.
Consider your passengers as well. Your health insurance covers you, but it does not automatically cover friends, extended family, or rideshare passengers in your vehicle. MedPay covers passengers in your car, which is a meaningful benefit for parents driving kids and their friends, or for anyone who regularly carpool. For a low monthly cost, MedPay can prevent an awkward situation where an injured passenger's bills become your responsibility. That alone is why many drivers add it even when they have good health coverage.
Here is a simple framework to decide:
- High-deductible health plan: MedPay is often worth it because it can cover the deductible and copays after an accident.
- Low-deductible, broad-network health plan: MedPay is optional, but still useful for passengers and out-of-network emergencies.
- No health insurance: MedPay is a valuable safety net, though it has limits and should not replace health coverage.
- No-fault state with high PIP: MedPay may be redundant; check your PIP limit before adding it.
- Fault state with no PIP: MedPay is the main no-fault medical benefit and worth considering.
After you weigh those factors, look at the actual premium. MedPay is usually inexpensive, so the cost of saying yes is often small compared to the potential out-of-pocket exposure. A $5,000 MedPay limit might cost less than a streaming subscription each month. For many households, that is a reasonable trade for peace of mind.
How MedPay Works With Health Insurance in a Claim
When you are injured in a crash, you generally have two paths: file with your health insurer or file with your auto insurer under MedPay. Many policies require you to notify your auto insurer promptly, and some health plans require you to disclose that the injury was auto-related. Coordination of benefits rules determine which insurer pays first. In some cases, MedPay pays first up to its limit, and your health plan covers the remainder. In other cases, your health plan pays first and MedPay reimburses you for copays and deductibles. The order depends on your policy language and state law.
To keep the process smooth, follow a few practical steps. First, report the accident to both insurers as soon as possible. Second, keep copies of all medical bills and explanations of benefits. Third, ask your auto insurer whether they can pay providers directly, which reduces your upfront costs. Fourth, track your MedPay limit so you know when it is exhausted. If you are also pursuing a liability claim against the at-fault driver, tell your attorney or adjuster about MedPay so the settlement is calculated correctly. Clear communication prevents double-billing and delays.
One common misconception is that using MedPay will raise your rates. In most states, medical payments coverage is a no-fault benefit, and using it does not count as an at-fault accident. That said, your overall claims history can influence future premiums, so it is worth asking your insurer how a MedPay claim is recorded. Generally, MedPay claims are treated more like health claims than like liability claims, which is good news for your record.
How Much MedPay Should You Carry?
MedPay limits are usually sold in increments, and the right amount depends on your health plan and savings. A $1,000 limit is better than nothing but can be exhausted by a single emergency room visit. A $5,000 limit covers many common accident scenarios, including ambulance rides, imaging, and follow-up care. A $10,000 limit offers more cushion for serious injuries but costs more. For families with children or frequent passengers, a higher limit may be prudent. For a single driver with excellent health coverage, a smaller limit may suffice.
When you request auto insurance quotes, ask specifically about MedPay limits and pricing. A licensed agent can show you the premium difference between $1,000 and $10,000, and you may be surprised how small the gap is. If you are shopping for coverage, platforms like Free Auto Insurance Quotes Online let you compare quotes from multiple carriers at once, and you can specify that you want MedPay included. That makes it easy to see how much the coverage adds to your total premium and whether it fits your budget.
It also helps to review your health insurance summary of benefits before you decide. Look at your deductible, copays, out-of-pocket maximum, and network rules. If your deductible is $3,000 and your copay for an emergency room visit is $500, a $5,000 MedPay limit could cover most of your accident-related costs. If your deductible is $500 and your plan pays 90 percent after that, MedPay is less critical for you but still valuable for passengers. Matching MedPay to your actual health plan gaps is the smartest way to choose a limit.
Common Situations Where MedPay Earns Its Keep
MedPay shines in scenarios that health insurance handles slowly or incompletely. Imagine a rear-end collision where you are not at fault. The other driver's liability insurance may eventually pay, but that can take months. MedPay pays your medical bills now, so you are not waiting for a settlement to see a doctor. Or imagine a passenger in your car who has no health insurance. Your MedPay covers their care up to the limit, which protects both of you from financial strain. These are real situations that happen every day, and they are why MedPay remains a popular add-on.
Another scenario: you are hit by an uninsured driver. Your uninsured motorist coverage may handle pain and suffering and larger damages, but MedPay can handle the immediate medical bills without a fault investigation. Or you are injured as a pedestrian in a crosswalk. Many MedPay policies follow you as a pedestrian, so your auto policy can respond even though you were not in your car. These edge cases are where a small premium delivers outsized value.
MedPay can also cover funeral expenses if a crash results in a death, up to the policy limit. That is a grim but important benefit for families. And because MedPay has no network restrictions, it can cover treatment from specialists, chiropractors, or urgent care centers that might be out of network under a health plan. For drivers who value choice and speed, MedPay is a practical layer of protection.
How to Add MedPay and Compare Quotes
Adding MedPay is straightforward. When you request a quote, tell the agent you want medical payments coverage and specify a limit. If you already have a policy, you can usually add MedPay with a quick call or online change. Ask whether the policy covers passengers, pedestrians, and family members, and confirm the per-person and per-accident limits. Also ask whether MedPay pays providers directly or reimburses you, and whether it coordinates with your health insurance. These details determine how useful the coverage will be in practice.
Comparison shopping is the best way to find affordable MedPay. Rates vary by carrier, and bundling MedPay with other coverage can lower the cost. If you are also financing a vehicle, you may be reviewing your auto loan terms at the same time; resources like CarLoanRefinancing explain how to compare refinancing options, which can free up room in your budget for better insurance coverage. And if you want to see how a specific carrier structures its policies, a deep dive into Geico auto insurance coverage and value can help you understand how MedPay fits into a larger policy.
When you are ready, gather your current policy declarations page, your health insurance summary of benefits, and a list of drivers and passengers in your household. Then request quotes from multiple carriers with MedPay included at a few different limits. Compare the total premium, not just the MedPay line item, because discounts and bundling can change the math. A few minutes of comparison can save you money and give you confidence that your coverage matches your actual risk.
Final Thoughts on MedPay and Health Insurance
Medical payments coverage is not a replacement for health insurance, and health insurance is not a replacement for MedPay. They serve different purposes and work best together. MedPay provides fast, no-fault, no-deductible payments for accident-related medical bills, including copays and passengers' care. Health insurance provides broad, long-term medical coverage. If you have a high-deductible plan, carry passengers, or want flexibility in where you receive care, MedPay is worth discussing with your agent. If your health plan is comprehensive and you have savings for copays, you may reasonably choose a smaller limit or skip it. Either way, make the decision with clear information, and ask about MedPay limits the next time you request auto insurance quotes.