Named Non Owner Car Insurance: Who Needs It in 2026
Named non owner car insurance who needs it: drivers without a car who borrow or rent vehicles. Call 8332757533 to compare coverage options today.
By Althea Monroe
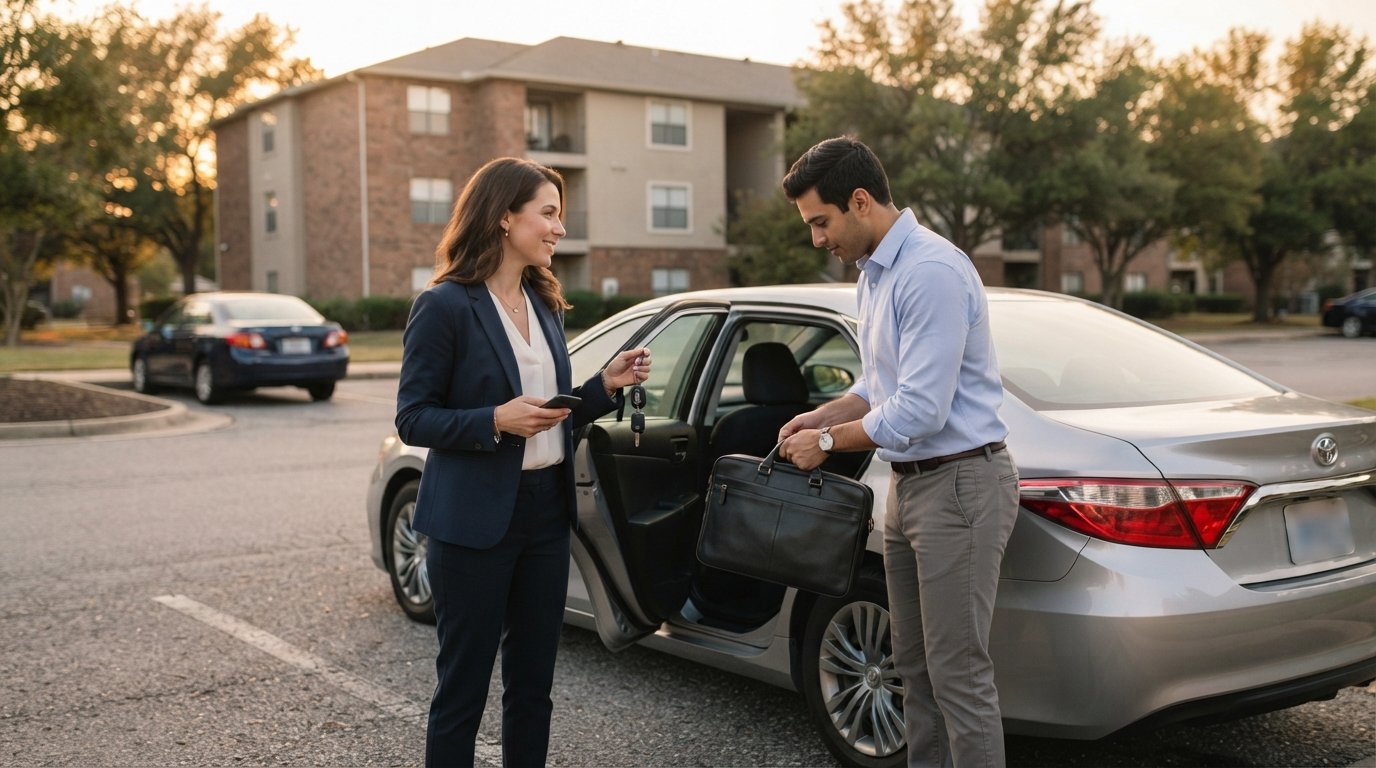
You do not own a car, yet you still need auto insurance. That sounds like a contradiction until you look at how often drivers without their own vehicle get behind the wheel. Maybe you borrow your sister's SUV for weekend errands, rent a car on business trips, or drive a company vehicle during the workweek. In each of those situations, you face real financial exposure, and the owner's policy may not fully protect you. Named non owner car insurance exists for exactly this gap, and understanding who needs it can save you from a surprise bill that runs into the tens of thousands of dollars.
What Named Non Owner Car Insurance Actually Covers
A named non owner policy is a liability-focused auto insurance product for people who do not own a registered vehicle but frequently drive cars they do not own. The word "named" matters: you are listed by name on the policy, which distinguishes it from the coverage that already follows the vehicle you are borrowing. When you drive someone else's car, their insurance is generally primary, meaning it pays first. Your named non owner policy then acts as a secondary layer that can pick up costs the owner's coverage does not handle, such as a liability limit that is too low for a serious accident.
The typical named non owner policy includes bodily injury liability, property damage liability, and often uninsured or underinsured motorist protection. Some insurers add personal injury protection or medical payments coverage depending on the state. What it generally does not include is collision or comprehensive coverage, because there is no specific vehicle to repair. That distinction trips up many shoppers, so keep it in mind: this product protects people and other property, not the borrowed car itself.
Pricing tends to be lower than a standard auto policy because the risk profile is narrower. You are not insuring a vehicle around the clock, so you are not paying for physical damage coverage or the full exposure of a dedicated car. Many drivers find quotes in the range of a few hundred dollars per year, though rates vary widely by state, driving record, and credit history. If you want to see how those numbers stack up against a traditional policy, it helps to compare quotes from multiple carriers before you commit.
How Named Non Owner Coverage Differs From Other Policies
Drivers often confuse named non owner insurance with non owner insurance, rental car coverage, or the liability protection that automatically extends from a household policy. The differences matter because buying the wrong product leaves you underinsured without realizing it.
Here is a quick breakdown of the most common options and how they compare:
- Named non owner policy: You are specifically listed, and coverage follows you when you drive borrowed or rented vehicles. It is the strongest option for frequent drivers without a car.
- Non owner policy (unnamed): Similar concept but less common, and coverage is tied to the policyholder without naming specific additional drivers.
- Rental car insurance from the rental company: Covers a specific rental period and often includes physical damage, but it does nothing for you the rest of the year.
- Coverage extended from a household policy: If you live with a relative who owns a car, their policy may extend to you, but limits and rules vary by state and insurer.
- Personal umbrella policy: Adds liability protection above existing auto limits, but it usually requires an underlying auto policy first.
That last point about household extension deserves emphasis. Many people assume they are covered under a spouse's or parent's policy simply because they live at the same address. Sometimes that is true, but insurers can exclude household members who are not listed drivers, and the extended coverage may only apply in limited situations. A named non owner policy removes that uncertainty by putting your name directly on a contract.
Who Needs Named Non Owner Car Insurance?
The clearest candidates are people who drive regularly without owning a vehicle. Frequency is the key factor. If you borrow a car once a year for a quick trip to the airport, the owner's policy is probably enough. If you are behind the wheel of someone else's car several times a month, you are carrying meaningful risk that a named non owner policy can address.
Beyond frequency, specific life situations create a strong case for this coverage. Consider the following profiles:
- City residents who rely on transit but borrow cars occasionally. You might not own a vehicle, but you still drive a friend's car for weekend trips or a family member's truck to move furniture. Liability exposure does not disappear just because you do not have a car payment.
- Frequent business travelers who rent cars. Rental companies sell damage waivers, but those waivers do not cover liability for injuries you cause to others. A named non owner policy can fill that gap and may make the rental counter upsell unnecessary.
- Drivers between cars after a sale, lease end, or total loss. If you sold your car and are saving for the next one, you may still drive borrowed vehicles. A short-term named non owner policy keeps you covered during the transition.
- People with a suspended or revoked license working toward reinstatement. Some states require proof of financial responsibility, and a named non owner policy can satisfy that requirement when you do not own a vehicle.
- Seniors who gave up their own car but still drive occasionally. Handing over the keys to your own vehicle does not mean you will never drive again. Family members may ask you to run errands in their car, and liability protection is still prudent.
There is also a group of drivers who need named non owner coverage for legal reasons rather than lifestyle reasons. If you were involved in an at-fault accident, caused damage while driving uninsured, or accumulated violations, a state may require you to file an SR-22 or similar proof of financial responsibility. When you do not own a car, a named non owner policy is often the only way to comply. In that scenario, the policy is not optional; it is a condition of keeping your driving privileges.
When a Named Non Owner Policy Is Not the Right Fit
This coverage is not for everyone, and buying it unnecessarily wastes money. If you own even one registered vehicle, you should insure that vehicle with a standard auto policy instead. The named non owner product is designed for people with no owned vehicle, and insurers will generally decline an application if you have a car registered in your name.
You also may not need it if you drive only rarely and always with permission in a state where the owner's policy extends broad coverage to permissive drivers. That said, relying on someone else's coverage is a gamble. The owner's limits might be state minimums, which are often far too low to cover a serious injury claim. If you cause an accident with $500,000 in damages and the owner carries $25,000 in liability, you could be personally responsible for the difference. A named non owner policy with higher limits protects your assets in that scenario.
Another consideration is cost versus benefit. If you genuinely drive a borrowed car two or three times a year and have few assets to protect, the premium may not justify the coverage. But if you have savings, a home, or a steady income that a judgment could reach, the math usually favors buying the policy. Think of it as cheap protection against a catastrophic outcome rather than a routine expense.
How to Shop for Named Non Owner Coverage
Not every insurer offers named non owner policies, and those that do may use different names for the product. You may see it called a non owner policy, an operator's policy, or a named operator policy. The terminology varies, but the concept is consistent: liability coverage for a driver who does not own a vehicle.
Start by gathering quotes from several carriers, because pricing for this niche product swings dramatically. A driver with a clean record in a low-cost state might pay under $300 per year, while a high-risk driver in a densely populated city could pay several times that amount. Your credit-based insurance score, driving history, and the liability limits you choose all influence the final number. For a broader look at how coverage rules shift depending on the vehicle you drive, including borrowed and rented cars, the guide on rental car insurance coverage updates is a useful companion read.
When you request quotes, be ready to explain your situation clearly. Tell the agent that you do not own a vehicle, describe how often you drive borrowed cars, and ask specifically about named non owner policies. If the first agent does not recognize the term, ask for an operator's policy or a non owner liability policy. Persistence pays off here, because the product is common enough that most major carriers have a version of it, even if frontline agents do not always use the same label.
Finally, verify the limits before you buy. State minimum liability limits are rarely enough to protect you in a serious accident. Choosing higher limits costs relatively little on a named non owner policy and can make the difference between a claim that is fully covered and a personal financial crisis. For independent educational resources on coverage options and rate comparisons, drivers often turn to NewAutoInsurance.com to supplement what they learn from their agent.
Steps to Get Covered Without Overpaying
Once you have decided that a named non owner policy makes sense, the process is straightforward. The key is to treat it like any other insurance purchase: compare, verify, and review.
- Confirm you are eligible. You must not own a registered vehicle, and you should be able to describe your driving habits honestly. Some insurers ask whether you have regular access to a specific car.
- Collect at least three quotes. Use the same liability limits and deductible assumptions across all quotes so the comparison is apples to apples.
- Ask about uninsured motorist coverage. This add-on protects you if a hit-and-run or uninsured driver injures you, and it is often worth the small extra premium.
- Review the exclusions. Some policies exclude coverage for vehicles available for your regular use, such as a company car assigned to you. Know what is not covered before you sign.
- Revisit the policy annually. If you buy a car, your needs change and you should switch to a standard auto policy. If your driving frequency increases, consider raising your limits.
One more practical tip: keep proof of insurance in your wallet or phone. If you are pulled over while driving a borrowed car, you may need to show that you carry your own liability coverage. Officers and claims adjusters will sort out which policy pays first, but having documentation speeds up the process and prevents confusion at the scene.
Common Mistakes That Leave Drivers Exposed
The biggest mistake is assuming that permissive use rules cover everything. In many states, insurance follows the car, not the driver, which means the owner's policy pays first after an accident. That sounds reassuring until you learn that the owner's limits may be low and that some policies exclude drivers who are not listed. If you borrow a car regularly, you can be classified as a regular user, and the insurer may deny a claim because you were never added to the policy.
A second mistake is buying the cheapest possible limits to satisfy a legal requirement. If you are getting a named non owner policy to file an SR-22 after a violation, the state minimum may technically satisfy the law, but it will not protect your finances if you cause a serious crash. Buying higher limits on a non owner policy is usually inexpensive relative to the added protection.
A third mistake is letting a lapse in coverage go unnoticed. Named non owner policies are still auto insurance, and a gap in coverage can trigger higher rates, fines, or license suspension in states that monitor continuous coverage. Set up automatic payments or calendar reminders so the policy stays active as long as you need it.
Drivers who understand these pitfalls are far better positioned to make a smart purchase. The product is not complicated once you separate liability coverage from physical damage coverage, and it is not expensive when you compare it against the potential cost of an at-fault accident. If you drive cars you do not own, take a few minutes to check whether a named non owner policy belongs in your financial plan, then request quotes and let the numbers guide your decision.