No Fault vs At Fault States: How Location Affects Car Insurance
Understand no fault vs at fault states and how location affects car insurance. Call 8332757533 to compare quotes and avoid surprise bills.
By Jacob Martinez
Your car insurance rate is not just about how you drive. It is also about where you live. Two drivers with identical records, vehicles, and credit scores can pay wildly different premiums simply because one lives in a no fault state and the other lives in an at fault state. That geographic difference determines who pays after a crash, how quickly claims resolve, and how much you shell out every month. Understanding the no fault vs at fault states how location affects car insurance is one of the most practical pieces of knowledge you can have as a driver, because it directly influences your legal rights and your wallet.
What No Fault and At Fault Actually Mean
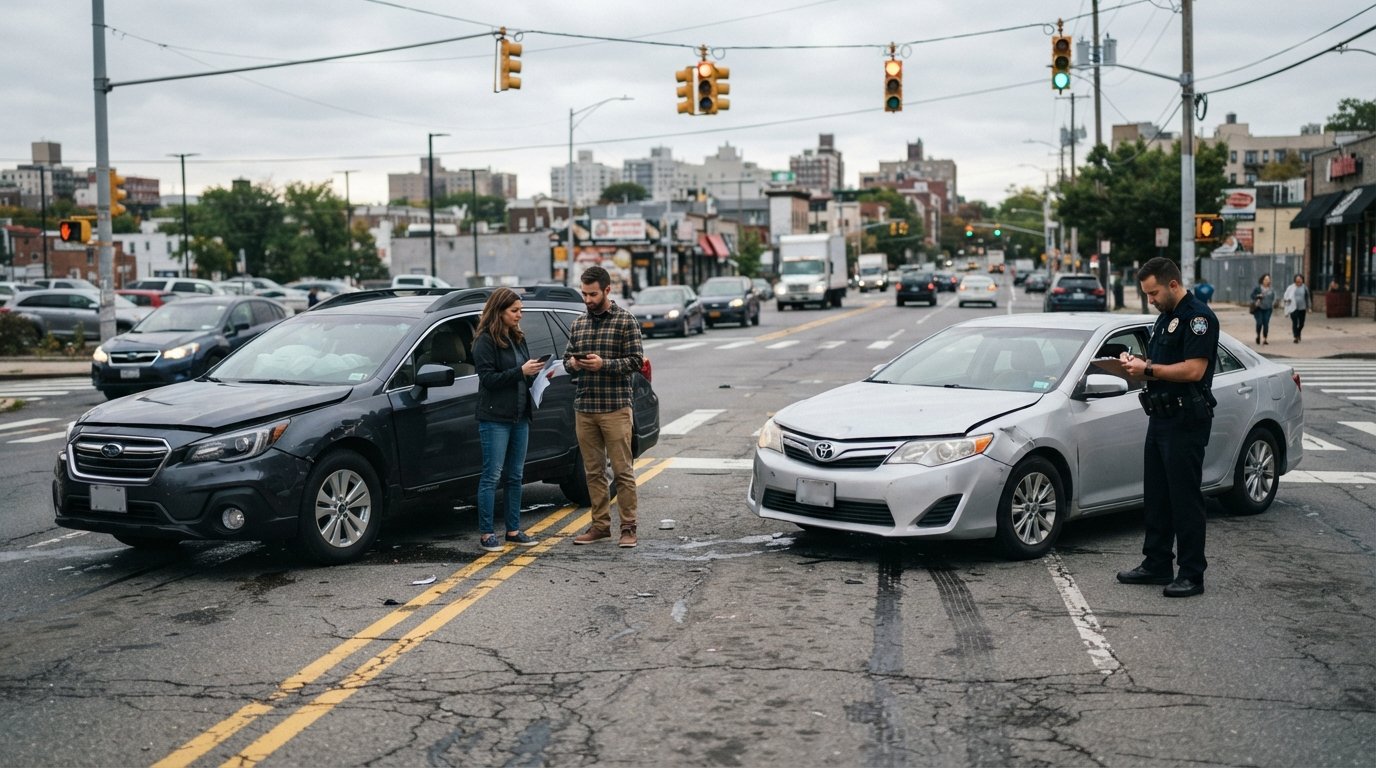
At its core, the distinction comes down to one question: after an accident, whose insurance pays for whose injuries? In an at fault state, the driver who caused the crash is financially responsible. The injured party can file a claim against the at fault driver's liability coverage, and in serious cases, they can sue for additional damages like pain and suffering. In a no fault state, each driver's own insurance pays for their own medical bills and related expenses, regardless of who caused the accident. The tradeoff is that your right to sue is restricted in most cases.
This is not a minor technicality. It changes the entire claims process. In an at fault state, you may wait weeks or months while insurers investigate fault. In a no fault state, your own Personal Injury Protection (PIP) coverage kicks in quickly, often paying medical bills and lost wages without a lengthy fault dispute. That speed and certainty come at a cost: no fault states typically require higher minimum coverage levels, which raises premiums for everyone.
The system also varies by degree. Some states are pure no fault, meaning you cannot sue except in extreme circumstances. Others use a hybrid or choice no fault system, where drivers can choose between no fault and traditional tort liability coverage. Meanwhile, at fault states operate under traditional tort law, where fault determination drives everything from claim payouts to rate increases.
The 12 No Fault States and Their Rules
As of 2026, 12 states plus Puerto Rico use some form of no fault auto insurance. These are Florida, Hawaii, Kansas, Kentucky, Massachusetts, Michigan, Minnesota, New Jersey, New York, North Dakota, Pennsylvania, and Utah. Each has its own quirks, but they share the core principle that your own insurer pays your medical bills first. Here is a quick look at how some of the most populous no fault states operate:
- Florida: Requires $10,000 in PIP and $10,000 in Property Damage Liability (PDL). Florida is a pure no fault state for injuries, but you can still be sued for non-economic damages if the injury meets a threshold.
- New York: Requires $50,000 minimum for no fault PIP coverage, plus liability limits. Lawsuits are allowed only for serious injuries as defined by law.
- Michigan: Historically offered unlimited PIP coverage, but recent reforms allow drivers to choose lower limits. Michigan also has unique rules for out of state drivers.
- Pennsylvania: A choice no fault state, meaning drivers can select full tort or limited tort. Limited tort saves money but restricts your right to sue for pain and suffering.
These rules matter because they determine how quickly you get paid and how much control you have over your claim. In a no fault state, your own insurance company is the first payer, so you deal with them directly. That can be faster, but it also means your rates may rise even if you did not cause the accident, depending on the state's rules on rate increases after not at fault claims.
For drivers in these states, comparing quotes is essential because PIP coverage can be expensive. If you want to see how your state's rules affect your premium, you can use an independent comparison platform like NewAutoInsurance to gather quotes from multiple carriers and spot the savings.
At Fault States: The Traditional Approach
The majority of U.S. states use the at fault system. In these states, the driver who causes the accident is responsible for the damages. If you are hit by another driver, you file a claim with their insurance company. If they are uninsured or underinsured, you may need to rely on your own Uninsured/Underinsured Motorist (UM/UIM) coverage. Fault is determined by police reports, witness statements, and state laws, which can follow pure comparative negligence or modified comparative negligence rules.
In pure comparative negligence states like California, you can recover damages even if you are 99 percent at fault, though your payout is reduced by your percentage of fault. In modified comparative negligence states, you can only recover if you are less than 50 or 51 percent at fault, depending on the state. This fault determination directly affects how much you receive and how much your insurance pays.
At fault states often have lower minimum coverage requirements than no fault states, which can mean lower premiums. However, they also expose you to lawsuits if you cause a serious accident. That is why many drivers in at fault states choose to buy higher liability limits than the minimum. The tradeoff is clear: you might pay less upfront, but you carry more financial risk if you are found at fault.
How Location Changes Your Premiums
Location affects your car insurance premium in several ways. First, no fault states require PIP coverage, which is often more expensive than traditional liability coverage. Second, no fault states tend to have higher rates of fraudulent claims and litigation, which insurers pass on to customers. Third, the density of drivers, traffic congestion, and accident rates in your city or ZIP code also play a role, regardless of the state's fault system.
For example, a driver in Tampa, Florida (a no fault state) will likely pay more for the same coverage than a driver in a rural at fault state like Montana. But even within a state, rates can vary dramatically. Urban areas with high accident rates and theft rates have higher premiums than rural areas. That is why it is critical to compare quotes based on your specific location, not just your state's fault system.
Here is a quick breakdown of how fault systems influence what you pay:
- No fault states: Higher minimum coverage requirements, PIP premiums, and limited lawsuit rights. Rates tend to be higher on average.
- At fault states: Lower minimum requirements, but higher liability risk. Rates vary widely based on fault rules and local accident rates.
- Choice states: You can choose between no fault and at fault coverage, giving you control over cost and legal rights.
Understanding these differences helps you anticipate your premium and choose the right coverage. If you live in a no fault state, you cannot avoid PIP, but you can shop around for the best rate. If you live in an at fault state, you may want to increase your liability limits to protect your assets.
What This Means for Your Claim After a Crash
After an accident, your location determines your next steps. In a no fault state, you file a claim with your own insurance company for medical bills and lost wages, regardless of who caused the crash. You do not need to wait for the other driver's insurer to accept fault. That can mean faster payment for medical treatment and less stress. However, your own rates may increase if your state allows it, and you may have limited ability to sue for pain and suffering.
In an at fault state, you file a claim with the at fault driver's insurance company. If they deny fault or delay payment, you may need to use your own collision coverage or UM/UIM coverage to get your car repaired and medical bills paid. You can also sue the at fault driver for damages, but that takes time and legal fees. The process is more adversarial, but it also gives you more leverage to recover non-economic damages like emotional distress.
Your location also affects how fault is determined. Some states follow pure comparative negligence, others modified comparative negligence, and a few follow contributory negligence, which bars recovery if you are even 1 percent at fault. Knowing your state's rule helps you understand your rights and negotiate with insurers.
Steps to Protect Yourself Regardless of Your State
No matter where you live, you can take steps to protect your finances and your peace of mind. Start by understanding your state's minimum requirements and fault system. Then, consider buying more than the minimum, especially if you have assets to protect. Here is a practical framework to follow:
- Check your state's fault system. Know whether you live in a no fault or at fault state and what that means for claims.
- Review your coverage. Make sure you have adequate liability, PIP (if required), collision, comprehensive, and UM/UIM coverage.
- Compare quotes from multiple insurers. Rates for the same coverage can vary by hundreds of dollars per year. Use a comparison platform to see your options.
- Ask about discounts. Safe driver, multi-car, good student, and bundling discounts can lower your premium.
- Re-evaluate annually. Your rates and needs change over time, so shop around at least once a year.
Following these steps can help you avoid surprise bills and maximize your recovery after an accident. It also puts you in a stronger position to negotiate with insurers, because you know what coverage you have and what your state allows.
For a seamless way to compare quotes from multiple carriers, visit NewAutoInsurance.com, an independent resource that provides free quotes and educational guides. It is not an insurance carrier, but it connects you with licensed agents who can help you find the right policy for your location and driving profile.
Common Myths About No Fault and At Fault States
There are many misconceptions about how fault systems work. One common myth is that no fault means no one is ever at fault. In reality, fault is still determined for rate increases and lawsuits, but it does not determine who pays first. Another myth is that at fault states always have cheaper insurance. While minimum coverage may be cheaper, the risk of a lawsuit and higher liability limits can make overall costs comparable.
Another myth is that you cannot be sued in a no fault state. That is false. Most no fault states allow lawsuits for serious injuries or when the economic damages exceed a certain threshold. Similarly, in at fault states, you can still be compensated even if you share some fault, as long as you meet your state's negligence rule.
Understanding these nuances helps you make better decisions about your coverage. It also prevents you from being caught off guard after an accident. Always read your policy and ask your insurer how your state's fault system affects your claims.
How to Shop for Insurance in Your State
Shopping for car insurance is not just about finding the lowest price. It is about finding the right coverage for your state's fault system and your personal situation. Start by gathering quotes from at least three insurers. Provide accurate information about your driving record, vehicle, and location. Then, compare not just the premium but also the coverage limits, deductibles, and exclusions.
If you live in a no fault state, pay attention to PIP limits and whether you can choose a deductible. If you live in an at fault state, focus on liability limits and UM/UIM coverage. In both cases, consider adding collision and comprehensive coverage if your car is worth more than a few thousand dollars.
Using an online comparison tool can save you time and money. Platforms like NewAutoInsurance let you enter your information once and receive quotes from multiple carriers. That makes it easy to see how your location affects your rate and to find the best deal.
Finally, do not be afraid to ask questions. Insurance agents are there to help you understand your options. Whether you are a first-time driver, a senior, or someone with a high-risk history, there is a policy for you. The key is to be informed and proactive.
Your location plays a huge role in how your car insurance works, from who pays after a crash to how much you pay each month. By understanding the no fault vs at fault states how location affects car insurance, you can take control of your coverage and your costs. Whether you live in a no fault state like New York or an at fault state like Texas, the right knowledge and the right quote can make all the difference.