Roadside Assistance Add-On: Worth the Cost in 2026?
Is a roadside assistance add-on worth the cost? Compare the monthly premium against out-of-pocket tow bills and see who benefits most.
By Leo Fairmont
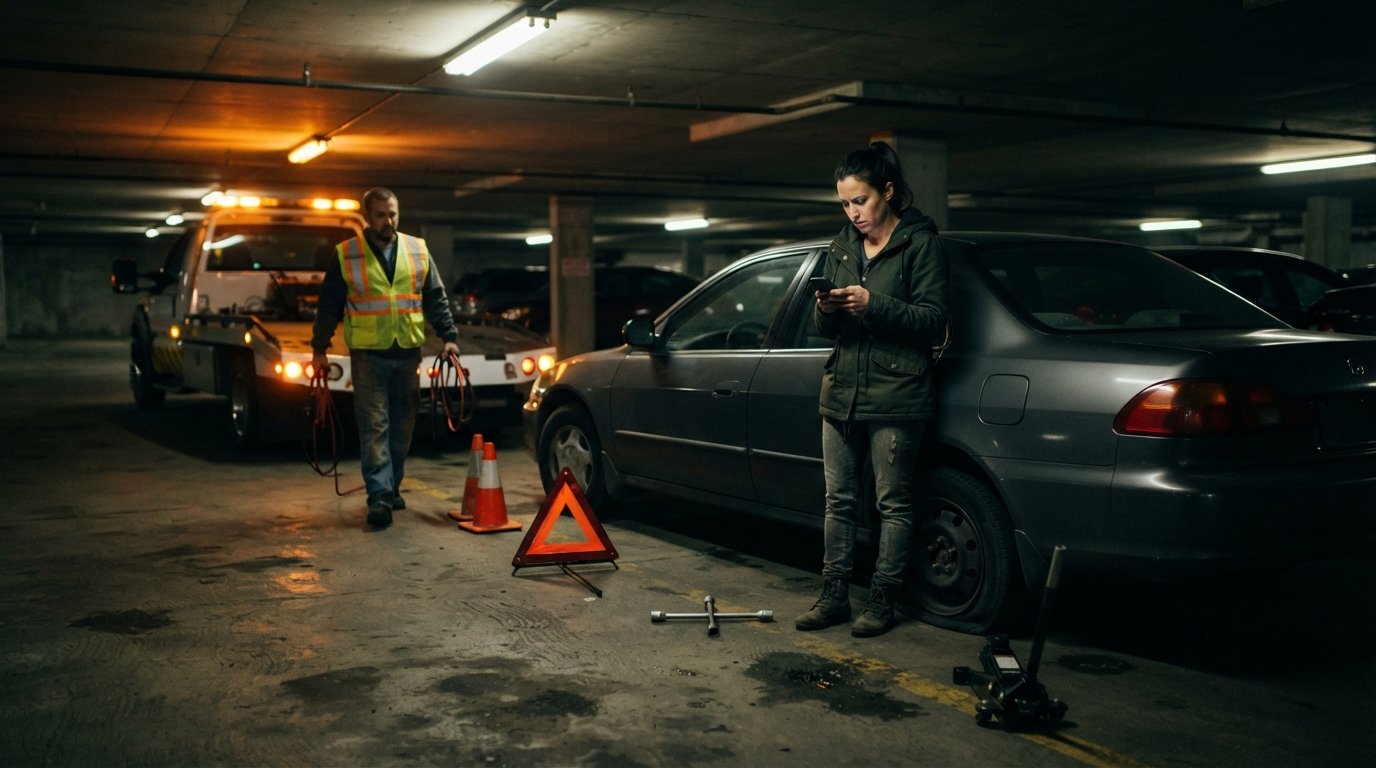
Your car dies in a parking garage on a Sunday night. You call a tow truck, and the driver quotes $180 just to hook up your vehicle. That moment, stranded and out of options, is when most drivers finally ask whether the roadside assistance add-on on their auto policy was worth the few dollars a month they skipped. The answer depends on how you drive, what you already pay for, and how much risk you are willing to absorb. This guide breaks down the real math behind roadside coverage so you can decide with confidence rather than regret.
What Roadside Assistance Add-Ons Actually Cover
Roadside assistance is rarely a standalone policy. It is usually a rider, an endorsement, or an add-on attached to your auto insurance or sold separately through a motor club. The core benefits look similar across providers, but the limits and exclusions vary enough that reading the fine print matters. Most add-ons reimburse or directly pay for towing, jump-starts, flat tire changes, fuel delivery, lockout service, and winching if you slide off the road. Some plans extend to trip interruption, which covers meals and lodging if a breakdown strands you far from home.
The typical cost ranges from $1 to $10 per month per vehicle when bundled with an auto policy, or roughly $40 to $120 per year. Standalone motor club memberships often run $60 to $150 annually and may include extra perks like travel discounts or map services. The gap between the cheapest and most expensive option is not huge, but the difference in what you get can be significant. A $1 monthly add-on might cap towing at five miles, while a $7 plan could tow you 100 miles to a shop you trust.
Here is what a standard roadside assistance add-on usually includes:
- Towing to a repair facility, with mileage limits that range from 5 to 100 miles
- Battery jump-starts or replacement assistance
- Flat tire changes using your spare
- Fuel, oil, or coolant delivery if you run out
- Lockout service to retrieve keys locked inside
Notice what is missing: coverage for parts, labor, or the actual repair. Roadside assistance gets you moving again, but it does not fix the alternator or replace the transmission. That distinction trips up many drivers who assume the add-on is a mechanical warranty. It is not. It is a convenience and emergency service, and its value comes down to how often you find yourself in situations where a tow or a jump is the only way forward.
The Real Cost of Paying Out of Pocket
If you decline the add-on, you are not avoiding the expense entirely. You are self-insuring. That means when your battery dies or your tire blows, you pay the market rate for a service call. Those rates have climbed steadily. A basic tow now averages $75 to $125 for the first few miles, with per-mile charges after that. A lockout can cost $50 to $100. A jump-start from a commercial service often runs $75 or more, especially after hours or in remote areas.
Run the numbers over a three-year period. If you call for help once every 18 months at an average of $120 per call, you spend about $240. A $5 monthly add-on costs $180 over the same period and covers unlimited or near-unlimited calls. That math favors the add-on for drivers who average even one breakdown every year or two. But if you have never used roadside service in a decade, you have likely paid more in premiums than you would have paid out of pocket, assuming nothing changes.
The calculation shifts when you factor in safety and stress. Being stranded on a highway shoulder at night is not just inconvenient; it is dangerous. A paid add-on removes the hesitation to call for help because you already know it is covered. That peace of mind has a value that is hard to quantify but real for older drivers, families with young children, and anyone who regularly travels through rural areas with spotty cell service.
When a Roadside Assistance Add-On Is Worth the Cost
Certain driver profiles get more value from roadside coverage than others. If you fit one or more of the categories below, the add-on is likely a smart purchase. If you fit none, you may be better off setting aside a small emergency fund instead.
The add-on tends to pay off for:
- Drivers with older vehicles that are more prone to battery, tire, and belt failures
- High-mileage commuters who spend hours on the road each week
- Families with multiple vehicles, where the odds of at least one breakdown rise
- Seniors who prefer not to change a tire on a busy road or in bad weather
- Anyone who frequently drives long distances through unfamiliar or remote areas
For these groups, the monthly cost is small relative to the potential out-of-pocket hit and the safety benefit. A single tow from a remote stretch of highway can exceed the annual premium for the add-on. When you also consider that many insurers offer the coverage for just a few dollars per vehicle per month, the barrier to entry is low. The key is to confirm the towing mileage limit and whether the plan covers the drivers in your household, not just the named insured.
On the other hand, the add-on may not be worth the cost if you already belong to a motor club, drive a new car under a manufacturer warranty that includes roadside assistance, or have a credit card that offers complimentary roadside service. In those cases, you would be paying twice for the same protection. Review your existing benefits before adding a duplicate. It is also worth checking whether your insurer raises premiums after a roadside claim; most do not, but a few treat it as a claim that can affect your rate.
How to Evaluate the Add-On Before You Buy
Not all roadside assistance add-ons are created equal. The price is only one factor. The fine print determines whether the coverage actually helps when you need it. Before you add the rider to your policy, ask a few pointed questions and compare the answers across at least two or three insurers. The differences can be surprising.
Start by confirming the towing distance. A five-mile limit may barely get you to the nearest exit, while a 100-mile limit gives you real choice about where your car is repaired. Next, check the service call limit. Some plans cover four or five calls per year; others are unlimited. Then look at the reimbursement model. Some insurers dispatch a provider directly, while others require you to pay upfront and file for reimbursement. The latter can be a problem if you do not have cash available at the moment of breakdown.
It also helps to understand how the add-on interacts with your other coverage. For example, if your car is disabled in an accident, your collision or comprehensive coverage may already pay for towing. In that case, the roadside add-on is most valuable for non-accident breakdowns like dead batteries and flat tires. Knowing which coverage responds to which event prevents you from paying for overlapping protection. If you are unsure how your policy handles towing after a collision, review your declarations page or ask your agent directly.
For a broader look at how roadside assistance fits into an auto policy, see this guide on auto insurance with roadside assistance. It explains how the add-on pairs with liability, collision, and comprehensive coverage, and when bundling makes sense.
Alternatives to the Insurance Add-On
If you decide the add-on is not worth the cost for your situation, you still have options. The most common alternative is a standalone motor club membership. These memberships often include the same core benefits (towing, jump-starts, lockouts, fuel delivery) and may add discounts on travel, hotels, and prescriptions. The trade-off is that you pay a separate bill and manage a separate renewal, but the coverage limits are sometimes higher than what insurers offer.
Another option is a credit card with roadside assistance as a built-in benefit. Many premium cards include towing and lockout service if you use the card to pay for the rental or purchase. The catch is that you must activate the benefit by paying with that card and following the card issuer's dispatch process. It is not automatic, and the limits are often lower than a dedicated plan. Still, for drivers who already carry such a card, it can be a free or low-cost layer of protection.
Finally, some new vehicles come with manufacturer roadside assistance for the first few years. This coverage is often generous, including towing to a dealership and trip interruption benefits. If your car is under warranty, check the terms before buying an add-on. You may already have coverage that makes the insurance rider redundant, at least until the warranty expires. Once it does, you can revisit the add-on with a clearer idea of your actual risk.
Making the Decision: A Simple Framework
To decide whether a roadside assistance add-on is worth the cost, run through a short framework. First, estimate how many times you have needed a tow, jump-start, or lockout in the past three years. Multiply that by the average out-of-pocket cost in your area. Second, compare that total to the annual premium of the add-on multiplied by three. Third, factor in your comfort level with risk and your access to alternative coverage through a motor club, credit card, or warranty.
If the out-of-pocket estimate is higher than the premium and you have no overlapping coverage, the add-on is likely worth it. If the estimate is lower and you have alternatives, you can safely decline. The decision is not permanent. You can add the coverage when your car ages or when you start a new commute, and drop it when your situation changes. The goal is to match the coverage to your actual driving life, not to buy it by default or skip it out of habit.
For drivers who want to compare quotes that include roadside assistance, an independent comparison platform can help. Resources like NewAutoInsurance provide educational content and comparisons that help vehicle owners understand coverage options and find potential savings. Pairing that research with a quote comparison from multiple carriers gives you the clearest picture of what you would pay and what you would get. With the numbers in front of you, the question of whether the roadside assistance add-on is worth the cost becomes much easier to answer.