RV Insurance: Full Time vs Part Time Use Explained
Compare RV insurance for full time versus part time use and protect your home on wheels. Call (833)-275-7533 for expert guidance today.
By Danica Frost
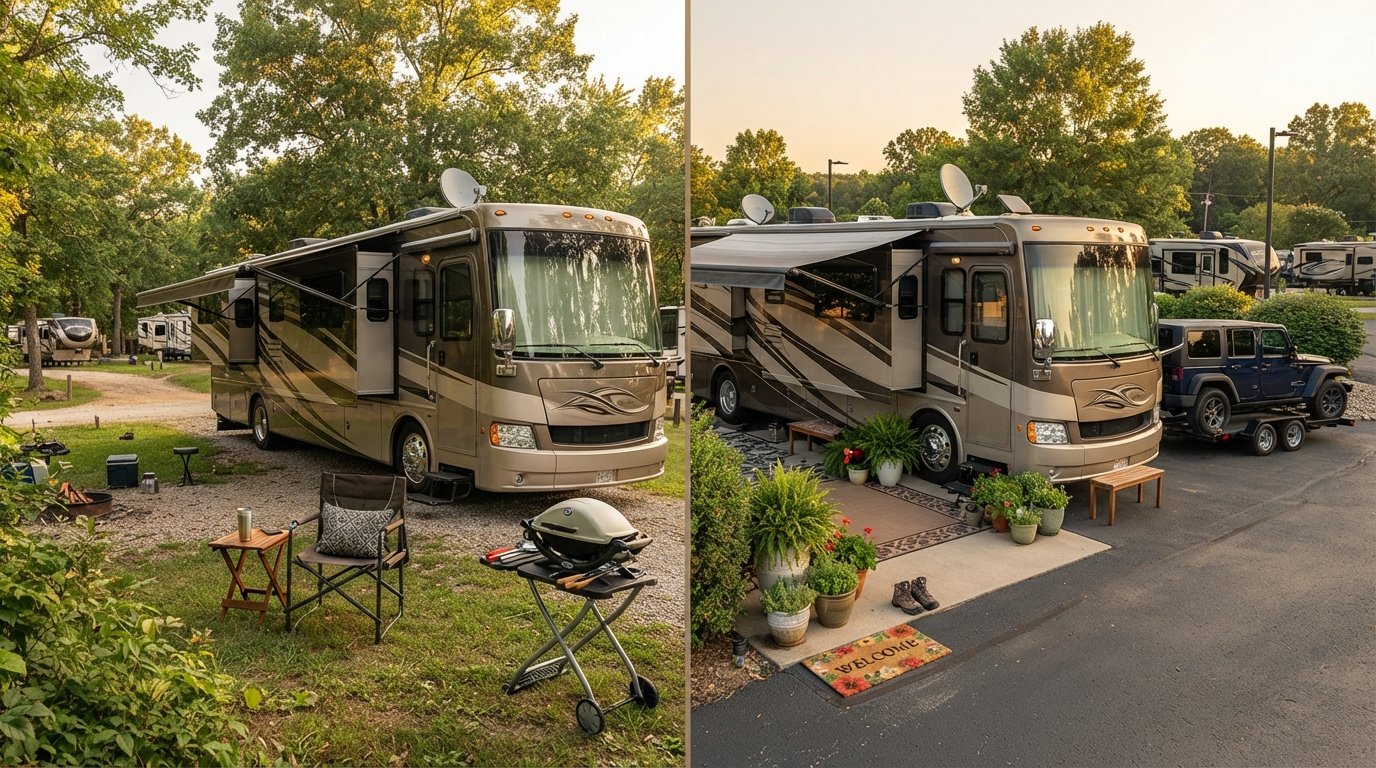
Your RV is more than a vehicle. For some owners it is a weekend escape, a tailgating headquarters, or a summer vacation machine. For others it is a primary residence, a mobile office, and a permanent address on wheels. That fundamental difference in how you use your rig is exactly what insurers use to decide how to rate, underwrite, and cover your policy. Understanding RV insurance full time versus part time use is not an academic exercise; it is the difference between a claim being paid in full and a claim being denied because your policy did not match your lifestyle. Whether you are parked at a seasonal campground or living in your coach year round, the coverage you need, the endorsements you should buy, and even the state where you register your vehicle all shift based on usage.
Most RV owners start with a standard auto-style policy, which assumes occasional recreational use. That works fine for a motorhome that sits in storage from November to March and logs 3,000 miles a year. But the moment you move into your RV full time, the risk profile changes completely. Your personal belongings are now concentrated in a vehicle that could be destroyed by fire or a storm. Your liability exposure grows because you are entertaining guests, hosting visitors, and living on a site rather than just parking there. And your state of domicile becomes a legal and insurance question, not just a mailing address. This guide walks through how insurers define full time versus part time use, what coverages differ, how full-timer endorsements work, why your tow vehicle needs separate attention, and how to compare specialized RV quotes before you commit.
How Insurers Define Full Time Versus Part Time RV Use
There is no single, universal definition of full-time RV use across the insurance industry, but most carriers converge on a few practical tests. The most common threshold is the number of days per year you live in the RV. Many insurers treat 150 to 180 days or more of annual occupancy as full-time use. Others ask whether the RV is your primary residence, meaning you have no other permanent dwelling that serves as your legal home. Some carriers simply ask if you live in the RV more than six months out of the year. The answers to these questions determine which policy form the insurer applies, and the premium difference can be substantial.
Part-time use generally means you use the RV for recreation, travel, or seasonal camping while maintaining a separate primary residence. You might take two-week trips, spend weekends at a lake, or snowbird for a few months in Arizona before returning to a house in Minnesota. Even if you spend 90 or 120 days in the RV, many carriers still classify that as part-time or seasonal use as long as you have a stick-and-brick home that serves as your primary residence and you do not claim the RV as your domicile. The key distinction is not just time; it is whether the RV functions as your home or as your hobby.
Insurers also look at how the RV is stored and where it is parked when not in use. A part-time RV is often stored at a residence or a storage lot, which lowers certain risks. A full-time RV is typically parked at campgrounds, RV resorts, or long-term sites, which introduces different liability exposures and sometimes higher theft or weather risk. Some carriers ask for the address where the RV is primarily garaged and whether that location is a campground, a mobile home park, or a private residence. These details feed into the rating algorithm and can affect whether you are placed in a preferred or non-standard tier.
Because definitions vary by carrier, the burden falls on you to be precise and honest during the quote process. If you tell an agent you are part-time when you actually live in the RV eight months a year, you may save money upfront but create a coverage gap that could void a claim. The better approach is to gather your actual usage data (nights per year, months in the RV, whether you have another home) and present it clearly. A licensed agent who specializes in RV policies can then match you with a carrier whose definition fits your reality. This is one area where using a comparison service to gather multiple quotes from carriers with different appetites is genuinely valuable.
Coverage Differences for Personal Liability and Contents While Parked
The biggest practical difference between full-time and part-time RV insurance shows up in liability and personal contents coverage. A standard part-time RV policy often includes liability coverage that mirrors an auto policy: it responds when you cause bodily injury or property damage while driving. But when a part-time RVer is parked at a campsite, the liability coverage may be limited or may not extend to incidents that occur off the road. For example, if a guest trips over your power cord and breaks an arm, a basic auto-style RV policy might not respond. That is a significant gap for someone who uses the RV as a residence and regularly hosts visitors.
Full-time RV policies are designed to fill that gap. They typically include personal liability coverage that applies both on the road and at the campsite, much like a homeowners or renters policy. This coverage can respond to bodily injury or property damage claims from third parties, whether the incident happens while you are driving, setting up camp, or simply living in the RV. Some full-timer policies also include medical payments to others, which can cover minor injuries to guests regardless of fault. For anyone who lives in their RV and entertains family or friends, this liability extension is not optional; it is essential protection.
Personal contents coverage is another major difference. A part-time RV policy may include a modest amount of coverage for personal property inside the RV, often capped at a few thousand dollars. That might be enough for a weekend camper with clothes, dishes, and a few electronics. But a full-timer has an entire household inside the coach: computers, tools, clothing, kitchenware, hobby equipment, and possibly work-related items. The replacement cost of those belongings can easily exceed $20,000 or more. Full-time RV policies typically offer higher personal contents limits and may allow you to schedule valuable items like jewelry, cameras, or musical instruments. Some policies also include replacement cost coverage for contents rather than actual cash value, which makes a meaningful difference when you need to rebuild your household after a loss.
There is also the question of loss of use and additional living expenses. If your full-time RV is damaged by a fire or a storm and becomes uninhabitable, you need a place to stay while it is repaired. Full-time policies often include loss of use coverage that pays for temporary lodging, meals, and other additional living expenses, similar to what a homeowners policy provides. Part-time policies may include a limited loss of use benefit, but it is usually calculated based on a short trip rather than months of displacement. For a full-timer, that difference can be financially devastating if a major repair takes weeks or months.
Finally, consider personal injury protection or medical payments coverage for yourself and your passengers. Part-time policies may include these coverages at modest limits, but full-timers often need higher limits because they spend more time on the road and may travel in remote areas where medical care is far away. Some full-timer policies also include coverage for emergency roadside assistance, which is valuable when your home itself is disabled on the side of a highway. When comparing quotes, look beyond the premium and examine the actual limits and endorsements each policy includes. The cheapest quote is rarely the best value if it leaves you underinsured for the risks you actually face.
Full-Timer Endorsements, Mail Forwarding, and Domicile Issues
Full-time RV living creates a unique set of legal and insurance challenges around domicile. Domicile is your permanent legal home, the place where you intend to return and where you are registered to vote, pay taxes, and hold a driver's license. Many full-timers sell their traditional homes and adopt a domicile state that is favorable for taxes and insurance, often Texas, Florida, or South Dakota. But insurers care about domicile because it determines which state's insurance regulations apply, which can affect policy forms, minimum coverage requirements, and even whether a carrier will write your policy at all. If you claim a domicile in one state but spend most of your time in another, you may create confusion that could complicate a claim.
Mail forwarding services are a common tool for full-timers, but they are not a substitute for a legal domicile. A mail forwarding address in South Dakota, for example, can help you establish residency if you also register your vehicles there, obtain a driver's license, and spend enough time in the state to satisfy its requirements. However, some insurers are wary of mail forwarding addresses because they can indicate a transient lifestyle or a mismatch between garaging location and domicile. When you apply for a full-time RV policy, be prepared to explain your domicile arrangement clearly and provide documentation such as a driver's license, voter registration, or a lease or property deed if applicable. Carriers that specialize in full-timer policies understand these arrangements and are more likely to underwrite them smoothly.
Full-timer endorsements are the policy add-ons that bridge the gap between a standard RV policy and a true full-time lifestyle. These endorsements vary by carrier, but common ones include:
- Personal liability extension: Adds liability coverage for incidents that occur while parked or living in the RV, beyond what the auto-style liability provides.
- Increased contents coverage: Raises the limit for personal belongings inside the RV and may include replacement cost rather than actual cash value.
- Loss of use or additional living expenses: Pays for temporary housing and related costs if the RV becomes uninhabitable after a covered loss.
- Full-timer personal injury protection: Provides medical payments or PIP coverage for you and your passengers at higher limits suited to full-time travel.
- Emergency expense coverage: Reimburses costs like lodging and meals if the RV breaks down far from home and requires extended repairs.
Not every carrier offers every endorsement, and some carriers bundle them into a dedicated full-timer policy form. When you request quotes, ask specifically whether the policy includes full-timer endorsements or whether they must be added separately. A policy that looks affordable at first glance may become expensive once you add the endorsements you actually need. Conversely, some carriers include robust full-timer features in their base policy, which can make them a better value even if the headline premium is slightly higher.
Domicile and mail forwarding also affect your tow vehicle and toad. If you flat-tow a car behind your motorhome, that car needs its own insurance policy in the state where it is registered, which is usually your domicile state. The tow vehicle's policy should include liability, collision, and comprehensive coverage, and you should confirm that it covers the car while it is being towed. Some auto policies exclude coverage while a vehicle is being towed by a motorhome, so you may need a special endorsement or a separate policy that explicitly covers the towing situation. This is a common gap that full-timers discover only after an accident, so address it during the quoting process.
Why the Tow Vehicle Needs Its Own Policy and How Coverage Interacts
Many full-timers travel with a secondary vehicle, often called a toad or dinghy, that is flat-towed behind a motorhome. It is a mistake to assume the motorhome policy covers the towed vehicle. In most cases, the motorhome policy covers the motorhome itself and may provide limited liability coverage while the towed vehicle is attached, but the towed vehicle needs its own policy for collision, comprehensive, and liability coverage when it is driven separately. If you drive the toad to the grocery store or to a trailhead, you need insurance on that vehicle just as you would on any other car.
The interaction between the two policies matters. Suppose you are driving the motorhome and cause an accident while towing the car. The motorhome policy's liability coverage typically responds first. But if you are driving the towed car separately and cause an accident, the car's policy responds. If the car is damaged while being towed, the car's comprehensive or collision coverage may respond, depending on the policy language. Some auto policies exclude damage that occurs while the vehicle is being towed, which is why you should read the exclusions carefully or ask your agent to confirm coverage. A specialized RV insurer may offer a combined policy that covers both the motorhome and the towed vehicle, which can simplify claims and eliminate gaps.
There is also the question of uninsured and underinsured motorist coverage. Full-timers spend a lot of time on highways and in unfamiliar areas, and the risk of encountering an uninsured driver is real. Your motorhome policy and your tow vehicle policy should both include UM/UIM coverage at limits that reflect your actual exposure. If you are injured by an uninsured driver while driving the toad, the toad's policy responds. If you are injured while driving the motorhome, the motorhome policy responds. Having adequate UM/UIM coverage on both policies protects you and your passengers regardless of which vehicle you are operating.
Another consideration is personal injury protection or medical payments coverage. In states that require PIP, your auto policy may include it automatically. In other states, you may need to add medical payments coverage. For full-timers, higher limits are often wise because medical costs can be significant and your health insurance may not cover injuries sustained in an auto accident. When comparing quotes, ask each carrier how their RV policy interacts with your tow vehicle policy and whether they offer any multi-policy discounts. Some carriers offer discounts for insuring both the motorhome and the toad, which can offset the cost of maintaining two policies.
Finally, consider the registration and inspection requirements for your tow vehicle. Some states require separate registration and insurance for towed vehicles, and others have specific rules about tow dollies and flat-towing. Your domicile state's DMV website is the authoritative source, but an insurance agent who writes policies in that state can often clarify the practical requirements. Keeping your tow vehicle properly registered and insured is not just a legal requirement; it is a critical part of protecting yourself financially on the road.
How to Compare Specialized RV Quotes Before Choosing
Comparing RV insurance quotes is not the same as comparing standard auto insurance quotes. The coverage forms, endorsements, and underwriting questions are different, and a policy that looks cheap may be missing the full-timer features you need. The best approach is to gather quotes from multiple carriers that specialize in RV coverage, including at least one or two that are known for full-timer policies. Start by preparing a detailed summary of your usage: how many nights per year you spend in the RV, whether you have another residence, your domicile state, the year, make, and model of your RV, and whether you tow a vehicle. Having this information ready makes the quoting process faster and more accurate.
When you receive quotes, compare them on more than just premium. Create a simple comparison sheet with columns for liability limits, personal contents coverage, loss of use coverage, full-timer endorsements, deductibles, and any exclusions that matter to you. Ask each agent or carrier representative to explain how their policy defines full-time use and what happens if your usage changes during the policy term. Some carriers allow you to adjust your policy mid-term if you transition from part-time to full-time, but others may require a new application. Knowing the rules upfront prevents surprises later.
Here is a practical framework for comparing specialized RV quotes:
- Confirm the usage classification: Ask each carrier to state in writing whether they are quoting you as full-time or part-time, and what definition they used.
- Compare liability and contents limits: Look at the actual dollar limits for personal liability and personal contents, not just whether coverage exists.
- Check for full-timer endorsements: Verify whether loss of use, increased contents, and campsite liability are included or optional, and at what cost.
- Review tow vehicle coverage: Confirm how the policy interacts with your towed vehicle and whether any discounts apply for insuring both.
- Read the exclusions: Pay attention to exclusions for full-time use, business use, or dwelling use, and ask how they apply to your situation.
After you have compared quotes, do not be afraid to ask follow-up questions. A reputable agent will welcome them. If a quote seems too good to be true, it probably is, especially if it lacks full-timer endorsements or has unusually low contents limits. The goal is not to find the absolute cheapest policy; it is to find the policy that matches your actual risk profile at a fair price. For full-timers, that usually means paying a bit more than a part-time policy but gaining liability, contents, and loss of use coverage that could save you tens of thousands of dollars in a worst-case scenario.
It also helps to understand the broader auto insurance landscape, even though RV policies are specialized. Many of the same principles apply: higher deductibles lower premiums, bundling policies can earn discounts, and maintaining a clean driving record matters. If you are also insuring a daily driver or a tow vehicle, you can learn more about general auto insurance requirements and options through resources like this independent auto insurance guide, which explains coverage types and comparison strategies for U.S. drivers. For Massachusetts residents or anyone curious about state-specific rules, a guide to auto insurance in Massachusetts can illustrate how state regulations shape policy requirements, which is useful context when you are navigating domicile decisions as a full-timer.
Finally, revisit your policy every year. Full-time RV living is dynamic; you may change domicile states, add or remove a tow vehicle, or adjust your travel patterns. An annual policy review ensures your coverage keeps pace with your lifestyle. If you transition from part-time to full-time, notify your insurer immediately rather than waiting for renewal. The cost of a mid-term adjustment is almost always less than the cost of a denied claim. With the right policy and a clear understanding of how full-time and part-time use differ, you can protect your home, your belongings, and your financial future while enjoying the freedom of the road.