SR 22 Filing in Texas: What Drivers Need to Know
Understand the SR 22 filing in Texas: what drivers need to know about triggers, limits, and duration. Call (833)-275-7533 for expert guidance.
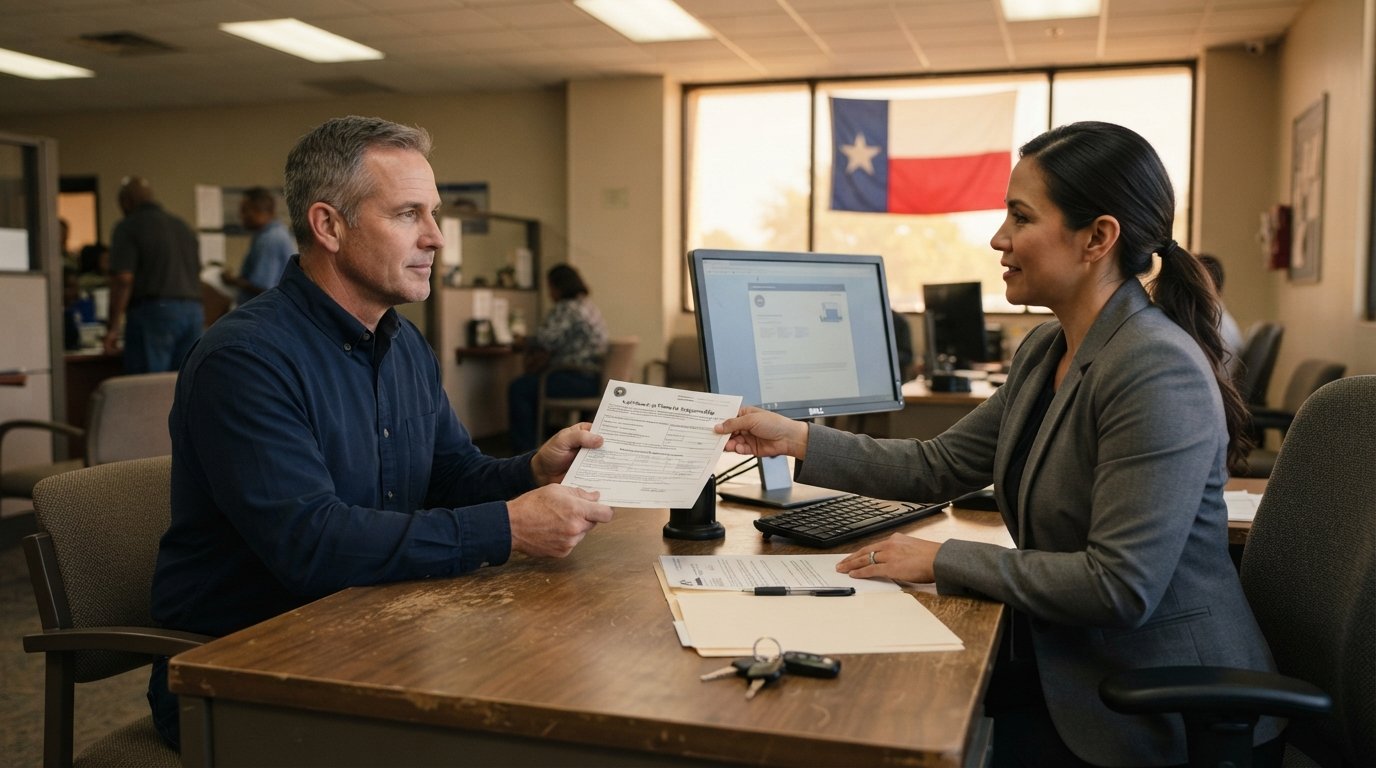
If you have been told that you must file an SR-22 in Texas, you probably have questions about what it means, how to get it done, and how long it will affect your driving record. An SR-22 is not a type of insurance policy; it is a certificate of financial responsibility that your auto insurer files with the Texas Department of Public Safety (DPS) on your behalf. It proves that you carry at least the state minimum liability coverage. The filing is typically required after certain driving offenses, such as a DWI or driving without insurance, and it remains in effect for a set period, usually two years. Understanding the process can help you avoid common pitfalls, keep your license valid, and eventually move on from the high-risk designation.
What Triggers an SR-22 Filing in Texas
Texas requires an SR-22 filing for several reasons, all tied to a driver's history of risky behavior or failure to maintain financial responsibility. The most common trigger is a conviction for driving while intoxicated (DWI). Even a first offense can lead to an SR-22 requirement, and the filing period may extend beyond the standard two years if there are aggravating factors. Another frequent cause is driving without insurance. If you are caught operating a vehicle without the required liability coverage, you may face fines, license suspension, and the need to file an SR-22 to reinstate your driving privileges.
Other offenses that can lead to an SR-22 include reckless driving, leaving the scene of an accident (hit-and-run), and accumulating too many points on your driving record within a certain timeframe. In some cases, an SR-22 is required after an at-fault accident where you were unable to show proof of insurance. The Texas DPS notifies you by mail when a filing is required, and you must act quickly to avoid further penalties.
It is important to note that an SR-22 is not a one-time document. It must be maintained continuously for the entire required period. If your policy lapses or is canceled, your insurer is obligated to notify the DPS, which can result in another license suspension and additional fees. This is why drivers with an SR-22 requirement need to prioritize keeping their coverage active at all times.
Texas Minimum Liability Limits and Proof of Financial Responsibility
Texas law requires drivers to carry a minimum amount of liability insurance to cover damages they may cause to others in an accident. As of 2026, the minimum liability limits are $30,000 for bodily injury per person, $60,000 for bodily injury per accident, and $25,000 for property damage per accident. These amounts are often written as 30/60/25. An SR-22 filing certifies that you have at least this coverage in place.
However, carrying the minimum limits may not be enough to protect your assets if you cause a serious accident. Many drivers with an SR-22 choose to purchase higher limits or add uninsured/underinsured motorist coverage for added protection. Your insurance agent can help you understand the options and find a policy that meets both the state requirements and your budget.
Proof of financial responsibility can also be demonstrated through other means, such as a surety bond or a deposit with the Texas Comptroller. However, the most common method is an SR-22 filing through an insurance company. The certificate itself is filed electronically by your insurer, so you do not need to handle paperwork with the DPS directly. You simply need to maintain your policy and ensure your insurer has the correct information.
How the SR-22 Filing Process Works
The SR-22 filing process begins when you contact an insurance company that writes policies for high-risk drivers. Not all insurers offer SR-22 filings, so you may need to shop around. When you apply for a policy, you must disclose that you need an SR-22. The insurer will then issue the policy and file the certificate with the Texas DPS electronically. This typically happens within a few business days, but you should confirm with your agent that the filing has been completed before you attempt to reinstate your license or registration.
Once the SR-22 is on file, you must keep your policy active for the entire required period. If you miss a payment or your policy is canceled for any reason, the insurer will notify the DPS, and your license may be suspended again. To avoid this, set up automatic payments or reminders, and communicate with your insurer if you anticipate any issues. If you need to switch insurance companies during the SR-22 period, make sure the new insurer files a new SR-22 before the old policy is canceled to avoid a gap in coverage.
After the required filing period ends, your insurer will notify the DPS that your obligation is complete. You should verify that the DPS has updated your record and that no further action is needed. In some cases, you may need to request a clearance letter from the DPS to confirm that your SR-22 requirement has been satisfied. Keeping copies of all correspondence and filings is a good practice.
Non-Owner SR-22 Options for Drivers Without a Vehicle
If you do not own a vehicle but still need to file an SR-22 to reinstate your license, you may be able to purchase a non-owner car insurance policy. This type of policy provides liability coverage when you drive a vehicle that you do not own, such as a rental car or a friend's car. It satisfies the SR-22 requirement without the need for a specific vehicle to be insured.
Non-owner policies are generally cheaper than standard auto insurance because they do not cover physical damage to a vehicle. However, they still fulfill the state's financial responsibility requirement. Not all insurers offer non-owner policies, so you may need to work with an agent who specializes in high-risk drivers. Keep in mind that if you later buy a vehicle, you will need to convert the non-owner policy to a standard auto policy and ensure the SR-22 remains in effect.
It is important to be honest with your insurer about your situation. If you purchase a non-owner policy but actually own a vehicle, your claim could be denied, and you could face legal consequences. A licensed agent can guide you through the options and help you choose the right coverage for your circumstances.
How Long Does an SR-22 Stay on Your Record in Texas?
In Texas, the SR-22 requirement typically lasts for two years from the date of the offense or the date you reinstate your license, whichever is later. However, the exact duration can vary depending on the nature of the offense and your driving history. For example, a second DWI conviction within a certain period may extend the filing requirement to three years or more. The Texas DPS will notify you of the specific period when they require the filing.
Even after the SR-22 requirement ends, the underlying offense may remain on your driving record for a longer period. Insurance companies may continue to see the violation and charge higher rates for several years. Shopping around for quotes from multiple carriers can help you find the best rate once the SR-22 is no longer required. You can use a comparison tool to get free quotes from multiple insurers and see how your rates change over time.
It is also worth noting that the SR-22 itself is not a permanent mark on your record. Once the filing period is over and your insurer notifies the DPS, the requirement is lifted. However, if you are required to file again in the future due to another offense, the process starts over.
What Happens If Your Policy Lapses During the SR-22 Period
A lapse in coverage during the SR-22 period is a serious matter. Your insurer is required to notify the Texas DPS if your policy is canceled or lapses for any reason, including non-payment. The DPS will then suspend your driver's license and vehicle registration, and you may face additional fines or fees to reinstate them. In some cases, you may be required to file a new SR-22 and start the filing period over again.
To avoid a lapse, consider setting up automatic payments with your insurer or paying your premium in full if possible. If you are struggling to afford your premium, talk to your agent about ways to lower your rate, such as increasing your deductible or adjusting your coverage. Do not let your policy lapse, even for a day, as the consequences can be costly and time-consuming.
If you do experience a lapse, contact your insurer immediately to see if the policy can be reinstated without a gap in coverage. If not, you will need to purchase a new policy and have the SR-22 filed again. You may also need to pay a reinstatement fee to the DPS and provide proof of financial responsibility before your license is restored.
Finding Affordable SR-22 Insurance in Texas
Drivers who need an SR-22 are often considered high-risk by insurance companies, which can lead to higher premiums. However, that does not mean you have to accept the first quote you receive. Shopping around and comparing rates from multiple insurers is the best way to find affordable coverage. Many companies specialize in high-risk drivers and may offer competitive rates, especially if you have completed a defensive driving course or have a clean record aside from the offense that triggered the SR-22.
When comparing quotes, make sure you are comparing apples to apples. Look at the coverage limits, deductibles, and any additional fees. Some insurers may charge a fee for filing the SR-22, while others include it in the premium. Ask about discounts, such as safe driver, multi-policy, or paid-in-full discounts, and see if you qualify. You can also check out our guide on how to get the best auto insurance quotes in Texas for more tips on saving money.
Working with an independent agent can also be helpful, as they can access multiple carriers and help you find the best combination of price and coverage. Be upfront about your SR-22 requirement so the agent can target the right companies. Remember that the cheapest policy is not always the best if it leaves you underinsured or if the company has poor customer service. Balance cost with reliability and coverage.
For additional resources and educational content about auto insurance, you can visit NewAutoInsurance, an independent online resource that provides consumer guidance and comparisons for vehicle owners in the United States.
Steps to Take Once Your SR-22 Requirement Ends
When your SR-22 filing period is over, you should take a few steps to ensure your record is clear and your insurance needs are up to date. First, confirm with your insurer that they have notified the Texas DPS that your obligation is complete. Then, check your driving record with the DPS to verify that the SR-22 requirement has been removed. If you find any discrepancies, contact the DPS or your insurer to resolve them.
Next, consider shopping for a new insurance policy. Once the SR-22 is no longer required, you may be eligible for lower rates from standard carriers. Use a comparison tool to get quotes from multiple companies and see how much you can save. You can also ask your current insurer if they offer a discount for drivers who have completed their SR-22 period.
Finally, maintain good driving habits to avoid future offenses that could lead to another SR-22 requirement. Keep your insurance active, drive safely, and address any traffic violations promptly. By staying proactive, you can leave the high-risk designation behind and enjoy lower premiums.
An SR-22 filing in Texas may feel like a burden, but it is a manageable process if you understand the requirements and stay organized. By maintaining continuous coverage, communicating with your insurer, and shopping for competitive rates, you can fulfill the obligation and move forward with a clean driving record.