Usage-Based Insurance Programs Pros and Cons for Drivers
Usage-based insurance programs pros and cons: safe drivers can save up to 30 percent, but privacy and surcharges are real risks. Compare quotes before you enroll.
By Imogen Clarke
Your driving habits might be the most powerful tool you have for lowering your auto insurance bill, or they might be the reason your rates climb higher than expected. Usage-based insurance programs have moved from a niche experiment to a mainstream option offered by many major carriers across the United States. These programs use telematics technology, either through a mobile app or a plug-in device, to track how, when, and how much you drive. The data collected then influences your premium, sometimes dramatically. For some drivers, this means significant savings and a fairer rate that reflects their actual behavior behind the wheel. For others, it can mean surprise surcharges, privacy concerns, and a complicated trade-off between savings and surveillance. Understanding the usage-based insurance programs pros and cons is essential before you enroll, because the wrong choice could cost you more than you save.
What Are Usage-Based Insurance Programs?
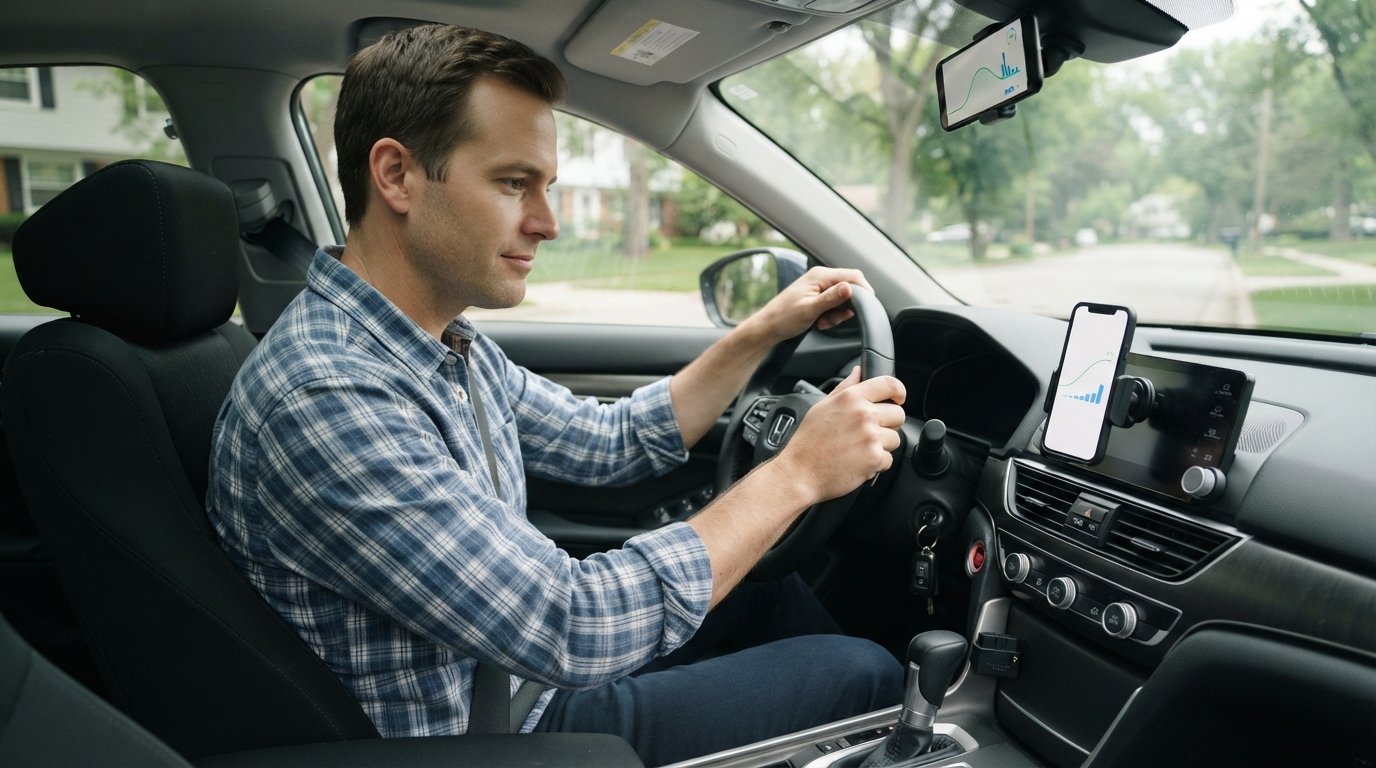
Usage-based insurance, often called UBI, telematics insurance, or pay-per-mile insurance, is a type of auto coverage where your premium is calculated partly or entirely based on your driving data. Traditional insurance relies on broad rating factors like your age, location, credit score, vehicle type, and driving record. Usage-based programs add a layer of real-time or near-real-time behavior tracking to that formula. The two main models are pay-how-you-drive (PHYD) and pay-per-mile (PPM). Pay-how-you-drive programs monitor things like hard braking, rapid acceleration, cornering speed, and phone distraction. Pay-per-mile programs focus primarily on the number of miles you drive, sometimes combined with basic behavior metrics.
Most major insurers now offer some form of telematics program. Some use a small device that plugs into your car's onboard diagnostics port, while others rely on a smartphone app that uses GPS and accelerometer data. The data is transmitted to the insurer, analyzed, and used to adjust your renewal premium or provide an immediate discount. Some programs offer an upfront discount just for signing up, while others wait until the monitoring period ends to determine your final rate. In our guide on usage-based insurance discounts, we explain how these programs calculate savings and what to expect during the enrollment process.
The appeal is straightforward: safe, low-mileage drivers should not pay the same as high-risk, high-mileage drivers. Usage-based insurance promises to reward good behavior with lower premiums and penalize risky behavior with higher ones. But the reality is more nuanced, and the pros and cons depend heavily on your individual driving profile, your state's regulations, and the specific program you choose. Before enrolling, it helps to compare quotes from multiple carriers, because not all usage-based programs are created equal, and some traditional policies may still offer better rates for certain drivers.
The Pros: Where Usage-Based Insurance Delivers Real Value
The most obvious advantage of usage-based insurance is the potential for lower premiums. If you are a safe driver who logs relatively few miles, you are exactly the profile these programs are designed to reward. Many insurers offer an initial discount of 5 to 15 percent just for enrolling, and that discount can grow to 30 percent or more after a full monitoring period if your driving data is favorable. For low-mileage drivers, pay-per-mile programs can be especially attractive because you only pay for the miles you actually drive, which can be a game-changer for retirees, remote workers, and city dwellers who rely on public transit.
Beyond savings, usage-based programs promote safer driving habits. When drivers know their behavior is being tracked, they tend to brake more gradually, accelerate more smoothly, and avoid distractions like phone use. This feedback loop can reduce accidents and improve overall road safety. Many programs also provide a dashboard or app that shows your driving score, helping you identify areas for improvement. This transparency can be empowering, especially for young drivers who are still building their skills and want to prove to insurers that they are responsible.
Another benefit is fairness. Traditional insurance pricing relies on proxies like age, gender, marital status, and credit score, which can feel arbitrary and even discriminatory. Usage-based insurance shifts the focus to actual behavior, which is a more direct measure of risk. If you are a safe driver who has been penalized by traditional rating factors, a telematics program might finally give you the rate you deserve. Here are some of the key advantages in summary:
- Potential for significant premium reductions, especially for safe, low-mileage drivers.
- Immediate enrollment discounts that apply before any data is even collected.
- Feedback that encourages safer driving and can reduce accident risk.
- Fairer pricing based on behavior rather than demographic proxies.
- Flexibility for drivers whose mileage varies seasonally or unpredictably.
These benefits are real, but they come with trade-offs. The same technology that rewards safe driving can also penalize you for habits you did not know were being measured. That is why it is critical to understand the cons before you sign up.
The Cons: Risks, Privacy Concerns, and Hidden Costs
The most significant downside of usage-based insurance is the potential for your rates to increase. If your driving data reveals risky behavior, such as frequent hard braking, late-night driving, or high mileage, your insurer may raise your premium at renewal. In some programs, a poor driving score can lead to a surcharge that exceeds what you would have paid on a traditional policy. This is especially risky for drivers who are not sure how their habits will be evaluated or who live in dense urban areas where sudden stops and quick accelerations are often unavoidable.
Privacy is another major concern. Telematics programs collect detailed data about your location, speed, time of day, and driving patterns. While insurers claim this data is used only for rating purposes, there is no guarantee that it will not be shared with third parties or used in other contexts, such as claims investigations. Some drivers are uncomfortable with the idea of their insurer knowing exactly where they go and when. In states with strict privacy laws, this concern may be mitigated, but in others, the data collection can feel intrusive.
There are also practical drawbacks. Not all vehicles are compatible with telematics devices, and some older cars may not have the necessary ports. Smartphone-based programs can drain your battery and use mobile data, which may be a problem if you have a limited data plan. Enrollment can also be complicated, with varying opt-in periods, cancellation policies, and requirements to maintain the program for a certain length of time. If you switch insurers mid-program, you may lose the discount you earned. Finally, usage-based programs are not available in all states, and some insurers offer them only in select markets.
For high-risk drivers, the cons may outweigh the pros. If you have a history of accidents, tickets, or DUI convictions, a telematics program could confirm the insurer's worst assumptions and lead to higher rates. In that case, you might be better off shopping for traditional coverage through a comparison platform that specializes in high-risk drivers. The key is to be honest with yourself about your driving habits and to read the fine print before enrolling.
How to Decide If a Usage-Based Program Is Right for You
Deciding whether to enroll in a usage-based insurance program requires a clear-eyed assessment of your driving habits, your tolerance for data collection, and your financial goals. Start by reviewing your typical driving patterns. Do you drive fewer than 10,000 miles per year? Do you avoid rush hour and late-night trips? Are you generally a cautious driver who rarely brakes hard or accelerates quickly? If you answered yes to most of these questions, a usage-based program is likely to work in your favor. If you drive a lot, frequently travel during high-risk hours, or have a lead foot, you may want to think twice.
Next, consider your comfort with data sharing. If the idea of your insurer tracking your every move makes you uneasy, a pay-per-mile program that only records mileage might be a better fit than a full telematics program that monitors behavior. You should also check the specific terms of the program: How long is the monitoring period? Can you cancel without penalty? Will the discount apply immediately or only at renewal? What happens if you switch insurers? These details can make or break the value proposition.
It also helps to compare quotes from multiple carriers, both those that offer usage-based programs and those that do not. Sometimes a traditional policy with a safe driver discount can beat a telematics program, especially if you have a clean record and a good credit score. For drivers in Texas, for example, comparing Texas auto insurance quotes side by side can reveal whether a usage-based program is truly the cheapest option. The same is true in other states with unique insurance markets.
If you decide to move forward, here is a simple framework to follow:
- Review your driving data from the past six to twelve months, including mileage, commute times, and any incidents.
- Research at least three insurers that offer usage-based programs in your state.
- Compare the enrollment discounts, monitoring periods, and potential surcharges.
- Read the privacy policy and data-sharing terms carefully.
- Request quotes from both telematics and traditional policies to see which is cheaper for your profile.
After you enroll, monitor your driving score regularly and adjust your habits if needed. Many programs offer weekly summaries that can help you stay on track. If you find that your rates are rising instead of falling, you may be able to switch to a traditional policy at renewal, though you may lose any accrued discounts. For a broader look at how telematics fits into the insurance landscape, independent resources like NewAutoInsurance provide consumer guidance and comparisons that can help you make an informed decision.
The Future of Usage-Based Insurance and What It Means for Drivers
Usage-based insurance is not going away. As vehicles become more connected and telematics technology improves, insurers will continue to refine their programs and expand their reach. Some industry analysts predict that usage-based policies will eventually become the default for many drivers, much like safe driver discounts are today. This could lead to more personalized pricing, but it also raises questions about data ownership, privacy, and fairness. Regulators in some states are already grappling with how to oversee telematics programs and protect consumers from unfair rate increases.
For drivers, the best strategy is to stay informed and proactive. Do not assume that a usage-based program will automatically save you money. Do your homework, compare quotes, and read the terms. If you are a safe, low-mileage driver, you may find that telematics is a powerful tool for reducing your premium. If you are a high-mileage or high-risk driver, you may be better off with a traditional policy and a focus on improving your driving record over time. Either way, the more you know about usage-based insurance programs pros and cons, the better equipped you will be to make a choice that fits your budget and your lifestyle.
Ultimately, usage-based insurance is a trade-off: you give up some privacy and predictability in exchange for the chance to pay less. For some drivers, that is a bargain. For others, it is not worth the risk. By understanding both sides of the equation, you can decide which path is right for you and your family. And if you are ready to explore your options, start by getting free, no-obligation quotes from multiple carriers. It is the simplest way to see what is available in your area and whether a usage-based program could put money back in your pocket.