What Documents Do I Need for an Auto Insurance Quote?
Gather your driver's license, VIN, and current policy details to get accurate auto insurance quotes. Call (833)-275-7533 for personalized help.
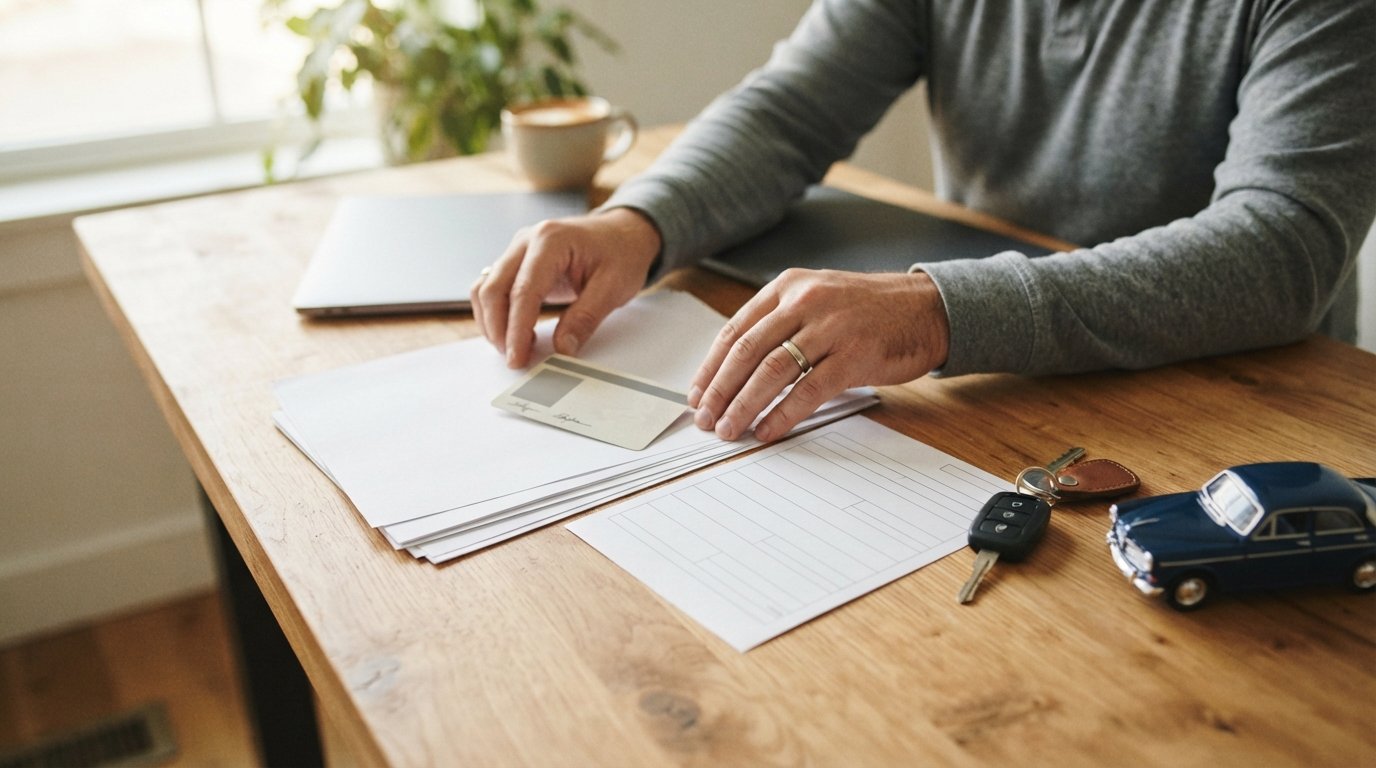
Before you start comparing rates, knowing exactly what paperwork to gather can turn a confusing process into a quick, painless one. Whether you are a first-time driver, adding a new car to your policy, or simply shopping for a better deal, having the right documents ready will help you get accurate quotes and avoid delays. This guide walks you through the specific items you need, explains why each matters, and shows how to prepare for a smooth quoting experience.
Essential Documents for Every Driver
Every auto insurance quote starts with basic information about you and your vehicle. Insurers use this data to assess risk and calculate your premium, so accuracy is critical. If you provide incomplete or incorrect details, the final policy price could change after underwriting, leading to unpleasant surprises.
At a minimum, you will need to provide your driver's license information, your vehicle's identification number (VIN), and details about your current coverage if you have one. These three items form the foundation of any quote. Let us break them down one by one.
Driver's License Details
Your driver's license is the primary piece of identification for insurance purposes. Insurers need your license number, the state that issued it, and the date it was first issued. They may also ask about traffic violations or accidents in the past three to five years. Having your license handy ensures you can provide accurate information without guessing.
If you are shopping for a policy for a household with multiple drivers, you will need license details for every person who will be listed on the policy. This includes family members who live with you and drive your vehicles, even if they have their own insurance. Insurers want to know who has regular access to the car to properly assess risk.
Vehicle Identification Number (VIN)
The VIN is a 17-character code that uniquely identifies your vehicle. It reveals the make, model, year, trim level, and even the engine type. Insurers use the VIN to determine the vehicle's value, safety features, and repair costs, all of which affect your premium. You can find the VIN on your vehicle registration card, on the driver's side dashboard near the windshield, or on the inside of the driver's door jamb.
When you request a quote, providing the VIN upfront ensures that the insurer quotes the exact vehicle you drive, not a similar model that might have different risk characteristics. This eliminates discrepancies and helps you compare apples to apples when evaluating quotes from different carriers.
Current Insurance Information
If you currently have auto insurance, the quoting process will ask for your current carrier's name, your policy number, and your coverage limits. This information serves several purposes. First, it allows the new insurer to see what coverage you have now so they can offer comparable or better options. Second, it helps identify any discounts you might qualify for, such as a loyalty discount or a discount for switching from a competitor.
Even if you are not currently insured, you should be prepared to explain any gaps in coverage. Some insurers offer lower rates to drivers who have maintained continuous coverage, so knowing your history is helpful. If you are switching from another carrier, having your current declarations page (the summary of your policy) can make the process faster.
Why Garaging Address and Annual Mileage Matter
Two pieces of information that often surprise drivers are the garaging address and annual mileage. These factors play a significant role in how insurers calculate your premium, and they are required for almost every quote.
The garaging address is where your vehicle is primarily parked overnight. It matters because theft rates vary by location, and insurers use this data to assess risk. Even if your mailing address differs, you must provide the address where the car is kept most of the time. Providing a false garaging address can be considered insurance fraud, so accuracy is essential.
Annual mileage is the estimated number of miles you drive per year. Insurers use this to gauge your exposure to accidents: the more you drive, the higher the risk. Most people have a rough idea of their annual mileage, but you can check your odometer or recent service records for a more precise figure. If you are unsure, a good rule of thumb is to divide your total miles driven since your last oil change by the number of months and multiply by 12.
These two factors are so important that some insurers will not provide a firm quote without them. Having them ready before you start will save time and help you get more accurate estimates.
Information for Additional Drivers and Household Members
Auto insurance quotes are not just about you and your car. If you share your household with other licensed drivers, their information may be required as well. Insurers typically want to know about all drivers in the household because they could have access to your vehicle.
For each additional driver, you will need to provide their name, date of birth, driver's license number, and any relevant driving history. This includes spouses, domestic partners, roommates, and teenage children. Even if a household member has their own car and insurance, some insurers still require them to be listed or excluded from your policy.
If you have a young driver in the household, their information is especially important because they can significantly impact your premium. Having their license details and driving record ready will help you get a realistic quote that reflects the true cost of adding them to your policy.
Documents for Special Situations
Some drivers have unique circumstances that require additional documentation. Being aware of these requirements can prevent delays and ensure you get the most accurate quote possible.
SR-22 Filings
If you have been convicted of certain driving offenses, such as DUI or driving without insurance, you may be required to file an SR-22 form with your state's DMV. This form proves that you carry the minimum required liability insurance. When getting a quote, you will need to disclose that you require an SR-22 filing, as not all insurers offer this type of policy. Having your court or DMV paperwork available will help the insurer understand your situation and provide an accurate quote.
Leased Vehicles
If your car is leased, the leasing company typically requires you to carry certain coverage levels, often higher than your state's minimum. When requesting a quote for a leased vehicle, you will need your lease agreement or a statement from the leasing company showing the required coverage limits. This ensures that the quoted policy meets the lease terms and protects you from financial penalties at the end of the lease.
High-Risk Drivers
Drivers with a history of accidents, tickets, or DUIs are considered high-risk by insurers. In addition to your driver's license and vehicle information, you may need to provide details about each incident, including dates and whether you were at fault. Some insurers may also ask for proof of completion of defensive driving courses or other remedial programs. Having this documentation ready can help you find insurers who specialize in high-risk policies and potentially secure better rates.
How to Prepare for a Free Quote Form
Now that you know what documents you need, the next step is to organize them before you start filling out quote forms. A little preparation goes a long way toward getting accurate quotes quickly.
Start by gathering the following items in one place:
- Your driver's license (and those of any additional drivers)
- Your vehicle's VIN and current registration
- Your current insurance policy declarations page (if applicable)
- Your garaging address and estimated annual mileage
- Any special documentation (SR-22, lease agreement, etc.)
Once you have these items, you can confidently fill out online quote forms or speak with an agent. Many quote forms will ask for the same information, so having it all in one place speeds up the process. You can also use our guide on how to get the best auto insurance quotes in Texas for state-specific tips if you live in the Lone Star State.
For a seamless experience, consider using a comparison platform that asks for all the necessary details upfront. This approach saves you from repeating information and ensures you receive multiple quotes from licensed agents who can tailor coverage to your needs.
Frequently Asked Questions
Do I need my Social Security number to get a quote?
In many cases, insurers will ask for your Social Security number to run a credit-based insurance score, which is used in most states to determine rates. However, you can often get a preliminary quote without it and provide it later when you are ready to purchase. If you are uncomfortable sharing your SSN online, you can request quotes by phone or provide it only to the agent you choose to work with.
What if I don't have my VIN handy?
You can still get a quote using your vehicle's make, model, year, and trim level, but the quote may be less accurate. The VIN ensures the insurer knows exactly which vehicle you drive, including optional features that affect repair costs. It is best to locate your VIN before finalizing a quote.
Can I get a quote if I have a suspended license?
Yes, but you will need to disclose the suspension and provide details about when it will be reinstated. Some insurers specialize in non-standard policies for drivers with license issues. You may need to provide court documents or proof of reinstatement to get an accurate quote.
What information do I need for a business vehicle?
If you are insuring a vehicle used for business purposes, you will need additional information such as your business tax ID, the vehicle's primary use (e.g., delivery, sales), and the estimated annual mileage for business use. Commercial auto insurance quotes often require more detailed documentation than personal policies.
Getting an auto insurance quote does not have to be a hassle. With the right documents in hand, you can quickly compare rates from multiple insurers and find the coverage that fits your needs and budget. Taking a few minutes to gather your license, VIN, and other key details will pay off with accurate quotes and potential savings. For more educational resources and to compare quotes from licensed agents, visit NewAutoInsurance, an independent online resource for consumer guidance.