What Is Accident Forgiveness and How Do You Qualify?
Accident forgiveness waives the surcharge after a first at-fault crash. Call (833)-275-7533 to compare quotes and see if you qualify.
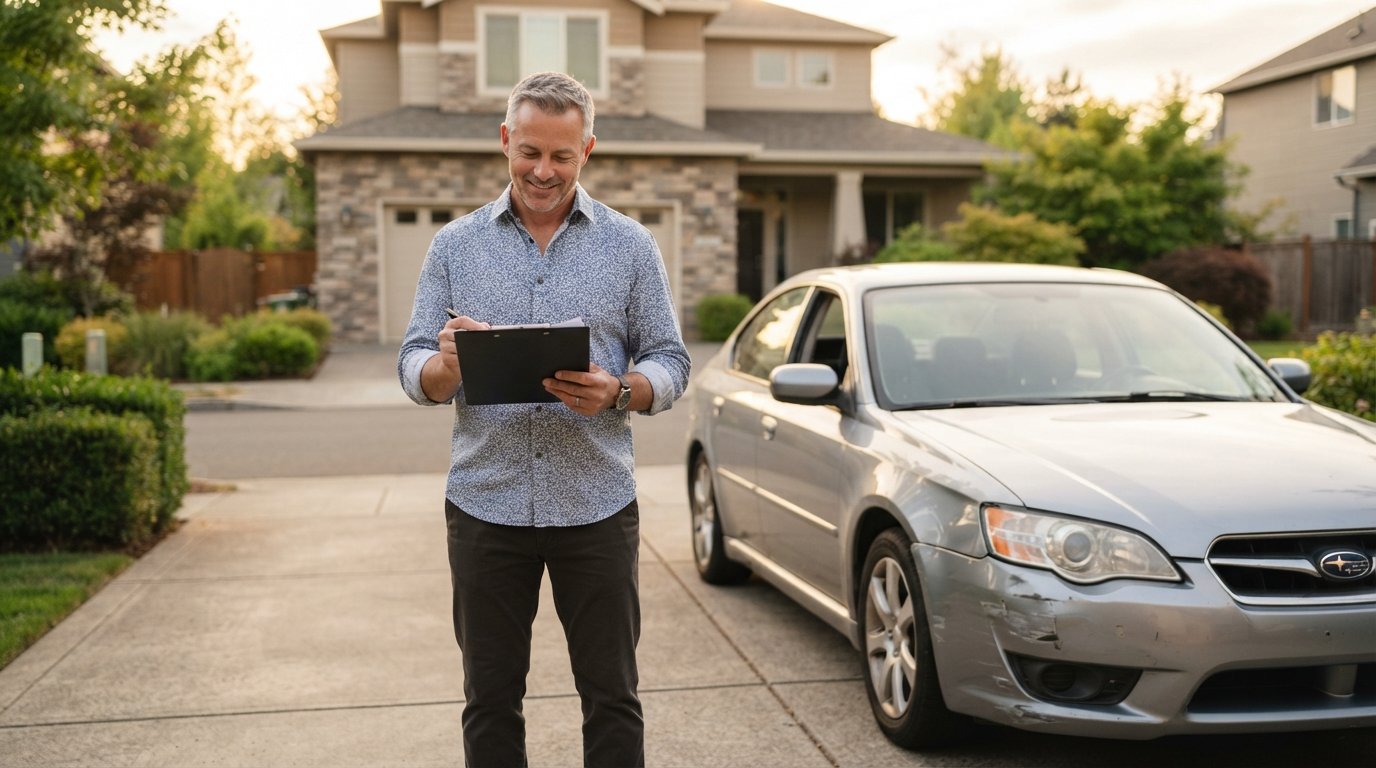
A single at-fault accident can raise your auto insurance premium by hundreds of dollars a year, and that increase often follows you for three to five years. For many drivers, the financial sting of the accident itself is bad enough without the added burden of a surcharge on every renewal. Accident forgiveness exists to soften that blow, but it is one of the most misunderstood features in auto insurance. Drivers often assume it wipes the accident off their record, or that every insurer offers it automatically. Neither assumption is true. Understanding what accident forgiveness actually does, who qualifies for it, and how to compare it across carriers can save you real money and prevent unpleasant surprises at claim time.
This guide breaks down the feature in plain terms, explains the most common qualification rules, and shows you how to shop for it intelligently. Whether you are a long-tenured policyholder with a clean record or a newer driver trying to build one, knowing the fine print will help you make a smarter decision when you request quotes.
Defining Accident Forgiveness in Plain Terms
Accident forgiveness is a carrier-specific policy feature that waives the surcharge a driver would normally face after a first at-fault accident. It is important to be precise here: the feature forgives the premium increase, not the accident itself. The claim still exists on your insurance history, the insurer still pays for covered damages, and other carriers may still see the incident when they pull your record. What changes is that your current insurer agrees not to raise your rate because of that one accident.
Think of it as a pricing benefit rather than a claims benefit. If you cause a collision and your insurer pays out for the other driver's repairs, accident forgiveness means your renewal premium stays at its current level instead of jumping to a higher tier. That distinction matters because some drivers expect the accident to disappear entirely, then feel misled when they see the claim listed on a future insurance history report. The payout is not prevented, and the record is not erased. The surcharge is simply waived.
Carriers structure the feature in different ways. Some build it into certain policies automatically, while others sell it as an optional add-on. Some apply it only to the policyholder's first at-fault accident, while others allow it once every three or five years. A few insurers market a similar benefit under names like "forgiveness" or "safe driver" programs. Because terms vary so widely, the feature is best understood as a family of programs rather than a single standardized product.
One more nuance: accident forgiveness usually applies only to the surcharge on your own policy. It does not prevent the at-fault accident from affecting your rate if you switch carriers, and it does not stop a ticket or violation from raising your premium. It is a narrow but valuable benefit that protects your rate with your current insurer at the moment you need it most.
How Accident Forgiveness Works When You File a Claim
The mechanics are straightforward once you know what to expect. You cause an accident, you file a claim, your insurer pays for the covered damages, and then at renewal the company determines whether a surcharge would normally apply. If you qualify for accident forgiveness, that surcharge is removed or never applied. Your rate stays at the level it would have been without the accident, at least with respect to that incident.
Timing matters. Some carriers apply forgiveness automatically when the claim is processed, while others require you to have held the feature for a certain period before the accident occurs. A common rule is that the benefit activates only after you have been accident-free for a set number of years, or only after you have been with the carrier for a certain tenure. If you buy the add-on and crash a week later, you may not be covered by the forgiveness provision yet.
It also helps to understand what "surcharge" means in practice. Insurers use rating tiers and surcharge points to price risk. An at-fault accident typically moves you into a higher-priced tier, and the increase can range from modest to severe depending on the claim amount, your state, and the carrier's rating plan. Accident forgiveness keeps you out of that higher tier for the forgiven incident, which is why the savings can be substantial over several renewal cycles.
If you are comparing policies, ask each carrier three specific questions: Does the policy include accident forgiveness automatically or as an add-on? What is the waiting period before it applies? And does it cover one accident, or one every few years? The answers will tell you whether the feature is genuinely useful for your situation or just a marketing line.
Common Qualification Rules You Should Expect
Qualification rules vary by carrier, but most programs share a recognizable structure. Insurers want to reward stable, low-risk customers, so the requirements tend to revolve around your driving record and your relationship with the company. Before you assume you qualify, check the specific terms in your policy or ask a licensed agent to walk you through them.
The most common requirements include:
- Accident-free years: Many programs require three to five years of clean driving before the benefit activates, and some require a longer period for the first forgiveness to apply.
- Policy tenure: Carriers often require you to have been a customer for a set period, sometimes one to three years, before accident forgiveness kicks in.
- Clean record thresholds: Major violations, DUI convictions, or multiple at-fault accidents in a short window usually disqualify a driver from the program.
- Purchase of the add-on: Some insurers sell accident forgiveness as an optional coverage, so you must opt in and pay the additional premium before the accident occurs.
- One forgiveness per period: Most programs forgive a single at-fault accident within a defined window, such as every three or five years.
Beyond those basics, some carriers impose additional conditions. A program might exclude accidents that involve serious injuries, DUI charges, or extremely high claim amounts. Others may limit forgiveness to accidents where the policyholder was not the primary cause, or they may require that all drivers on the policy meet the clean-record standard. Household composition can matter too: if a high-risk driver is added to your policy, the carrier may suspend or revoke the forgiveness benefit for everyone on the policy.
State regulations also shape how these programs work. Some states restrict how insurers can price surcharges and discounts, which can affect whether accident forgiveness is available or how it is applied. If you live in a state with tight rate-regulation rules, ask the carrier directly whether the feature is offered and how it interacts with state filing requirements. The answer can differ from what you read in a national brochure.
What Accident Forgiveness Does Not Do
The biggest source of confusion is the belief that accident forgiveness erases the accident. It does not. The claim remains on your insurance history, and other carriers will see it when you shop for a new policy. If you switch insurers after using forgiveness, the new company may still charge a higher rate because of the at-fault accident. The benefit protects your rate with your current carrier, not your record across the entire market.
It also does not prevent the insurer from paying the claim. The other driver's repairs, your covered collision damage, and any liability payments are still handled according to your policy. Accident forgiveness is purely a pricing mechanism, not a claims-suppression tool. And it does not protect you from non-accident rating factors: a speeding ticket, a DUI, or a lapse in coverage can still raise your premium even if the accident itself is forgiven.
Finally, it does not guarantee that your rate will never rise. Insurers can adjust rates for many reasons, including inflation, repair costs, and changes in state-approved rating plans. Accident forgiveness only addresses the surcharge tied to the forgiven accident. If your carrier files a broad rate increase, your premium can still go up even with the forgiveness benefit in place.
Understanding these limits helps you set realistic expectations. Accident forgiveness is a valuable safety net for a first at-fault accident, but it is not a substitute for a clean driving record or a thorough comparison of quotes. Drivers who understand the boundaries of the feature tend to make better decisions about whether the add-on is worth the cost.
How to Qualify and What to Ask When Comparing Quotes
Qualifying for accident forgiveness starts with knowing your own record and shopping strategically. Before you request quotes, gather your driving history, note any at-fault accidents or violations in the past five years, and decide how long you plan to stay with a carrier. Then ask each insurer the same set of questions so you can compare apples to apples.
A practical step-by-step approach looks like this:
- Review your motor vehicle record and insurance history so you know what carriers will see.
- Ask each carrier whether accident forgiveness is included, optional, or unavailable in your state.
- Confirm the waiting period, the number of accidents covered, and any exclusions for serious violations.
- Compare the total cost of the policy with and without the add-on, not just the base premium.
- Ask how the feature interacts with other discounts and whether it survives a policy change or vehicle addition.
That last point is easy to overlook. Some programs are tied to a specific vehicle or policy form, and adding a new driver or replacing a car can affect eligibility. If you are planning a major life change, such as adding a teen driver or buying a new vehicle, ask how the forgiveness benefit will be affected before you commit.
It also pays to think about your long-term plans. If you switch carriers every year or two to chase the lowest rate, accident forgiveness may never activate because you never meet the tenure requirement. Drivers who value the benefit should weigh it against the savings from frequent switching. For a deeper look at how the feature protects rates over time, see this guide on accident forgiveness and rate protection, which explains how the benefit fits into a broader rate strategy.
Finally, remember that accident forgiveness is only one piece of a well-built policy. Drivers who are also managing a car loan should think about how insurance and financing interact. If you are exploring options to refinance your car loan, keep in mind that lenders often require certain coverage levels, and your insurance choices can affect your overall monthly costs. Balancing loan terms and insurance features is part of a sound financial plan.
Is Accident Forgiveness Worth It?
Whether the feature is worth the cost depends on your risk profile and your tolerance for premium swings. Drivers with a long clean record and a stable relationship with one carrier often get the benefit automatically or for a modest add-on premium. For them, it is inexpensive peace of mind. Drivers who switch carriers often, have a history of claims, or live in states where the feature is restricted may find that the cost outweighs the benefit.
A simple way to decide is to estimate the surcharge you would face after a first at-fault accident. If your premium would jump by several hundred dollars a year for three years, the math often favors paying a small amount now for forgiveness later. If the potential surcharge is modest or your state limits how much insurers can raise rates after an accident, the add-on may be less compelling.
It also helps to compare the feature across multiple carriers rather than accepting the first quote you receive. Because terms vary so widely, the same driver can get very different forgiveness benefits from different insurers at similar base prices. A side-by-side comparison of quotes, including the fine print on forgiveness, is the most reliable way to find the best combination of price and protection.
Accident forgiveness is not a magic shield, but it is a practical tool for managing one of the most common causes of premium increases. Know the rules, ask the right questions, and compare quotes carefully. That approach will help you qualify for the benefit where it makes sense and avoid paying for a feature that does not fit your situation.