What Is Custom Equipment Coverage on a Car Policy?
Custom equipment coverage protects aftermarket additions like lifts and audio systems. Call (833)-275-7533 to compare quotes and close coverage gaps.
By Celeste Rowan
Your car is more than a factory-built machine. It is a rolling toolbox, a mobile office, a concert hall on wheels, or a lifeline for a family member with mobility needs. That aftermarket stereo system, the wheelchair lift in your van, the ladder rack holding your tools, or the custom leather seats you saved for months to buy, none of these come standard from the dealership. If you assume your auto policy treats them like the rest of the vehicle, you could be in for a costly surprise after a collision or theft. Understanding what is custom equipment coverage on a car insurance policy is the first step toward protecting the investments you have added to your vehicle. This guide breaks down how insurers define custom equipment, what is typically covered, where the gaps hide, and how to close them with the right endorsement.
Defining Custom Equipment Versus Factory Options
The dividing line between factory options and custom equipment is not always obvious, but insurers draw it clearly. Factory-installed options are features that came with the vehicle when it rolled off the assembly line or were installed by the manufacturer before the first sale. Think of a sunroof, upgraded wheels, a premium sound system, or a towing package that appears on the original window sticker. These are generally included in the vehicle's actual cash value or replacement cost, depending on your policy type, and they do not require special treatment.
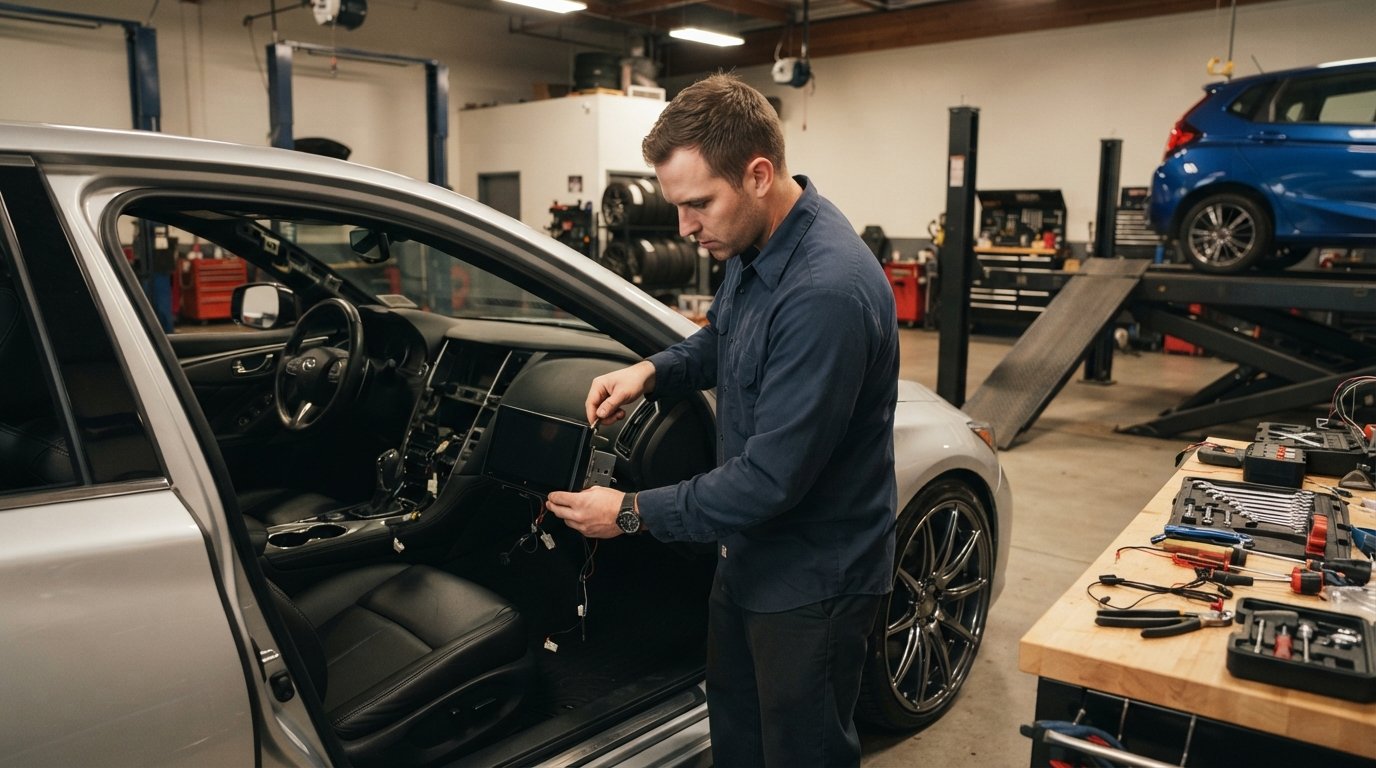
Custom equipment, by contrast, is anything added after the vehicle was manufactured and is not part of the original factory build. This category includes a wide range of items that owners install to enhance performance, comfort, utility, or accessibility. The key is that the modification happens after the vehicle leaves the factory, whether by a dealer, a specialty shop, or the owner. Insurers often use the term "custom parts or equipment" to describe these additions, and standard policies frequently cap coverage for them at a low dollar amount, sometimes as little as $1,000, or exclude them entirely unless you add an endorsement.
Here is where the confusion often starts: a dealer-installed option at the time of purchase might feel like a factory feature, but many insurers still classify it as custom equipment if it was not installed at the factory. Similarly, a replacement part that is not original equipment manufacturer (OEM) spec could be treated as custom. To avoid disputes, review your policy language and ask your agent how your insurer treats dealer-installed accessories. The distinction matters because it determines whether your standard policy pays to repair or replace the item after a covered loss, or whether you need to add specific coverage.
Common examples of custom equipment include:
- Aftermarket audio and video systems, including subwoofers, amplifiers, and custom speaker enclosures
- Wheelchair lifts, ramps, and adaptive driving controls for accessibility
- Ladder racks, toolboxes, and cargo management systems for work vehicles
- Custom wheels, lift kits, and suspension modifications
- Specialized paint, wraps, and interior upholstery upgrades
Each of these items can add thousands of dollars to your vehicle's value, and each represents a potential gap in a standard policy. Recognizing what falls into this category is the foundation for deciding whether you need additional protection.
How Standard Policies Treat Custom Equipment
Most standard auto insurance policies include a small amount of coverage for custom equipment, but the limits are modest and the conditions are strict. A typical policy might cover up to $1,000 for custom parts or equipment, and that coverage often applies only if the items are permanently installed on the vehicle. Portable items, such as a removable GPS unit, a laptop, or a detachable tool set, are usually excluded from auto coverage altogether and may need to be covered under a homeowners or renters policy instead.
The distinction between permanently installed and portable equipment is critical. A wheelchair lift bolted to the floor of a van is generally considered permanently installed and may fall under the custom equipment provision, subject to the policy limit. A removable ramp that you stow in the trunk between uses might be treated as personal property and excluded from the auto policy. Similarly, a custom stereo system wired into the dashboard is likely covered as custom equipment, while a portable Bluetooth speaker sitting on the passenger seat is not. Insurers look at how the item is attached, whether it requires tools to remove, and whether it is integral to the vehicle's operation or function.
Another limitation is that standard policies often cover custom equipment only for specific perils. If your policy is a broadform or includes comprehensive and collision coverage, you may have better protection, but liability-only policies typically do not cover damage to your own custom equipment at all. Even with comprehensive coverage, the low limit can leave you underinsured if your additions are valuable. For example, a $5,000 custom audio system would exceed a $1,000 custom equipment limit, leaving you responsible for the difference. This is why many drivers with significant modifications choose to add a custom equipment endorsement, which raises the limit and broadens protection.
It is also worth noting that some policies exclude coverage for equipment used in a business or for commercial purposes. If you use your vehicle for work and carry expensive tools or equipment, your personal auto policy may not respond to a claim, even if the items are permanently installed. In those cases, a commercial auto policy or a separate inland marine floater may be necessary. Understanding these nuances helps you avoid the trap of assuming your standard policy has you covered when it does not.
When Commercial Use Equipment Needs Separate Coverage
Personal auto policies are designed for personal use, and they often draw a hard line when it comes to business-related equipment. If your vehicle is used for work and carries equipment that is essential to your trade, such as plumbing tools, photography gear, or medical equipment, your personal policy may exclude coverage for those items. Even if the equipment is permanently installed, the commercial nature of the use can trigger an exclusion. This is a common pitfall for small business owners, contractors, and gig workers who assume their personal policy will protect their work tools.
Commercial auto policies are built to handle these situations, but they may still have limits for custom equipment. Some commercial policies include coverage for permanently installed equipment, while others require a separate endorsement or a floater. For portable tools and equipment, an inland marine policy or a commercial property policy is often the better fit because it can cover items in transit and at multiple locations. The key is to have an honest conversation with your agent about how you use your vehicle and what you carry, so the policy matches your actual risk.
Consider a contractor who installs a $10,000 ladder rack and tool storage system on a pickup truck. If the truck is used solely for personal errands, a personal auto policy with a custom equipment endorsement might suffice. But if the truck is used to haul materials to job sites and the rack holds tools that are essential to the business, a commercial auto policy is likely necessary. The same logic applies to mobile detailing businesses, catering operations, and any other trade where the vehicle and its equipment are part of the business. Getting this wrong can mean a denied claim and a significant financial loss.
Documenting Value With Receipts and Photos
Even with the right coverage, claims can go sideways if you cannot prove what you had. Insurers pay based on evidence, and the burden of documenting custom equipment falls on you. Keeping a detailed record of your modifications is one of the most practical steps you can take to ensure a smooth claims process. Without documentation, an adjuster may default to a generic value or deny the claim entirely, leaving you to absorb the cost.
Start by saving receipts for every purchase, including the equipment itself and any installation labor. If you bought items used or received them as gifts, take photos and note the estimated value. Create a digital folder with photos of the equipment installed on the vehicle, close-ups of serial numbers or model numbers, and wide shots that show the item in context. Update this record whenever you add or change equipment, and store it in the cloud so it is accessible even if your phone or computer is lost. Some insurers allow you to submit this documentation when you add the endorsement, which can streamline the process later.
Here is a simple documentation checklist to follow:
- Photograph each custom item from multiple angles, including any visible serial or model numbers.
- Save digital copies of receipts, invoices, and installation work orders.
- Record a short video walkaround of the vehicle showing all modifications.
- Keep a written inventory with purchase dates, costs, and current estimated value.
- Review and update the inventory annually or whenever you add new equipment.
This documentation does double duty. It supports your claim if you ever need to file one, and it helps you set an accurate coverage limit when you add the endorsement. Underinsuring your equipment because you forgot how much you spent is a common mistake, and a thorough inventory prevents it.
Adding Coverage With a Custom Equipment Endorsement
The good news is that closing the coverage gap is straightforward. Most insurers offer a custom equipment endorsement, sometimes called a custom parts and equipment (CPE) endorsement, that increases the limit of coverage for aftermarket additions. This endorsement is added to your existing policy and typically costs a modest premium relative to the value it protects. The exact terms vary by insurer and state, but the endorsement generally raises the coverage limit to a level you choose, such as $5,000, $10,000, or more, and may broaden the perils covered.
To add the endorsement, you will need to provide a description of the equipment, its value, and supporting documentation. Some insurers require an inspection or photos before approving the endorsement, especially for high-value items. Once in place, the endorsement ensures that a covered loss will pay to repair or replace your custom equipment up to the stated limit, rather than the low default amount. If you are comparing quotes from multiple carriers, ask specifically how each one handles custom equipment and whether the endorsement is available. You can start by getting free quotes from multiple carriers to see which ones offer the best combination of base rate and endorsement pricing for your needs.
Keep in mind that the endorsement is not a substitute for commercial coverage if you use the vehicle for business. It is designed for personal-use vehicles with added equipment. If your situation involves business use, discuss commercial auto options with a licensed agent. For drivers who need to remove a vehicle from a policy during a sale or change, our guide on how to remove a car from your auto insurance policy explains the correct steps to avoid coverage gaps and premium errors. And for a broader look at how different coverage types fit together, independent resources like NewAutoInsurance provide educational comparisons that can help you make informed decisions.
Before finalizing any endorsement, review the policy language for exclusions. Some endorsements exclude coverage for certain types of equipment, such as items used for racing or off-road competitions, or equipment that is not permanently installed. Others may have a separate deductible for custom equipment claims. Understanding these details ensures that the coverage you buy actually matches the protection you expect. A quick call to your agent can clarify the specifics and help you choose the right limit.
Frequently Asked Questions About Custom Equipment Coverage
Drivers often have specific questions about how custom equipment coverage works in practice. Here are answers to some of the most common inquiries.
Does custom equipment coverage apply to leased vehicles?
It can, but the rules depend on the leasing company and the insurer. If you add equipment to a leased vehicle, you generally need to notify the leasing company and ensure the equipment is covered. Some leases prohibit permanent modifications, so check your lease agreement before installing anything. If approved, a custom equipment endorsement can be added to the policy, but you may need to remove the equipment before returning the vehicle to avoid penalties.
What happens if I do not add the endorsement?
Without the endorsement, your custom equipment is subject to the standard policy limit, which is often low. If your equipment is worth more than that limit, you will be responsible for the difference after a covered loss. In some cases, the equipment may be excluded entirely if it falls outside the policy's definition of covered property. Adding the endorsement is the only reliable way to ensure full protection.
Are portable items ever covered by auto insurance?
Generally, no. Portable items like removable GPS units, laptops, and detachable tool sets are typically considered personal property and are excluded from auto coverage. They may be covered under a homeowners or renters policy, subject to that policy's deductible and limits. If you carry valuable portable equipment in your vehicle, consider a separate floater or inland marine policy to cover it.
Understanding what is custom equipment coverage on a car insurance policy empowers you to make smart choices about your vehicle and your budget. Whether you have a modest aftermarket stereo or a complex wheelchair lift system, the right coverage ensures that a covered loss does not wipe out your investment. Take a few minutes to inventory your equipment, review your policy limits, and talk to a licensed agent about adding an endorsement. It is a small step that can save you thousands of dollars and a lot of frustration down the road.