Car Insurance for Older High Mileage Vehicles
Compare car insurance for drivers with older high mileage vehicles and decide if full coverage is worth it. Call (833)-275-7533 for expert help.
By Brielle Hawthorne
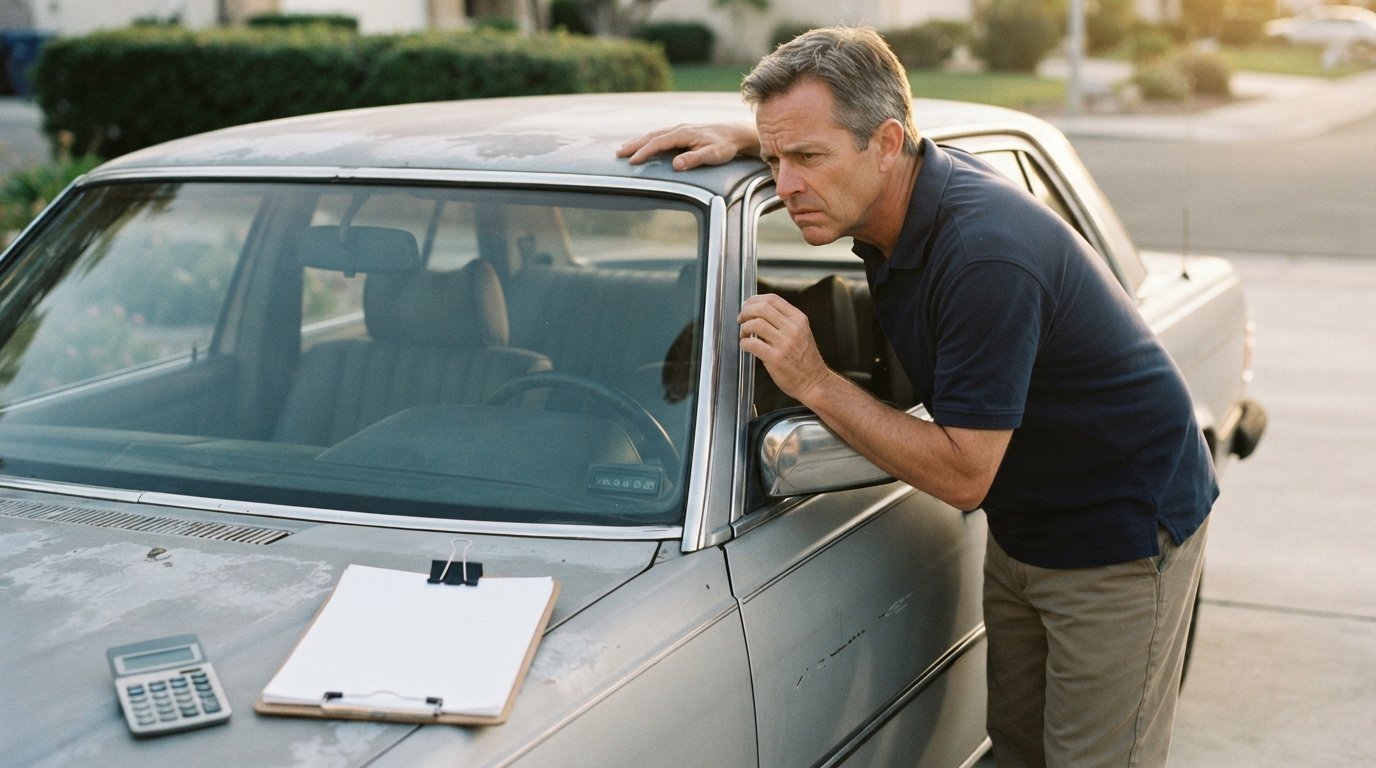
Your odometer just rolled past 150,000 miles, the paint has a few new scratches, and the air conditioning groans on hot days. You love this car, but every renewal notice for your auto policy seems to cost more, not less. It is a frustrating paradox: the vehicle is worth less than ever, yet the insurance bill stays stubbornly high. If you are like most drivers, you have wondered whether keeping full coverage on an aging, high mileage vehicle still makes financial sense or if you are simply throwing money at a depreciating asset. The answer is not a simple yes or no, but a calculation that balances risk, budget, and the actual value of your car. Understanding how insurers view older vehicles and where you can legitimately cut costs is the key to making a smart decision for your wallet and your peace of mind.
How Insurers View Age and Mileage on Your Policy
Insurance companies are in the business of predicting risk, and both age and mileage are powerful predictors. A newer car is generally safer, has more safety features, and is cheaper to repair with readily available parts. An older car with high mileage, on the other hand, presents a different profile. Insurers see a higher likelihood of mechanical failure, a greater chance of breakdowns that lead to accidents, and a higher probability that the cost of repairs could exceed the vehicle's actual cash value (ACV). This is why you often see premiums for physical damage coverage (collision and comprehensive) remain relatively stable or even increase as a car ages, even though the payout in a total loss scenario would be much lower.
However, this does not mean you are powerless. The core of the issue is the relationship between your premium and your car's value. While liability coverage (which pays for damage you cause to others) is mandatory in almost every state and is not directly tied to your car's value, the optional coverages like collision and comprehensive are where the math becomes critical. Insurers calculate the maximum payout for these coverages based on your car's ACV. As your car depreciates, that maximum payout shrinks, but your premium may not shrink at the same rate. This growing gap is the signal that it might be time to reevaluate your coverage strategy.
The 10 Percent Rule of Thumb for Premium vs. Car Value
Financial experts and insurance professionals often recommend a simple guideline to help drivers decide whether to keep full coverage: the 10 percent rule. The rule suggests that if your annual premium for collision and comprehensive coverage exceeds 10 percent of your car's current market value, it is probably not worth keeping that coverage. For example, if your car is worth $3,000 and your annual premium for collision and comprehensive is $400, that is 13.3 percent of the car's value. In this case, you are paying a significant portion of the car's total worth each year just to insure it against damage.
To apply this rule, you first need to determine your car's actual cash value. You can get a realistic estimate from sources like Kelley Blue Book, Edmunds, or by checking local listings for similar vehicles with similar mileage and condition. Be honest about the condition; a private party sale value is usually lower than a dealer retail price. Once you have that number, look at your policy declarations page to see exactly how much you are paying for collision and comprehensive coverage separately from your liability coverage. If the combined cost of those two coverages is more than 10 percent of the car's value, dropping them and pocketing the savings is a financially sound move. You are essentially self-insuring for the risk of damaging a low-value asset.
It is important to remember that this is a guideline, not a hard rule. If you have a $1,000 deductible on collision and comprehensive, your premium will be lower, which might keep you under the 10 percent threshold. Conversely, if you have a low deductible, your premium will be higher, pushing you over the limit faster. The rule is a starting point for a conversation with yourself about what you are truly getting for your money. For a deeper dive into how different coverage types interact, you can explore resources on new auto insurance options and consumer guides. This site provides independent educational content to help you understand the nuances of various policies, which is especially useful when you are trying to compare the value of full coverage against a liability-only policy.
When Dropping Collision and Comprehensive Makes Sense
Deciding to drop collision and comprehensive coverage is a personal finance decision that goes beyond a simple percentage. It makes the most sense when several factors align. First, as mentioned, the cost of the coverage is high relative to the car's value. Second, you have a comfortable emergency fund that could cover the cost of replacing your car or paying for a major repair out of pocket. If you can afford to absorb a $3,000 loss without derailing your financial life, self-insuring is a reasonable strategy. Third, you are not relying on the car for essential, high-stakes daily transportation that you cannot easily replace. If the car is a second vehicle or used primarily for short, local errands, the risk of a catastrophic loss is lower.
Additionally, consider your deductible. If you have a $1,000 or $2,000 deductible, the most you can get from a collision claim is the car's value minus that deductible. If your car is worth $4,000 and your deductible is $1,000, the maximum payout is $3,000. If you are paying $500 a year for that coverage, you are paying a significant amount for a relatively small potential benefit. In these scenarios, dropping the coverage and redirecting that premium into a savings account earmarked for car repairs or a future down payment can be a more efficient use of your money.
However, there are situations where keeping full coverage is still prudent. If you have a loan or lease on the vehicle, your lender will almost certainly require collision and comprehensive coverage, regardless of the car's age or mileage. If you live in an area with high rates of theft or severe weather, comprehensive coverage might still be valuable even for an older car, as it protects against non-collision events like hail, flood, or vandalism. Finally, if you absolutely depend on your car for your livelihood and could not function without it, the peace of mind that comes with full coverage might be worth the cost, even if the math says otherwise.
Liability-Only Coverage and the Risks You Assume
Switching to a liability-only policy is the most common way to save money on car insurance for drivers with older high mileage vehicles. Liability coverage pays for injuries or property damage you cause to others in an accident. It is required by law in most states, with minimum limits that vary widely. By dropping collision and comprehensive, you are agreeing that if you crash your own car, the insurance company will not pay to fix it or replace it. You are on the hook for those costs.
The risk is obvious: a single at-fault accident could result in a total loss of your vehicle with no financial compensation from the insurer. You would then need to find the money to buy a replacement car. For many drivers with older cars, this is an acceptable risk because the replacement cost is low. However, it is crucial to understand the other risks as well. If you are hit by an uninsured or underinsured driver, your own collision coverage would normally pay for your car's damage (minus deductible). Without it, you may have to rely on your uninsured motorist property damage coverage, if your state offers it and you purchased it, or you may have to pursue the other driver in court, which is often impractical.
To mitigate some of these risks, you can consider keeping comprehensive coverage but dropping collision. Comprehensive is often cheaper and covers theft, fire, vandalism, and weather-related damage, which are risks you cannot control. Collision covers damage from hitting another object or vehicle, which is more directly tied to your driving behavior. Dropping only collision can be a middle-ground solution. It is also wise to increase your emergency fund to cover the value of your car. The money you save each month by not paying for full coverage can be automatically transferred to a high-yield savings account. Over a year or two, you can build a repair or replacement fund that effectively serves as your own insurance policy.
How to Compare Quotes for Older Vehicles
When you decide to shop around for a new policy or adjust your existing one, the process for an older, high mileage vehicle is slightly different than for a new car. Insurers will ask for your vehicle identification number (VIN), mileage, and often your driving history. Because the value of the car is low, some insurers may not even offer collision and comprehensive coverage, or they may offer it at a rate that makes it clearly not worth it. Your goal is to find the best combination of required liability coverage and any optional coverages that still make sense for your situation.
Start by gathering your current policy declarations page and your vehicle's estimated value. Then, use a comparison platform to get quotes from multiple carriers. When you request quotes, be specific about the coverage limits you want. Do not just ask for the minimum; ask for a few different scenarios, such as state minimum liability, higher liability limits, and a quote with and without collision/comprehensive. This will give you a clear picture of the cost of each coverage component. For drivers who tow trailers or boats, specialized coverage may be needed, and you can find guidance in our article on car insurance for drivers who tow trailers or boats.
Here is a step-by-step framework for comparing quotes for your older vehicle:
- Determine your car's actual cash value. Use online valuation tools and local listings to get a realistic private-party value. Subtract your deductible from this amount to find the maximum possible payout from a total loss claim.
- Get your current premium breakdown. Look at your declarations page to see exactly how much you pay for liability, collision, and comprehensive separately.
- Apply the 10 percent rule. Calculate if your collision and comprehensive premiums exceed 10 percent of the car's value. If they do, strongly consider dropping those coverages.
- Request quotes for multiple scenarios. Use a free quote comparison service to get quotes for liability-only, liability plus comprehensive, and full coverage. Compare the prices side-by-side.
- Factor in discounts. Ask about discounts for safe driving, low mileage, or bundling with other policies. Even with an older car, you may qualify for savings that make a particular insurer more competitive.
After you have your quotes, do not just pick the cheapest one. Check the financial strength ratings of the insurers and look at their claims satisfaction scores. A low premium is worthless if the company is difficult to deal with when you have a claim. Also, remember that you can often adjust your deductible to lower your premium. If you have a $500 deductible and a car worth $3,000, raising it to $1,000 might save you 15 to 30 percent on your collision and comprehensive premiums, and you are only increasing your out-of-pocket risk by $500, which you should have in your emergency fund anyway.
Maximizing Savings Without Sacrificing Protection
There are several other strategies to reduce your car insurance costs for an older, high mileage vehicle beyond just dropping coverages. One of the most effective is to improve your credit score if you live in a state that allows insurers to use credit-based insurance scores. A better score can significantly lower your premiums across all coverages. Another is to take a defensive driving course; many insurers offer discounts for drivers who complete an approved course, and this can be especially beneficial for older drivers. You can also ask about discounts for having multiple vehicles on the policy, being a homeowner, or having a clean driving record.
It is also worth reviewing your policy annually. As your car continues to depreciate, the value of your collision and comprehensive coverage decreases. You may find that a coverage that made sense last year no longer does. Set a reminder to reassess your policy every time you renew. If you have paid off your car and no longer have a lender requiring full coverage, that is another trigger to reevaluate. The goal is to pay for the protection you need and not a dollar more. By understanding how insurers calculate risk, applying the 10 percent rule, and shopping around strategically, you can keep your older high mileage vehicle on the road without overspending on insurance.
Finally, consider the role of telematics or usage-based insurance programs. Some insurers offer programs where you plug a device into your car or use a smartphone app to monitor your driving habits. If you are a safe driver who does not drive many miles, these programs can lead to substantial discounts, even for older vehicles. Since high mileage often correlates with more time on the road, if you are actually driving less now, you might be overpaying. Ask your insurer or a comparison service if these programs are available and if they could benefit you.
In the end, car insurance for drivers with older high mileage vehicles is about making informed trade-offs. You can save money by accepting more risk, but you must be prepared for the consequences. By using the tools and rules of thumb outlined here, you can make a confident decision that aligns with your budget and your comfort level. Whether you choose to keep full coverage for peace of mind or switch to liability-only to save money, the key is to be intentional and to review your choice regularly as your car and your life change.