Car Insurance for Remote Workers Who Drive Less: Save Big
Remote work means fewer miles, and car insurance for remote workers who drive less can lower your premium. Call (833)-275-7533 to compare quotes and save.
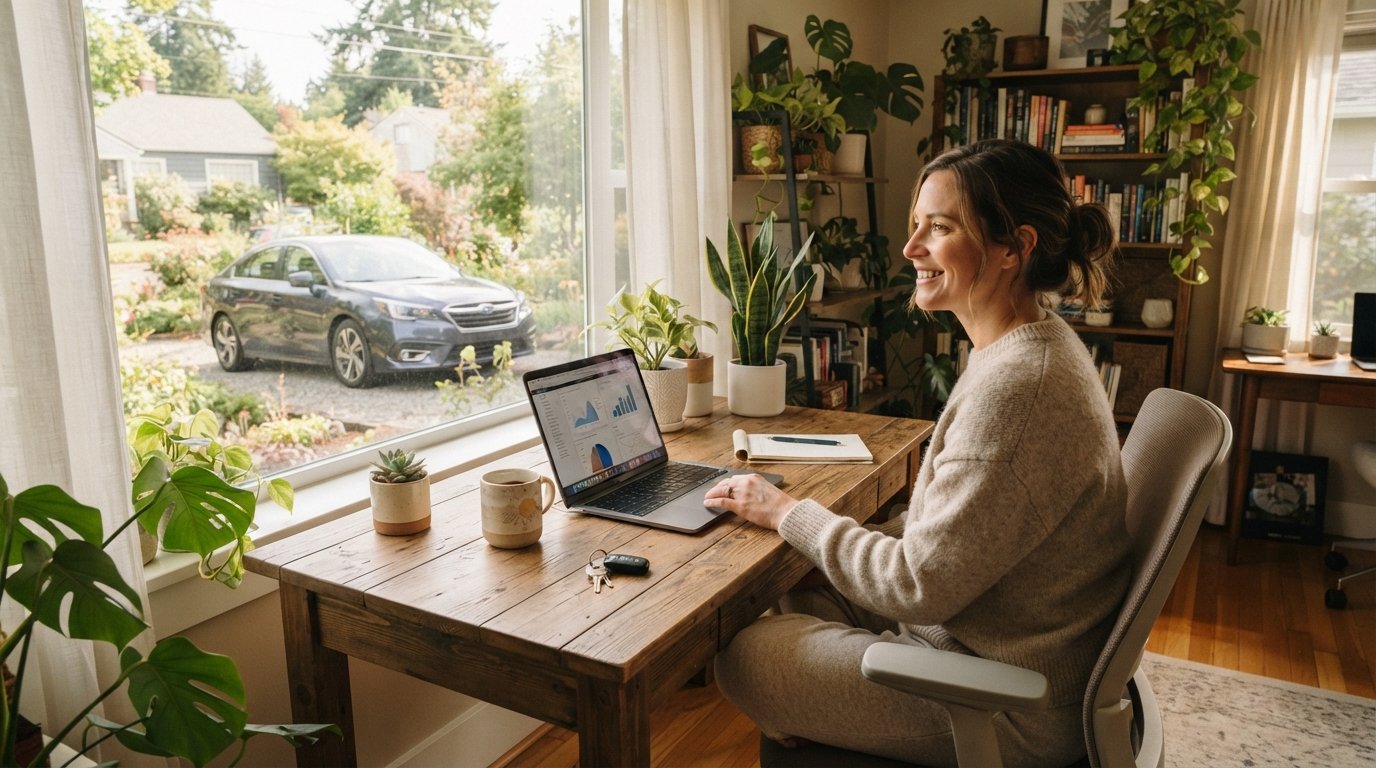
If you traded your daily commute for a home office, you are not alone. Millions of Americans now work remotely at least part of the time, and that shift has a direct impact on how much they drive. Fewer miles behind the wheel often means you are overpaying for car insurance, especially if your policy still reflects a lengthy daily commute. The good news is that insurers recognize this change, and there are concrete steps you can take to align your coverage with your new driving habits. This guide explains how car insurance for remote workers who drive less actually works, what to ask your insurer, and how to capture savings without sacrificing protection.
Why Your Mileage Matters More Than You Think
Auto insurance premiums are built on risk. The more time you spend on the road, the greater the statistical chance of an accident, theft, or claim. Insurers use annual mileage as a core rating factor, even if you have a spotless driving record. When you applied for your current policy, you likely reported a commute of 10, 20, or even 30 miles each way. That translated into an annual mileage estimate of 12,000 to 15,000 miles or more. If you now work from home and only drive for errands, appointments, and occasional outings, your actual mileage might be half that or less.
Reporting a lower annual mileage can lower your premium because it reduces the insurer's exposure. Some companies offer specific low-mileage discounts, while others simply adjust your rate tier. The key is to be accurate: underreporting mileage to get a discount can backfire if you file a claim and the insurer discovers a discrepancy. The goal is to match your policy to your real driving pattern, not to game the system.
How Insurers Rate Annual Mileage
Most carriers group drivers into mileage bands, such as under 5,000 miles, 5,000 to 7,500 miles, 7,500 to 10,000 miles, and so on. These bands help actuaries predict risk without tracking every mile. When you request a quote or update your policy, you will be asked for your estimated annual mileage. Some insurers also ask for a breakdown of business versus personal use, and whether the vehicle is used for rideshare or delivery. Remote workers typically fall into the personal use category with lower annual miles.
If you are unsure of your mileage, take a week and log your trips, then multiply by 52. Or check your odometer at the start and end of a month and extrapolate. Accuracy here is your friend: a realistic estimate prevents surprises at renewal and ensures you are not paying for miles you never drive.
Low-Mileage and Pay-Per-Mile Options to Ask About
Not all insurers advertise low-mileage programs, but many offer them. When you shop for car insurance for remote workers who drive less, ask specifically about these options. Here are the most common programs worth exploring:
- Low-mileage discount: A percentage discount applied when you report annual mileage below a certain threshold, often 7,500 or 10,000 miles.
- Pay-per-mile insurance: You pay a base rate plus a per-mile charge, tracked through a mobile app or plug-in device. This can be ideal if you drive very little and want precise control over costs.
- Usage-based insurance (UBI): A program that monitors driving habits, including mileage, braking, and time of day, and adjusts your rate at renewal based on your score.
- Storage or pleasure-only coverage: If you rarely drive and the car is parked most of the time, some insurers offer reduced coverage for low-use vehicles, though restrictions apply.
Each option has trade-offs. Pay-per-mile programs can be very cheap for low-mileage drivers but may not suit those who take occasional long road trips. Usage-based programs require sharing driving data, which some people prefer to avoid. Low-mileage discounts are simpler but may be smaller. Compare quotes from multiple carriers to see which structure fits your life and budget.
What Documentation Insurers May Request
When you report a lower annual mileage, some insurers will take your word for it, especially at the quote stage. Others may ask for proof, particularly if the mileage reduction is significant or if you are claiming a low-mileage discount. Common documentation requests include:
- A recent oil change receipt or service record showing the odometer reading.
- A photo of your odometer.
- A signed mileage verification form.
- Telematics data if you are enrolled in a usage-based program.
Having these items ready can speed up the process. If you are switching insurers, the new carrier may verify your mileage with your previous insurer or through public records. Honesty is always the best policy: if you misrepresent your mileage and later file a claim, the insurer could adjust your payout or cancel your policy.
When to Revisit Coverage Limits After a Commute Disappears
Dropping your commute does not automatically mean you should drop coverage. In fact, some remote workers make the mistake of reducing liability limits to save money, only to find themselves underinsured if they cause a serious accident. The right approach is to reassess your entire policy, not just mileage. Consider these factors:
- Liability limits: Even if you drive less, a single accident can result in significant medical bills and property damage. Keep limits high enough to protect your assets. Many experts recommend at least 100/300/100, meaning $100,000 per person, $300,000 per accident, and $100,000 for property damage.
- Comprehensive and collision deductibles: If your car is parked most of the day, comprehensive coverage (which pays for theft, vandalism, and weather damage) may be more valuable than collision. You might raise your collision deductible to lower your premium, but keep comprehensive if your car is exposed to risk.
- Uninsured/underinsured motorist coverage: This protects you if you are hit by a driver with little or no insurance. It is worth keeping regardless of your mileage.
- Medical payments or personal injury protection (PIP): If you have health insurance, you may be able to reduce this coverage, but check your health plan's limits and deductibles first.
Review your policy annually or after any major life change, such as a new job, a move, or a change in household drivers. A quick call to your insurer can reveal savings you did not know existed.
How to Shop for Car Insurance as a Remote Worker
Comparing quotes is the most reliable way to find the best rate for your new driving habits. Start by gathering your current policy details, including coverage limits and deductibles, so you can make apples-to-apples comparisons. Then, request quotes from multiple carriers. Be sure to mention that you work from home and drive less than before; some insurers have specific questions about remote work that can unlock discounts.
Online comparison tools can streamline the process. For example, Free Auto Insurance Quotes Online lets you request quotes from multiple carriers in one place, with no obligation to buy. You can also ask about discounts for low mileage, safe driving, and vehicle safety features. Do not overlook the value of bundling auto with home or renters insurance, which often yields a multi-policy discount.
If you are also considering refinancing your auto loan to lower your monthly payments, resources like Car Loan Refinancing offer educational guides and rate comparisons that can help you evaluate your options. Lowering your car payment can free up room in your budget for adequate insurance coverage.
Avoiding Common Pitfalls
Remote workers who drive less sometimes make costly mistakes when adjusting their insurance. One common error is canceling coverage entirely because the car sits in the driveway. In most states, you must maintain continuous insurance as long as you own a registered vehicle, even if you rarely drive it. Lapses in coverage can lead to fines, license suspension, and higher rates when you reinstate. Another pitfall is dropping uninsured motorist coverage to save a few dollars. Given that roughly one in eight drivers is uninsured, according to the Insurance Research Council, this coverage is well worth keeping.
Finally, do not assume your insurer will automatically adjust your rate when you stop commuting. You must proactively notify them of the change. Set a reminder to review your policy every six to twelve months, or whenever your driving habits shift. A five-minute phone call could save you hundreds of dollars a year.
Frequently Asked Questions
Will my rate go up if I report lower mileage?
No, lower mileage typically reduces your premium because it lowers the insurer's risk. However, if you previously had a low-mileage discount and your mileage increases, your rate could go up. Always report changes accurately.
Can I get a refund if I already paid for a year of coverage?
Possibly. If you update your policy mid-term and your premium decreases, most insurers will prorate the difference and either refund it or apply it to future payments. Ask your agent for details.
Do I need special coverage if I use my car for business occasionally?
If you occasionally use your personal vehicle for work errands, your personal policy may not cover business use. Ask your insurer about a business-use endorsement or a commercial policy if your employer does not provide coverage.
How does pay-per-mile insurance work?
You pay a base daily or monthly rate plus a few cents per mile driven. Mileage is tracked via a smartphone app or a device plugged into your car's diagnostic port. It can be a good fit for very low-mileage drivers, but read the fine print about data privacy and program availability in your state.
Understanding the nuances of car insurance for remote workers who drive less is the first step toward savings. By aligning your policy with your actual mileage, asking about low-mileage programs, and reviewing your coverage limits, you can protect yourself without overpaying. For a seamless comparison experience, visit Free Auto Insurance Quotes Online to request free, no-obligation quotes from multiple carriers today. If you are also exploring options to refinance your auto loan, the 2026 rental car insurance coverage updates guide may offer useful context on how coverage interacts with rentals, which can be handy for occasional trips.