Car Insurance for Retired Drivers Who No Longer Commute
Lower your car insurance for retired drivers who no longer commute. Call (833)-275-7533 to compare quotes and uncover savings.
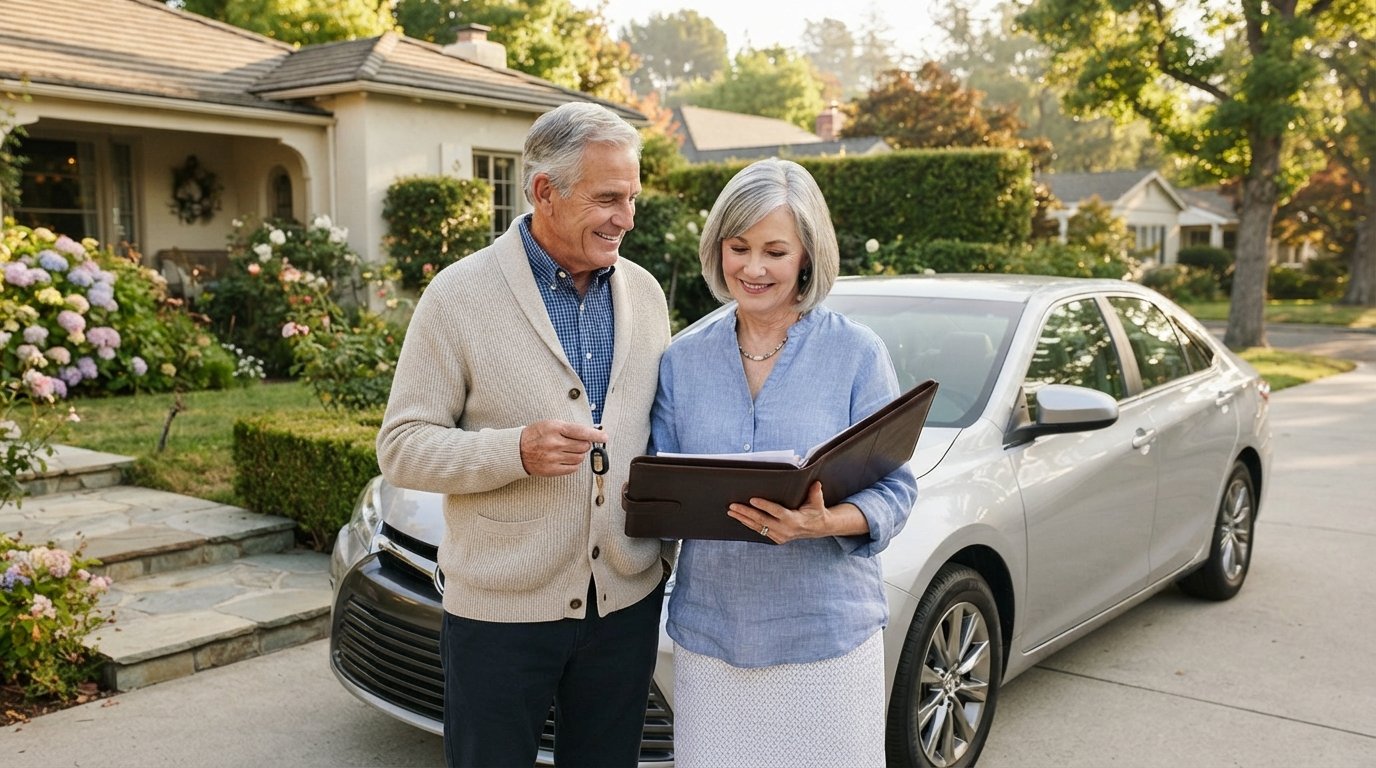
Retirement changes more than your daily schedule. It also changes how, when, and how far you drive. If you no longer commute to work, your annual mileage may drop by thousands of miles, and that shift can have a real impact on your car insurance premiums. Many retirees keep paying for coverage based on an outdated driving profile, which means they may be leaving money on the table. Understanding how car insurance for retired drivers who no longer commute works can help you align your policy with your new lifestyle and keep more of your retirement budget in your pocket.
Why Lower Mileage After Retirement Matters for Your Premium
Insurance companies price risk based on how likely you are to file a claim. When you commute daily, you spend more time on the road during peak hours, increasing your exposure to accidents. After you retire, your driving patterns typically shift to shorter trips, off-peak hours, and fewer overall miles. That reduced exposure often translates into lower risk in the eyes of an insurer.
However, your insurer may not automatically know that you stopped commuting. Unless you tell them, they may still have you classified as a daily commuter with a higher annual mileage estimate. That outdated classification can keep your premium artificially high. Requesting a rate review and updating your mileage is one of the simplest steps you can take to potentially lower your car insurance costs as a retiree.
Many carriers use mileage bands (for example, under 5,000 miles per year, 5,000 to 10,000, and so on) to help determine rates. If your retirement driving falls into a lower band, you may qualify for a lower rate. Some companies also offer low-mileage discounts or usage-based programs that reward you for driving less. It is worth asking your agent whether your policy reflects your current odometer readings and driving habits.
Retiree and Mature Driver Discounts You May Be Missing
Beyond mileage, retirees often qualify for discounts that are specifically designed for mature drivers. These discounts vary by insurer and state, but they can add up. Here are some common opportunities to explore:
- Mature driver safety course discount: Many states require insurers to offer a discount to drivers who complete an approved defensive driving or mature driver course. These courses are often available online and can be completed in a few hours.
- Retiree or occupation-based discounts: Some carriers offer discounts for retirees or for certain professions. Even if you are no longer working, your former occupation or membership in a retiree organization may qualify you for savings.
- Low-mileage discount: If you drive significantly less than the average driver, you may qualify for a low-mileage discount or a usage-based insurance program that monitors your actual driving.
- Multi-policy and multi-vehicle discounts: Bundling auto and home insurance, or insuring multiple vehicles, can often reduce your overall premium.
- Safety feature discounts: Vehicles equipped with airbags, anti-lock brakes, and anti-theft devices may qualify for additional discounts.
It is important to ask your insurer or a licensed agent about every discount you might qualify for. Discounts are not always applied automatically, and a quick conversation can reveal savings you did not know existed. When comparing car insurance for retired drivers who no longer commute, make sure you are comparing quotes that include all applicable discounts so you get an accurate picture.
Should You Keep a Second Vehicle Insured After Retirement?
Many retirees downsize to one vehicle after they stop commuting. If you have a second car that is rarely driven, you may be able to reduce costs by adjusting its coverage. However, simply dropping insurance entirely can be risky. If you still drive the vehicle occasionally, you need at least the state minimum liability coverage. If you let the policy lapse, you may face penalties, and you could lose a continuous coverage discount that many insurers offer.
One option is to keep liability coverage on the second vehicle but drop collision and comprehensive if the car is older and not worth much. Another option is to explore a low-mileage or storage policy if the vehicle is truly not being driven. Some insurers offer reduced rates for vehicles that are stored or driven only seasonally. Before making changes, consider how often you actually use the second car and what it would cost to replace it. A licensed agent can help you weigh the trade-offs and find a coverage level that fits your budget and your risk tolerance.
Coverage Adjustments for Snowbirds and Seasonal Residents
If you split your time between two states, your car insurance needs may be more complex. Snowbirds often face questions about where to register their vehicle, which state's insurance requirements apply, and how to keep coverage active while they are away. Generally, you should insure your vehicle in the state where it is primarily garaged. If you spend six months in one state and six months in another, the rules can vary, and it is important to confirm with your insurer.
Seasonal residents may be able to adjust their coverage when the vehicle is not in use. For example, if you store your car during the months you are away, you might qualify for a reduced rate or a storage policy. However, you should never cancel insurance entirely unless you also surrender your plates and registration, as penalties for lapses can be significant. When you return, you will need to reinstate coverage before driving. Working with an agent who understands multi-state insurance can help you avoid gaps and ensure you are compliant in both states.
How to Request a Rate Review and Compare New Quotes
Taking control of your car insurance costs as a retiree starts with a simple conversation. Follow these steps to review your current policy and see if you can save:
- Gather your current policy and mileage information: Note your annual mileage, the vehicles you drive, and the coverage types and limits you currently have.
- Call your insurer to request a rate review: Explain that you have retired and your driving habits have changed. Ask them to update your mileage and check for any discounts you may now qualify for.
- Compare quotes from multiple carriers: Rates vary widely between insurers, so getting quotes from several companies can help you find the best deal. You can start by getting free auto insurance quotes online from a comparison platform that connects you with licensed agents.
- Review coverage options: Consider whether you still need the same coverage levels. For example, if your car is older, you might drop collision and comprehensive to save money, but make sure you understand the risks.
- Ask about usage-based programs: If you drive very little, a pay-per-mile or usage-based policy could save you money. For a deeper look at how these programs work, see our guide on pay per mile car insurance.
After you have gathered quotes, compare them side by side, looking at both price and coverage. A lower premium is not always the best deal if it leaves you underinsured. Take the time to understand what each policy covers and choose the one that balances cost and protection.
Other Ways Retirees Can Save on Car Insurance
Beyond mileage and discounts, there are other strategies retirees can use to lower their car insurance costs. Maintaining a clean driving record is one of the most effective ways to keep premiums low. Taking a defensive driving course can refresh your skills and may qualify you for a discount. Improving your credit score can also help, as many insurers use credit-based insurance scores in pricing (except in states where it is prohibited).
If you are financing a vehicle, refinancing your auto loan could reduce your monthly expenses and free up room in your budget for insurance or other needs. For retirees with an existing car loan, exploring car loan refinancing options may help lower your interest rate or monthly payment. While this does not directly affect your insurance premium, it can improve your overall financial picture in retirement.
Finally, consider raising your deductible if you have savings to cover it. A higher deductible typically lowers your premium, but make sure you are comfortable with the out-of-pocket cost if you need to file a claim. As with any coverage change, weigh the savings against the potential risk.
Frequently Asked Questions About Car Insurance for Retired Drivers
Will my car insurance go down when I retire?
It can, but not automatically. If you update your mileage and driving status with your insurer, you may qualify for lower rates or discounts. Requesting a rate review is the best way to find out.
Do I need to tell my insurer that I retired?
Yes, it is a good idea. Your insurer may still have you classified as a commuter, which could mean you are paying more than necessary. Updating your status can trigger a rate adjustment.
Can I drop collision and comprehensive coverage on an older car?
You can, but consider the value of the vehicle and your ability to replace it. If the car is worth little, dropping these coverages may save money, but you will not be reimbursed for damage to your own vehicle.
What if I only drive seasonally?
You may qualify for a storage policy or reduced coverage during months when the vehicle is not in use. However, never cancel insurance entirely without surrendering your plates, as penalties can apply.
How can I compare car insurance quotes for retired drivers?
You can use an online comparison platform to get free quotes from multiple carriers. Make sure to provide accurate mileage and driving information so the quotes reflect your retired lifestyle.
Retirement is a time to enjoy life, not to overpay for car insurance. By understanding how your changed driving habits affect your premium, asking for discounts, and comparing quotes, you can make sure your policy fits your new routine. Take a few minutes today to review your coverage and see if you can free up money for the things that matter most.