When to Shop for New Car Insurance (Not Just at Renewal)
Knowing when to shop for new car insurance instead of waiting for renewal can save you money. Call (833)-275-7533 for expert help today.
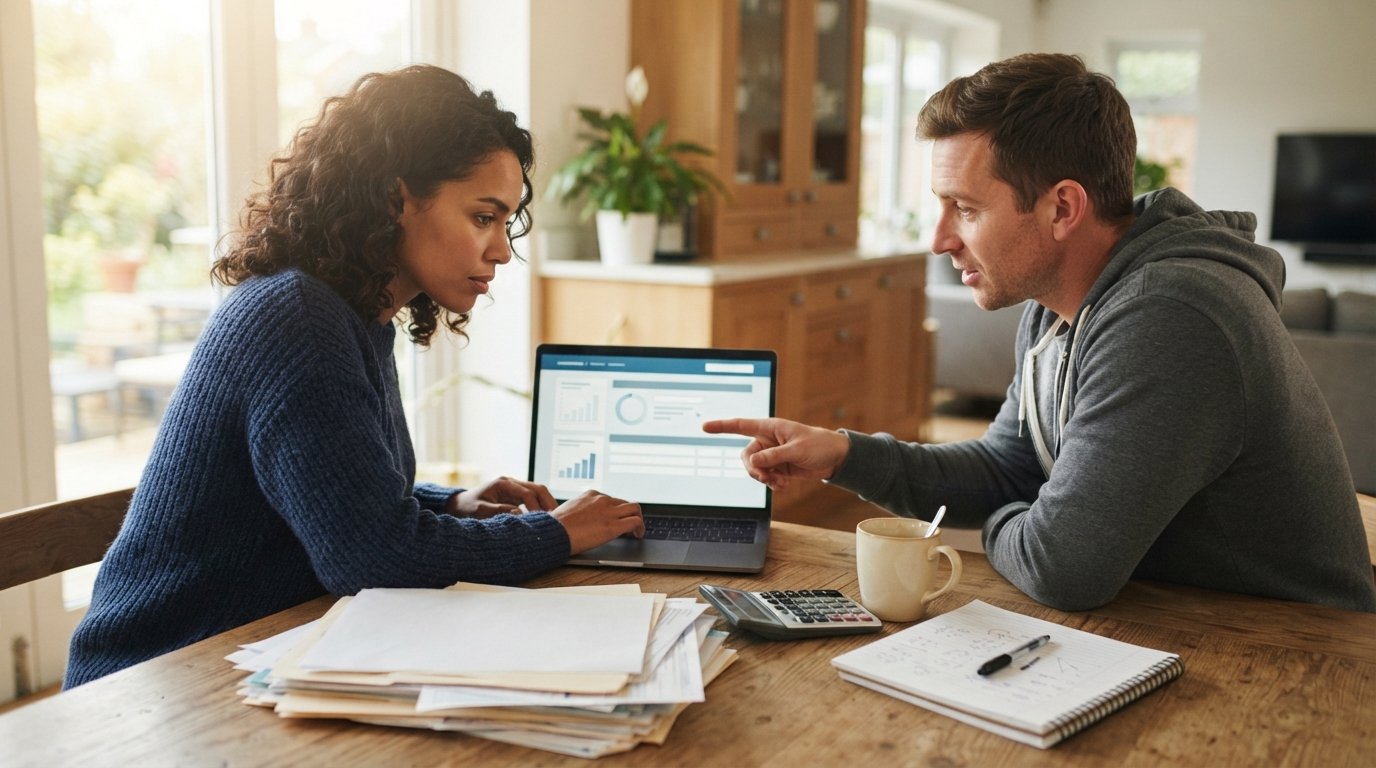
Your auto insurance renewal notice arrives, and you glance at the new premium. It is higher than last year, but you figure that is normal and pay it. Months later, you mention the increase to a friend who pays hundreds less for similar coverage. That scenario plays out for millions of drivers every year, and it happens because most people only think about car insurance when the bill comes due. The truth is that the best time to shop for new car insurance is not always at renewal. Certain life events, rate changes, and policy shifts create windows of opportunity where comparing quotes can save you real money, sometimes immediately. Waiting for renewal out of habit can cost you hundreds of dollars in unnecessary premiums. This guide explains exactly when to shop for new car insurance instead of waiting for renewal, how to compare offers mid-term without triggering penalties, and what documents you need to make the switch smoothly.
Why Renewal Is Not the Only Time to Compare Rates
Insurance companies price policies based on risk, and your risk profile changes throughout the year. When you bought your policy, the insurer assessed your driving record, credit score, location, vehicle, and other factors. If any of those factors shift, your current premium may no longer reflect the best available rate. Waiting until renewal means you could spend months overpaying before the insurer recalculates your rate. In a competitive market, carriers constantly adjust their pricing models, and a company that was cheapest for you last year may no longer be the most affordable option today.
Many drivers assume that switching mid-term is complicated or expensive. In reality, most states allow you to cancel your policy at any time, and you are typically entitled to a prorated refund for unused coverage. The key is to shop strategically, compare quotes before canceling, and time the switch to avoid any gaps. Understanding these mechanics puts you in control and ensures you never pay more than necessary for the coverage you need.
Life Triggers That Justify Re-Shopping Immediately
Certain events materially change your insurance needs or your risk profile. When these happen, waiting for renewal can be a costly mistake. Here are the most common triggers that should prompt you to compare quotes right away.
- Moving to a new address or state: Premiums are heavily influenced by location. A move, even within the same city, can change your rate class. If you move to a state with different minimum coverage requirements, your current policy may not even be compliant.
- Buying a new car: A new vehicle changes the value being insured and may come with safety features that qualify for discounts. Your current insurer might not offer the most competitive rate for that specific model.
- Adding a teen driver: Teen drivers are statistically riskier, and adding one to your policy can spike your premium. Shopping around before the addition goes into effect can reveal carriers that specialize in families with young drivers.
- A rate hike or renewal increase: If your premium jumps by more than 10 percent without a clear reason (like an at-fault accident), it is a signal to compare. Insurers sometimes raise rates across entire regions or risk classes, and a competitor may not have followed suit.
- Changes in driving habits: If you start working from home, reduce your annual mileage, or retire, your risk profile improves. Some carriers offer low-mileage discounts that your current policy may not reflect until renewal.
In each of these cases, the potential savings from switching often outweigh any inconvenience. The earlier you act, the sooner you lock in a better rate and stop overpaying.
How to Compare Quotes Mid-Term Without Canceling Early
The safest way to explore your options is to gather quotes while your current policy remains active. You do not need to cancel anything to see what other carriers would charge. Start by collecting the following documents: your current declarations page (showing coverage limits and deductibles), your driver's license, vehicle registration, and a recent payment statement. With these in hand, you can request quotes online or through an independent agent.
When you receive quotes, compare them apples to apples. Look beyond the monthly premium and check the coverage limits, deductibles, and any add-ons. A cheaper premium might come with lower liability limits, which could leave you underinsured. Also ask about mid-term cancellation fees. Some carriers charge a fee if you cancel before the policy period ends, though many do not. Factor that fee into your savings calculation. If the new policy saves you $300 over six months but carries a $50 cancellation fee, you still come out ahead.
Once you have a competitive quote, you can time the switch. You are not required to cancel your old policy until the new one is ready to take effect. Arrange for the new coverage to start on the same day the old one ends, and then cancel the old policy. This approach eliminates any gap in coverage, which is critical because even a one-day lapse can trigger higher rates or legal penalties.
Avoiding Cancellation Fees and Coverage Gaps During a Switch
Coverage gaps are the biggest risk when switching insurers. If your old policy cancels before the new one activates, you are driving uninsured, even if only for a few hours. Most states require continuous coverage, and insurers report lapses to databases that other carriers check. A gap can lead to higher premiums, non-renewal, or even license suspension in some states. To avoid this, always set the new policy's effective date to match or precede the old policy's cancellation date. Confirm in writing that the new carrier has bound coverage before you call to cancel the old one.
Cancellation fees are less common but still worth checking. Some insurers charge a short-rate cancellation penalty, meaning they keep a portion of the unearned premium as a fee. Others charge a flat fee. Review your current policy's cancellation clause or ask your agent. If a fee applies, calculate whether the savings from switching still justify the cost. In most cases, the answer is yes, especially if you are switching due to a rate hike or a life change that your current insurer does not accommodate well.
Documents to Gather Before Requesting New Quotes
Having the right information ready speeds up the quoting process and ensures accuracy. Before you start comparing, collect these items:
- Your current auto insurance declarations page, which shows policy limits, deductibles, and coverage types.
- Driver's license numbers for all household members who will be on the policy.
- Vehicle identification numbers (VINs) and estimated annual mileage for each vehicle.
- Your home address and the address where the vehicles are garaged, if different.
- A recent payment statement or proof of continuous coverage, which some carriers use to qualify you for discounts.
With these documents, you can get accurate quotes quickly. If you have a poor credit history or a high-risk driving record, be prepared to provide additional details. In our guide on car insurance after bankruptcy filing: rates and coverage, we explain how to navigate the quoting process when your record is less than perfect. The same principles apply: transparency and preparation help you find the best available rate.
When Waiting for Renewal Actually Makes Sense
While there are many good reasons to shop mid-term, there are also situations where waiting for renewal is the smarter move. If your policy is set to renew in a few weeks and you have no pressing life changes, it may be simpler to compare at that point. Renewal is a natural checkpoint, and some carriers offer loyalty discounts or renewal credits that you would forfeit by canceling early. Additionally, if you recently filed a claim that is still open, switching mid-claim can complicate the process. In those cases, waiting until the claim is resolved and the renewal date approaches is often the least disruptive path.
Another consideration is your state's rules on mid-term cancellations. A few states have specific notice requirements or restrictions, so check your local regulations. However, for most drivers, the flexibility to switch at any time is a key advantage of the competitive insurance market. The bottom line is that you should never feel locked in. If a better offer exists, you have the right to pursue it, and the savings can be substantial.
Step-by-Step: How to Shop Mid-Term and Switch Smoothly
If you have decided that now is the time to compare, follow this sequence to protect yourself and maximize savings.
- Gather your documents (declarations page, license, VIN, mileage).
- Request quotes from at least three carriers, including your current insurer's competitors.
- Compare coverage limits, deductibles, and premiums side by side.
- Check for cancellation fees and any loyalty discounts you might lose.
- Select the best offer and bind coverage, setting the effective date to match your old policy's end date.
- Cancel your old policy only after the new one is active, and request a refund of any unused premium.
This process typically takes less than an hour, and the savings can last for the entire policy term. For additional guidance on comparing rates and understanding coverage options, you can explore independent resources like NewAutoInsurance.com, which offers educational articles and FAQs for drivers. However, the most direct way to see your potential savings is to request personalized quotes from multiple carriers.
Final Thoughts: Take Control of Your Insurance Timing
The decision of when to shop for new car insurance instead of waiting for renewal comes down to awareness and action. If your circumstances have changed, if your rate has jumped, or if you simply have not compared in a while, there is no reason to wait. The insurance market is dynamic, and carriers compete for your business. By shopping strategically, you can avoid overpaying and ensure your coverage matches your current needs. Remember to gather your documents, compare quotes without canceling, and time your switch to avoid gaps. With a little effort, you can turn a routine errand into a meaningful savings opportunity.