Auto Insurance for College Students Away From Home
Keep your college student covered without overpaying. Call (833)-275-7533 for auto insurance for college students away from home and compare quotes today.
By Evelin Cross
Your child got into their dream school three states away. You are proud, you are excited, and then a small practical question hits you: what happens to their car insurance? Do you keep them on your family policy, or do they need their own coverage in a new state? The answer depends on a handful of details that most families never think about until a claim, a ticket, or a renewal notice forces the issue. Understanding how auto insurance for college students away from home actually works can save you hundreds of dollars a year and prevent a nasty surprise if your student is ever in an accident.
This guide walks through the real rules insurers use, the discounts your student probably qualifies for, and the exact steps to take when a dorm move or apartment lease changes where the car sleeps at night.
Can a College Student Stay on a Parent's Policy?
In most cases, yes. Insurance companies generally allow a full-time college student to remain on a parent's policy as long as the student is a resident of the parent's household, even if they live in a dorm or an off-campus apartment during the school year. The key phrase insurers use is "resident relative," and full-time student status usually satisfies that definition. This is the single biggest reason families can avoid buying a separate policy while their child is at school.
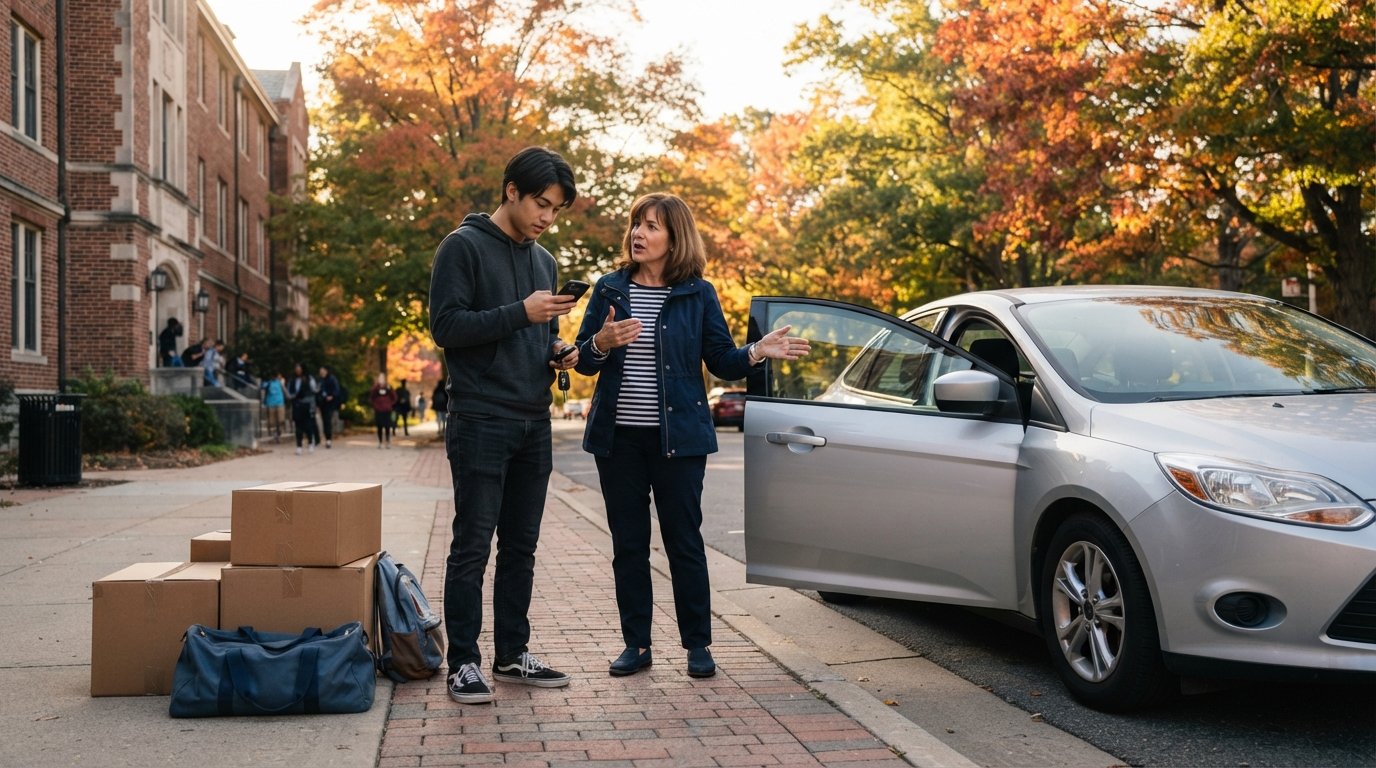
However, the rules change depending on whether the student takes a car with them. If the student leaves the car at home and only uses it during breaks, keeping them listed on the family policy is straightforward. If they take the car to school, the insurer needs to know the new garaging location, because rates are calculated partly on where a vehicle is parked most of the time. A car parked in a rural college town may cost less to insure than one parked in a dense city, but the reverse is also true. Either way, hiding the move is a mistake that can lead to a denied claim.
There are a few situations where a separate policy makes more sense:
- The student is married, financially independent, or no longer claimed as a dependent.
- The student's car is titled in their own name and they pay their own premiums.
- The student moves to a state where your current carrier does not write policies.
- The student's driving record has become so risky that keeping them on the family policy would raise everyone's rates dramatically.
Before assuming anything, call your insurer and ask one direct question: "Does my full-time college student still qualify as a resident relative if they live in a dorm in another state?" The answer will shape everything else.
Good Student and Distant Student Discounts
Insurance companies love students who earn good grades, and they prove it with discounts that can trim premiums by 5 to 25 percent. The most common is the good student discount, which typically requires a GPA of 3.0 or higher, a class rank in the top 20 percent, or placement on the dean's list or honor roll. Documentation is usually a transcript, a report card, or a signed letter from the school registrar. Most insurers require you to resubmit proof every semester or every year, so set a calendar reminder.
The distant student discount is the one families overlook most often. If your student attends school at least 100 miles away from home (some carriers use 150 miles) and does not take a car with them, many insurers will reduce or even remove the cost of having that student on the policy. The logic is simple: a student who only drives during winter break and summer is a much lower risk than one who drives daily. You still keep them listed for coverage when they are home, but you stop paying the full rate for a car they are not using.
To claim this discount, be ready to provide:
- Proof of full-time enrollment (a tuition bill or class schedule usually works).
- The school's address and distance from your home.
- A written statement that the student does not have a vehicle at school.
- Updated documentation each time the student's status changes, such as moving off campus or bringing a car mid-year.
Stacking these two discounts is often possible, and the combined savings can be substantial. A student with a 3.5 GPA who lives 200 miles away and leaves the car at home might see the family's premium drop by a few hundred dollars a year.
How Garaging Location Changes Rates
Every insurer cares about where a vehicle is parked overnight, because that is where most thefts and many collisions happen. When a student takes a car to school, the garaging address on the policy must change to the dorm, apartment, or campus parking lot. This is not optional paperwork; it is a material fact that affects both the premium and the insurer's willingness to pay a claim.
Rates can move in either direction. A student moving from a large metro area to a small college town may see a decrease, because theft and accident rates are typically lower. A student moving from a suburb to a dense urban campus may see an increase, sometimes a significant one, because of higher traffic density, parking-related damage, and theft risk. Some carriers also apply a surcharge if the campus is in a state with different minimum liability requirements than your home state.
Here is where families get into trouble. If the student takes the car but the policy still lists the home address, the insurer can argue that it was charged the wrong premium and either deny a claim or charge backdated premium. That outcome is far worse than a modest rate increase. The fix is a quick phone call or online update to report the new garaging address as soon as the student arrives on campus. If you want to see how rates shift by location before you commit, running side-by-side quotes is the smartest first step. Our guide on auto insurance quotes in Texas explains how to compare rates the smart way, and the same method works in any state.
Steps to Notify Your Insurer When a Student Moves
Moving a student to college is chaotic, but a five-minute insurance update prevents months of headaches. Whether your student is moving into a dorm, a sorority house, or an off-campus apartment, the process is the same. Do it before the first day of classes if possible, and no later than the first week.
Follow these steps in order:
- Call your insurer or log into your account and report the new address where the car will be kept.
- Confirm whether the student still qualifies as a resident relative and whether any discounts need to be re-verified.
- Ask whether the new state has different minimum liability requirements that your current policy does not meet.
- Request written confirmation of the changes, including any premium adjustment, so you have a record.
- Update your student's address with the DMV if they change their driver's license or voter registration.
If the student is moving to a state where your carrier does not operate, you may need a separate policy in that state. In that case, ask your current insurer for a referral or shop for a new policy that meets the new state's minimums. Do not let the student drive on a lapsed or non-compliant policy, even for a few weeks.
When a Separate Policy Makes Sense
Staying on a parent's policy is usually the cheapest option, but it is not always the right one. If your student is financially independent, married, or has a vehicle titled in their own name, a separate policy is often required. A separate policy also makes sense if the student's driving record has deteriorated to the point that keeping them on the family plan would raise everyone's rates, or if the student lives in a state where your carrier does not write coverage.
Before splitting the policy, run the numbers both ways. Sometimes the cost of a separate policy for a young driver is high enough that keeping them on the family plan, even with a rate increase, is still cheaper. Other times, the family plan surcharge is so large that a standalone policy for the student is the better financial move. A licensed agent can quote both scenarios in minutes.
If your student is also managing a car loan, it helps to understand how the loan and the insurance interact. Resources like CarLoanRefinancing explain how refinancing an auto loan can lower monthly payments, which can free up room in the budget for a separate insurance policy if that becomes necessary.
Coverage Gaps to Watch For
The most common gap for college students away from home is a vehicle left at home that is still listed as actively driven by the student. If the student does not have a car at school, tell your insurer. Keeping them listed as a full-time driver when they only drive during breaks can cost you money and, in rare cases, create questions at claim time.
The second gap is a car taken to school but not reported. As covered earlier, this can lead to a denied claim or backdated premium. The third gap is a student who borrows a friend's car or rents a vehicle on a trip. Most family policies extend coverage to a borrowed car, but the limits may be lower than expected. Ask your insurer how coverage applies when your student drives someone else's vehicle.
Finally, watch for state minimum liability differences. If your student moves to a state with higher minimums than your home state, your policy may not satisfy the new state's requirements. In that case, you may need to increase your limits or purchase a separate policy. A quick call to your insurer before the move resolves this in most cases.
Frequently Asked Questions
Does my college student need their own car insurance?
Usually no, as long as they are a full-time student, a resident relative of your household, and you keep them listed on your policy. They need a separate policy if they are financially independent, married, or own the car themselves.
Can I keep my student on my policy if they go to school in another state?
Yes, in most cases. The key is to report the new garaging location and confirm that your carrier writes policies in that state. If it does not, you may need a separate policy.
What is the distant student discount?
It is a discount for students who attend school at least 100 to 150 miles from home and do not take a car with them. It can reduce or remove the cost of having the student on the policy.
What happens if I do not report a move?
Your insurer may deny a claim or charge backdated premium. Always report a change of address as soon as the student moves.
College is expensive enough without overpaying for insurance. Take five minutes to confirm your student's status, claim the discounts they qualify for, and update the garaging address. That small effort can keep your family covered and your budget intact all year.