Auto Insurance for Divorced or Separated Couples
Auto insurance for divorced or separated couples starts with splitting policies cleanly. Call (833)-275-7533 for a free quote and avoid coverage gaps.
By Kieran Maddox
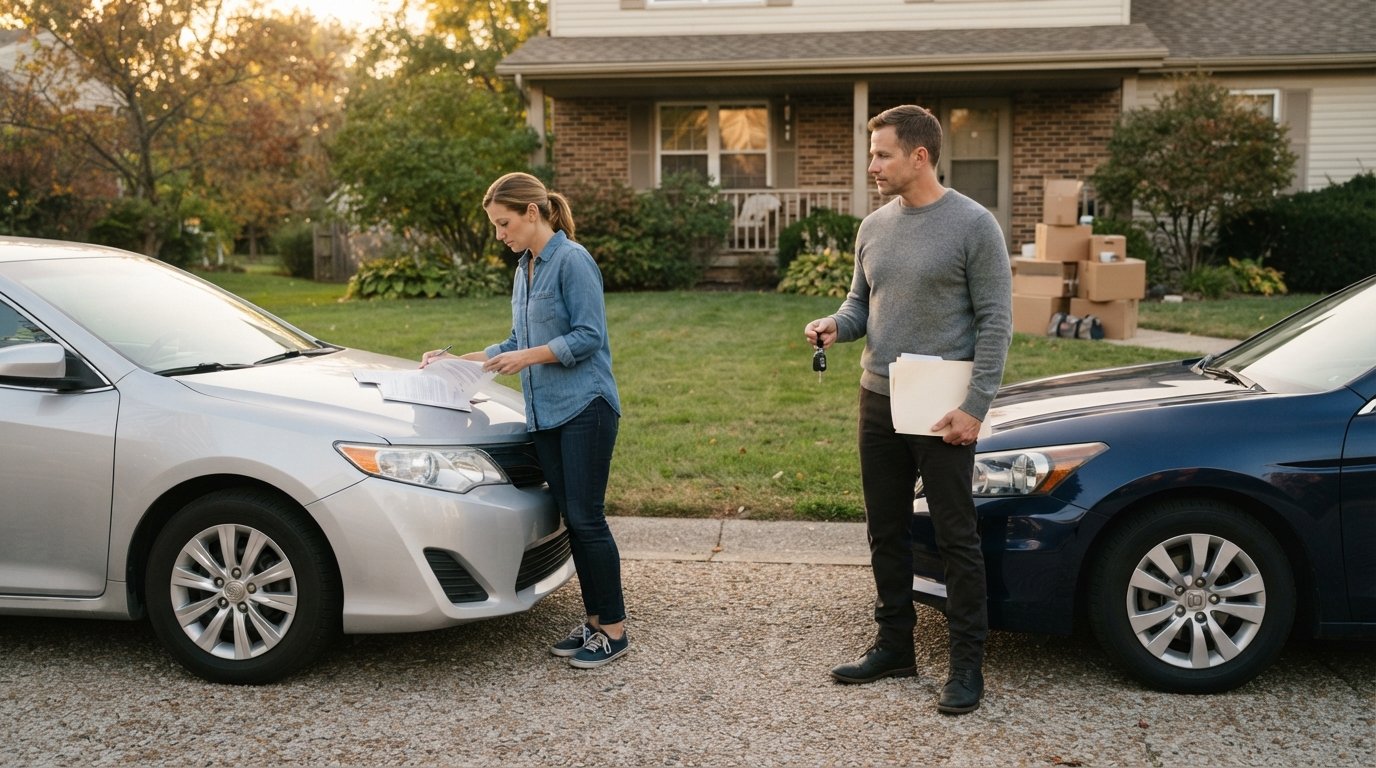
Divorce or separation changes almost every part of your financial life, and your car insurance policy is no exception. Many people do not realize that a marital split can quietly raise their premiums, create coverage gaps, or leave them legally exposed after an accident. Whether you are newly separated, in the middle of divorce proceedings, or finalizing a settlement, understanding how auto insurance for divorced or separated couples works can save you hundreds of dollars and prevent painful surprises. This guide walks you through the practical steps: who stays on the policy, how to split vehicles, when to notify your insurer, and how to compare rates so you land on solid, affordable coverage.
At its core, the issue is simple: most auto policies are built around a household. When that household changes, the policy must change too. Insurers care about who lives at the address, who drives each car, and who carries financial responsibility. If you keep paying on a joint policy after a separation and something goes wrong, the claim process can become a nightmare. The good news is that with a little planning, you can turn a stressful transition into an opportunity to find better rates. Platforms like compare Texas auto insurance quotes show how shopping multiple carriers at once can reveal real savings, and the same approach works in every state.
Why Your Marital Status Matters to Car Insurers
Insurance companies use dozens of rating factors, and marital status is one of them. Statistically, married drivers file fewer claims than single drivers, so many carriers offer lower rates to married couples. When you divorce or separate, you may lose that marital discount, and your premium can rise even if nothing else about your driving changes. That increase is not personal; it is simply how actuarial tables work. Knowing this in advance helps you budget and shop strategically instead of being blindsided by a renewal notice.
Beyond discounts, marital status affects how a policy is structured. A joint policy typically lists both spouses as named insureds, which means either person can file a claim, make changes, or cancel the policy. After a separation, that shared control becomes a problem. One ex-spouse could remove a vehicle, lower coverage limits, or cancel the policy entirely without telling the other. If you are still driving a car listed on that policy, you could suddenly be uninsured without any warning.
There is also the question of liability. If your name is on the title but your ex-spouse causes an accident, a claimant could pursue assets you share or once shared. Separating your insurance is one of the first protective steps you can take after a split, ideally before the divorce is final. The earlier you act, the less risk you carry from a policy you no longer control.
Who Keeps the Joint Policy During Separation?
During a separation, many couples continue sharing a policy because it is convenient or because a divorce decree has not yet divided assets. This can work for a short time, but it requires clear communication. If you keep a joint policy, both drivers should agree in writing on who pays what, which vehicles are covered, and what coverage limits apply. You should also confirm that your insurer knows about the separation, because some companies treat a separated spouse as a separate household for rating purposes.
In some cases, it makes more sense to split policies immediately. If there is any conflict, distrust, or history of missed payments, separate policies remove the risk of one person's actions affecting the other. A lapse caused by an ex-spouse can follow you for years and raise your rates with future insurers. If you are unsure, call your carrier and ask two questions: how would a separation affect my rate, and what happens to my coverage if the other person cancels the policy?
If you are in a state with community property rules, such as Texas or California, divorce can complicate who owns which vehicle and who is responsible for debts tied to it. In those states, it is wise to consult your divorce attorney before making policy changes. Once ownership is clear, splitting the policy is usually the cleanest path forward.
How to Split Vehicles and Policies Step by Step
The mechanics of separating auto insurance are straightforward once you know the order of operations. The goal is to avoid any gap in coverage, because even one day uninsured can trigger penalties, higher rates, or a suspended license in some states. Work through these steps in sequence, and keep records of every conversation with your insurer.
- Decide who keeps which vehicle. Match each car to the person who will drive it and pay for it. If a loan or lease is involved, confirm who is legally responsible for the payments before transferring anything.
- Update the title and registration. In most states, the person keeping the car should have the title and registration in their name. This usually requires a trip to the DMV and may involve a refinance if a lender is involved.
- Open a new policy before canceling the old one. Buy your own coverage first, then remove yourself from the joint policy. Never cancel first and shop later, because that creates a coverage gap.
- Notify the insurer in writing. Ask for confirmation that you have been removed and that your new policy is active. Keep a copy of that confirmation.
- Adjust coverage limits and deductibles. Your needs may have changed. If you now drive fewer miles or no longer commute with a spouse, you may qualify for lower rates.
After the split, review your policy every six months. Life changes quickly after a divorce, and your insurance should keep pace. If you move, change jobs, or add a new driver to your household, tell your insurer right away. Small updates often unlock discounts that offset the loss of the marital rate.
Coverage Gaps to Watch For After a Split
The biggest danger after a separation is an unnoticed coverage gap. If you are listed as a driver on your ex-spouse's policy but no longer live at that address, the insurer may deny a claim because you are not a household member. Conversely, if your ex-spouse keeps driving a car titled in your name, your insurance could be on the hook for an accident you had nothing to do with. Both situations are avoidable with prompt updates.
Another common gap involves teenagers and young drivers. If a child splits time between two households, both parents may need to list the teen on their policies. Some carriers allow a teen to be listed as an occasional driver on one policy, but rules vary by state and company. Failing to disclose a young driver can lead to a denied claim or a mid-term premium increase. If you share custody, ask each insurer how they handle a teen with two addresses.
Finally, watch out for lapses caused by payment disputes. If you and your ex-spouse shared a bank account that is now closed, an automatic payment could fail without either of you noticing. Set up autopay on your new policy from an account you control, and check your bank statements for the first few months. A single missed payment can raise your rate for years, so a little vigilance now pays off later.
Ways to Lower Your Premium After Divorce
Losing the married discount does not mean you are stuck with high rates. In fact, a divorce is a natural time to re-shop your coverage and find a better deal. Insurers compete fiercely for single drivers, and many offer discounts that married couples never bother to claim. The key is to compare multiple carriers rather than renewing automatically with your old company.
Several discounts are especially relevant after a split. You may qualify for a paid-in-full discount, a paperless billing discount, a safe-driver discount, or a low-mileage discount if your commute changed. If you bought a new car as part of the divorce, ask about a new car discount. If you have a student on your policy, ask about a good-student discount. These savings add up quickly and can offset the marital status change.
You can also adjust your deductible. Raising it from $500 to $1,000 can lower your premium noticeably, as long as you have the cash to cover the higher amount if you file a claim. Just be careful not to cut liability coverage to save money. Liability insurance protects your assets, and after a divorce you may have fewer shared resources to fall back on. For a broader look at how coverage options affect your rate, independent resources such as NewAutoInsurance explain the trade-offs in plain language.
Finally, consider bundling. If you rent or own a home, combining auto and renters or homeowners insurance with one carrier often produces a multi-policy discount. Even if you and your ex-spouse shared a bundle before, you can create a new one on your own and still capture the savings.
Legal and Financial Details That Affect Your Policy
Divorce agreements often spell out who pays for which insurance, but a divorce decree does not override an insurance contract. If a judge orders your ex-spouse to maintain coverage on a car you drive, that order is between the two of you, not between you and the insurer. If your ex-spouse drops the policy, you could be left uninsured even though the decree says otherwise. The safest approach is to carry your own policy and treat any court-ordered coverage as a backup, not a guarantee.
Liability is another area where the law and the policy can diverge. If you and your ex-spouse are both named on a loan for a vehicle, you may both remain financially responsible for the debt even after the divorce. Lenders typically require comprehensive and collision coverage until the loan is paid off, so whoever keeps the car must maintain those coverages. If the car is sold, make sure the loan is satisfied and the policy is canceled properly to avoid paying for coverage on a vehicle you no longer own.
In community property states, debts and assets accumulated during the marriage are generally split evenly. That can include insurance premiums owed, claims paid, and even vehicles. A family law attorney can clarify your obligations, but your insurance agent can explain the practical side: who is listed, who is covered, and what happens if a claim is filed. Having both professionals on the same page reduces the chance of a costly misunderstanding.
Comparing Quotes as a Newly Single Driver
Once your new policy is in place, plan to shop again within six to twelve months. Insurers weigh rating factors differently, so the company that offered the best rate right after your divorce may not be the cheapest a year later. Comparing quotes from multiple carriers takes only a few minutes online and can reveal savings of hundreds of dollars per year. You do not need to wait for renewal, either; you can switch mid-term and receive a prorated refund on unused premium.
When you request quotes, have your driver's license number, vehicle identification number, current coverage limits, and address ready. Be honest about your marital status and everyone who drives the car. Misrepresenting those details can void your policy later. If you are unsure what coverage you need, ask a licensed agent to walk you through the options. Free Auto Insurance Quotes Online connects drivers with licensed agents who can provide personalized quotes with no obligation to buy.
Divorce is hard enough without insurance complications on top of it. By separating your policy promptly, updating your titles and registrations, and comparing rates from several carriers, you protect yourself financially and often end up paying less than you feared. Take the steps in order, keep good records, and treat your new policy as the fresh start it is.