Auto Insurance Policy Limits: How Much Coverage Is Enough?
Understanding auto insurance policy limits and how much coverage is enough protects your assets after a crash. Call 8332757533 for free quotes at your target limits.
By Leo Fairmont
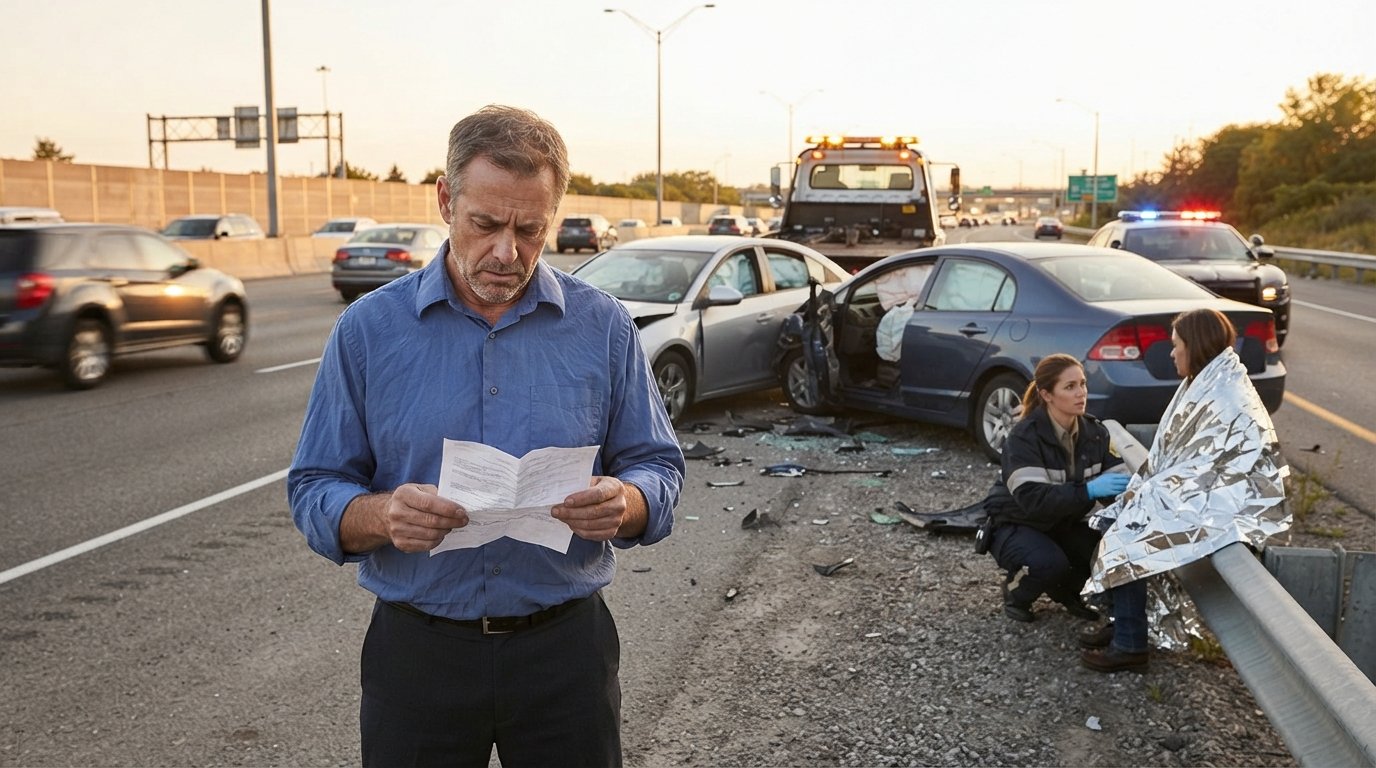
Imagine causing a highway accident that sends three people to the hospital and totals two vehicles. Your insurer pays its share, then hands you a bill for the rest, because your policy limits were too low. That scenario plays out every day across the United States, and it is the single most common and most expensive mistake drivers make when buying coverage. Understanding auto insurance policy limits and how much coverage is enough is not an abstract exercise in reading fine print. It is the difference between a covered claim and a lawsuit that follows you for years.
This guide breaks down what policy limits actually mean, how they appear on your declarations page, and how to choose numbers that protect your income, your savings, and your family. You will also see why the cheapest legal minimum is rarely the smartest financial decision, and how a quick comparison of quotes can reveal that higher limits often cost far less than drivers assume. If you want to run your own numbers against real rates, you can start by comparing Texas auto insurance quotes, and the same comparison logic applies in every state.
What Policy Limits Actually Mean on Your Declarations Page
Every auto policy states its limits as a series of numbers, usually written in a format like 50/100/25 or 100/300/100. Those numbers are not arbitrary. They represent the maximum your insurer will pay for specific categories of loss, and once those ceilings are reached, the remaining financial responsibility shifts to you. The first number is the per-person limit for bodily injury, the second is the total per-accident limit for bodily injury, and the third is the per-accident limit for property damage.
Suppose you carry 50/100/25 limits and cause an accident that injures two people. Your insurer can pay up to $50,000 for the first person's medical costs and up to $100,000 total for all injuries combined. If the second driver's injuries exceed the remaining $50,000, that driver can pursue you personally for the difference. The property damage number works the same way: $25,000 is all the insurer pays toward the other driver's vehicle, and anything beyond that, including a rented luxury car or a damaged fence, comes out of your pocket.
It helps to think of limits as the height of a wall between your assets and an accident claim. A tall wall absorbs the impact. A short wall lets the claim spill over into your savings, your home equity, and in serious cases, your future wages through wage garnishment. The declarations page also lists other limits that do not use the three-number format, including medical payments coverage, uninsured motorist coverage, and any deductibles that apply to collision or comprehensive coverage.
Reading the Three Numbers Correctly
Drivers frequently misread the split-limit format because the middle number looks like a doubling of the first. In reality, the middle number is a cap on the whole accident, not an additional allowance per person. If one person's claim consumes most of the per-accident limit, other injured parties may receive very little even though their own injuries were severe. This is one reason many insurance educators recommend considering a single limit policy, which combines bodily injury into one pool, such as $300,000 per accident, giving the insurer flexibility to allocate funds where the claims are worst.
The difference between split limits and a combined single limit matters most in multi-vehicle accidents, which are exactly the situations that generate the largest claims. A pileup on an interstate can involve four or five injured parties, and a split-limit policy with a modest per-accident cap can be exhausted almost immediately. When you request quotes, ask the agent to show you both split-limit and single-limit options so you can compare the real cost of each structure.
State Minimums: Legal Does Not Mean Sufficient
Every state except New Hampshire and Virginia (which allow alternate arrangements) requires drivers to carry some form of liability insurance, but the required amounts vary dramatically. Some states require as little as 25/50/25, while others mandate 50/100/50 or higher. These minimums exist to keep drivers legal, not to keep them financially whole. A single serious injury can generate medical bills in the hundreds of thousands of dollars, which means a driver carrying minimum limits is essentially self-insuring the gap.
Consider a common scenario: a driver with 30/60/25 limits runs a red light and injures a pedestrian who requires surgery and months of rehabilitation. The hospital bill alone might reach $150,000. The insurer pays its $30,000 per-person share, and the driver is personally exposed to the remaining six figures. Wage garnishment, liens, and bankruptcy filings are the frequent result. The uncomfortable truth is that minimum limits protect other drivers only up to a point; beyond that point, they protect nobody, including you.
Choosing higher limits is not just about protecting strangers. It is about protecting your own household from a financial shock that could undo years of saving. The premium difference between minimum limits and moderately higher limits is often surprisingly small, sometimes just a few dollars per month, which is why consumer educators consistently describe liability limit upgrades as one of the best values in personal finance.
How Much Liability Coverage Is Enough for Your Situation
There is no universal number that fits every driver, but there is a practical framework. The goal is to carry enough liability coverage that a serious at-fault accident would not force you to liquidate assets or surrender future income. A widely used rule of thumb is to carry liability limits at least equal to your net worth, and to add an umbrella policy once your assets exceed the standard policy limits available.
To apply the framework, gather a few facts about your finances and your driving exposure. Then match them against the coverage tiers below, which represent common recommendations rather than legal requirements.
- Minimum limits: appropriate only for drivers with virtually no assets and no meaningful income to protect, and even then, the exposure to future earnings remains.
- 50/100/50: a modest step up that covers many routine accidents but still leaves significant gaps in serious injury cases.
- 100/300/100: the level most financial professionals describe as a reasonable baseline for drivers with steady income, a home, or savings.
- 250/500/250 or a combined single limit of $500,000: appropriate for higher earners, homeowners in expensive markets, and families with teenage drivers.
- Umbrella policy on top: adds $1 million or more of liability protection for a relatively low annual premium, filling the gap above your auto policy.
Once you have a target, the next step is checking what that coverage actually costs. Rates vary enormously between carriers for identical limits, and the only reliable way to know is to gather multiple quotes. You can also explore broader consumer guidance on coverage structure through independent resources such as NewAutoInsurance, which publishes educational material on how policies are built and priced.
Two additional factors deserve attention. First, your income matters as much as your assets, because a judgment can follow your paycheck for years. Second, your driving patterns matter: a long daily commute or frequent highway driving increases the odds of a multi-party accident, which increases the value of higher per-accident limits.
Uninsured and Underinsured Motorist Coverage: The Other Half of the Equation
Liability coverage protects others when you are at fault. Uninsured and underinsured motorist coverage (UM/UIM) protects you when the other driver is at fault and either has no insurance or has too little. Given that a meaningful share of drivers on the road carry only minimum limits or none at all, UM/UIM is one of the most valuable coverages a driver can buy, and it is often inexpensive to add.
UM/UIM limits are usually written to match your liability limits, and many insurers require that match. If you carry 100/300 liability, your UM/UIM can also be 100/300, meaning that if a hit-and-run driver injures you, your own policy steps in up to those amounts. In states with high uninsured driver rates, this coverage can be the difference between receiving fair compensation and absorbing your own medical costs.
There is a related coverage called medical payments, or MedPay, which pays medical bills for you and your passengers regardless of fault, up to a modest limit such as $5,000 or $10,000. MedPay works quickly, often before a liability investigation is complete, and it can cover health insurance deductibles and copays that would otherwise come out of your pocket.
Why UM/UIM Limits Should Usually Match Your Liability Limits
If you decide that $300,000 is the right amount of protection to offer others, it is logical to want the same protection for yourself. Lowering UM/UIM below your liability limits creates an asymmetry: you would be generously covered if you cause a crash, but thinly covered if someone else causes one and flees or has no insurance. The premium savings from reducing UM/UIM are usually small relative to the protection given up.
Some drivers decline UM/UIM because they have health insurance and assume it will handle everything. Health insurance typically does not cover lost wages, pain and suffering, or the diminished value of your vehicle, all of which UM/UIM can address. For households with a primary earner, that distinction alone justifies the cost.
Additional Coverages That Shape Your Real-World Protection
Liability and UM/UIM form the core of a well-built policy, but several other coverages determine how smoothly a claim resolves. Collision coverage pays to repair or replace your own vehicle after a crash, regardless of fault. Comprehensive coverage handles non-collision events such as theft, hail, flooding, fire, and animal strikes. Together they are often marketed as full coverage, and if you have a loan or lease, the lender will typically require both.
Deductibles interact with these coverages. A higher deductible lowers your premium but increases the amount you pay before coverage begins. The right deductible is the largest amount you could comfortably pay on short notice without disrupting your budget. For many households, $500 to $1,000 is a reasonable range, though drivers with emergency savings sometimes choose $1,000 or $2,000 to reduce premiums.
Rental reimbursement and roadside assistance are smaller add-ons that improve the claims experience. Rental reimbursement pays for a temporary vehicle while yours is being repaired, and roadside assistance covers towing, jump-starts, and lockouts. Neither is required, but both prevent minor incidents from becoming major inconveniences.
A Practical Process for Choosing Your Limits
Choosing limits is a decision you can make systematically rather than emotionally. The following process takes about thirty minutes and produces a defensible answer you can revisit each year.
- List your assets: savings, investments, home equity, and any business interests that could be pursued in a lawsuit.
- Estimate your annual income and the number of working years ahead of you, since wage garnishment can reach future earnings.
- Set liability limits at least equal to the larger of your assets or a multiple of your income, then round up to the next available tier.
- Match your UM/UIM limits to your liability limits, and add MedPay or personal injury protection where available.
- Choose collision and comprehensive deductibles you could pay without borrowing.
- Compare quotes from multiple carriers at those exact limits, because the same coverage can vary by hundreds of dollars per year between insurers.
After running this process once, review it after any major life change: a new home, a raise, a marriage, a teenage driver joining the policy, or a significant change in commuting distance. Limits that fit a renter with modest savings may be inadequate for a homeowner with children and a six-figure income.
It also pays to revisit your limits when you shop for a new carrier. Because insurers price risk differently, a driver who could only afford 50/100/50 with one company may find that 100/300/100 costs nearly the same with another. That is precisely why comparing quotes at your target limits, rather than at the cheapest possible limits, produces the most useful information.
Common Mistakes That Leave Drivers Underinsured
The most frequent mistake is treating the state minimum as a target rather than a floor. Drivers renew year after year at the same low limits, never revisiting the numbers as their income and assets grow. Another common error is dropping UM/UIM to save a few dollars, which leaves the driver unprotected against the very scenario that generates the largest personal losses.
A third mistake is focusing only on the premium and ignoring the deductible, the claims process, and the insurer's reputation for paying claims. The cheapest policy is not a bargain if a claim is denied or delayed. Finally, many drivers never ask about discounts, even though insurers routinely offer savings for bundling home and auto, safe driving records, paid-in-full policies, good students, and vehicle safety features. Asking about discounts during the quote process is free and often reduces the cost of upgrading limits.
Understanding auto insurance policy limits and how much coverage is enough ultimately comes down to honesty about your finances and your exposure. The right limits are the ones that let you sleep at night knowing a single accident will not erase what you have built. Start by gathering quotes at a few different limit levels, compare them side by side, and let the numbers guide a decision that protects both your wallet and your future.