How to File an Auto Insurance Claim Step by Step
Navigating how to file an auto insurance claim step by step is easier with a clear plan. Get expert help at 8332757533 to maximize your settlement and avoid delays.
By Victor Langley
A fender bender on a rain-slicked highway, a hailstorm that dimples your hood, or a parking lot scrape you discover days later: at some point, most drivers face the task of filing an auto insurance claim. The process can feel intimidating, especially when you are already stressed about damage, safety, and costs. But filing a claim does not have to be a nightmare. With the right preparation and a clear roadmap, you can move from accident scene to settlement check with far less friction. This guide walks you through how to file an auto insurance claim step by step, highlights common pitfalls, and explains how to protect your rates and your rights along the way.
Before You File: Immediate Steps After an Accident
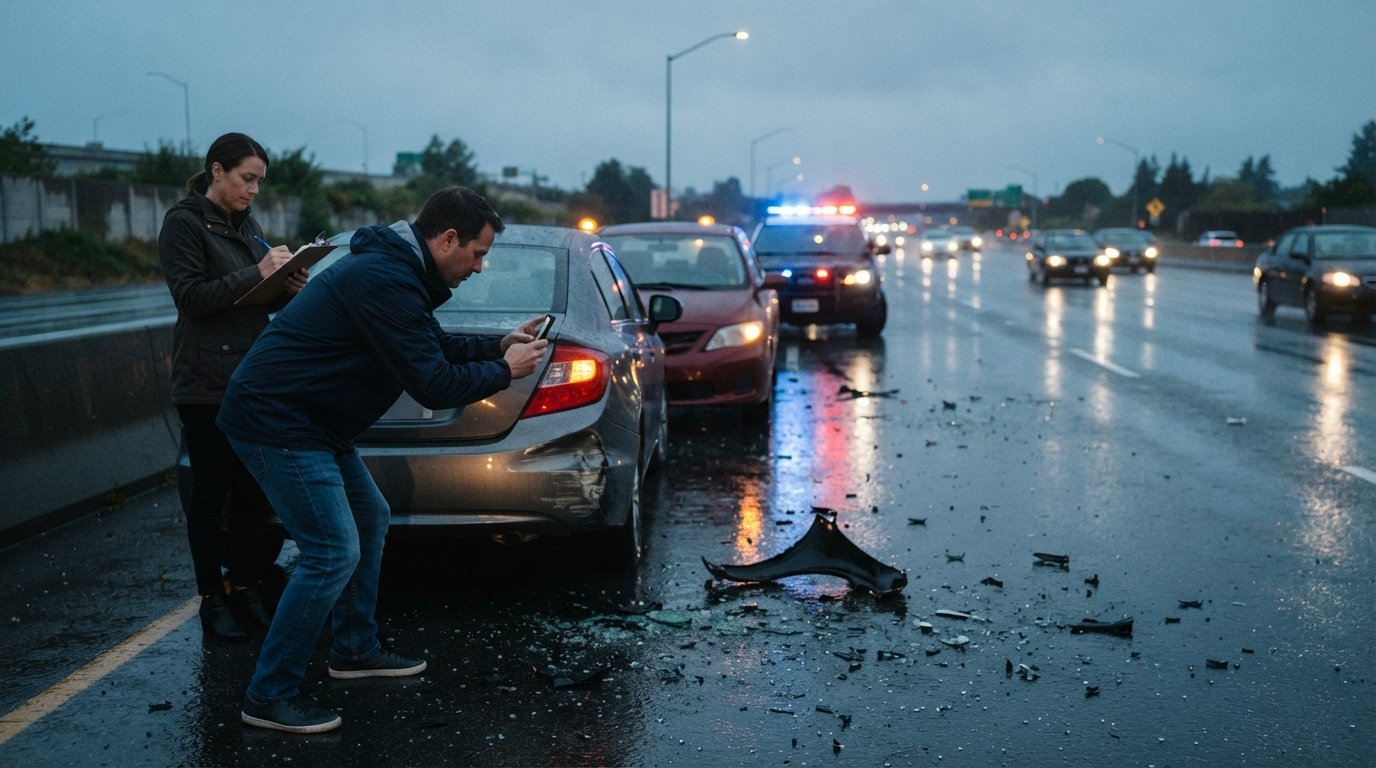
The moments right after a collision or discovery of damage set the stage for everything that follows. Your first priority is always safety. Move vehicles out of traffic if possible, turn on hazard lights, and check yourself and passengers for injuries. Call 911 if anyone is hurt or if the scene is unsafe. Even if everyone feels fine, it is wise to request a police report, especially for multi-vehicle accidents or when fault is disputed. A police report creates an official record that insurers rely on heavily.
While you wait for help, gather information. Exchange names, phone numbers, driver's license numbers, license plate numbers, and insurance details with the other driver. Do not discuss fault or apologize; keep the conversation factual. If there are witnesses, ask for their contact information. Use your phone to take photos and videos of all vehicles from multiple angles, the surrounding scene, road conditions, traffic signals, and any visible injuries. These visuals can be worth thousands of dollars when a claims adjuster evaluates liability.
As soon as possible, notify your own insurance company. Many policies require prompt notice, and delays can give an insurer grounds to deny a claim. You do not need to have every detail ready; a simple call to your agent or the claims hotline starts the clock and gets a claim number assigned. If you are unsure which coverage applies, the claims representative can guide you. Remember that even if the other driver was at fault, you may still need to involve your own insurer, especially if you carry collision or uninsured motorist coverage.
Step 1: Understand Your Coverage Before You Call
Knowing what your policy actually covers prevents confusion and helps you set realistic expectations. Auto insurance is not a single product; it is a bundle of coverages that respond differently depending on the situation. Liability coverage pays for damage you cause to others, while collision coverage handles damage to your own vehicle from a collision, regardless of fault. Comprehensive coverage kicks in for non-collision events like theft, fire, vandalism, or weather. Uninsured and underinsured motorist coverage protects you when the at-fault driver has little or no insurance. Medical payments or personal injury protection can cover medical bills for you and your passengers.
If you are not sure what you have, pull out your declarations page or log into your insurer's app. The declarations page summarizes your coverages, limits, and deductibles. Your deductible is the amount you pay out of pocket before insurance pays for a covered claim. For example, if you have a $500 deductible on collision and the repair estimate is $3,000, you pay $500 and your insurer covers the remaining $2,500, minus any depreciation if you have an actual cash value policy.
Understanding these details helps you answer the claims representative's questions accurately and avoid surprises. If you discover that your coverage is inadequate, after the claim is resolved you can explore options to adjust your policy. Comparing rates from multiple carriers is a smart way to find better coverage at a lower price. For drivers in the Lone Star State, our guide on Auto Insurance Quotes Texas: Compare Rates and Save Big explains how to shop efficiently and spot real savings.
Step 2: Contact Your Insurer and File the Claim
Filing the claim itself is usually straightforward. You can call your insurer's claims hotline, use their mobile app, or file online through your account. Have your policy number, driver's license, vehicle information, and details of the incident ready. The representative will ask what happened, when and where it occurred, and whether police were involved. Provide facts, not opinions. If you are unsure about a detail, say so rather than guessing. You will receive a claim number, which you should write down and use in all future communications.
Your insurer will assign a claims adjuster to your case. The adjuster's job is to investigate the claim, determine coverage, and estimate the cost of repairs or the value of a total loss. They may ask you to provide a recorded statement. You are generally required to cooperate with the investigation, but you can ask for clarification if a question seems ambiguous. If you feel uncomfortable giving a recorded statement, you can request to provide a written statement instead, though some insurers may insist on a recording. Being honest and consistent is critical; discrepancies can delay or derail your claim.
At this stage, it also helps to understand the difference between a first-party claim (filed with your own insurer) and a third-party claim (filed with the at-fault driver's insurer). If you file with your own insurer under collision coverage, they will pay for repairs minus your deductible and then may seek reimbursement from the other insurer through subrogation. If you file directly with the other driver's insurer, you may avoid paying a deductible, but the process can take longer and the other insurer may dispute liability. Many drivers choose to file with their own insurer for speed and let the insurers sort out fault later.
Step 3: Document Everything and Cooperate with the Adjuster
Documentation is the backbone of a successful claim. Keep a folder (physical or digital) with all receipts, estimates, photos, police reports, medical records, and correspondence. If you rent a car while yours is in the shop, keep those receipts too, if your policy includes rental reimbursement. If you miss work due to the accident, document lost wages; some coverages may reimburse you. The more organized you are, the easier it is for the adjuster to approve your claim quickly.
The adjuster will likely inspect your vehicle or ask you to take it to a repair shop for an estimate. Some insurers have preferred shops, but you generally have the right to choose your own repair facility. If you use a shop outside the insurer's network, the insurer may ask for a separate estimate or send an adjuster to inspect the damage before authorizing repairs. Do not start repairs before the insurer has approved them, or you risk having to pay out of pocket for unauthorized work.
Communication is key. Respond promptly to calls and emails, but do not sign anything you do not understand. If the adjuster makes a settlement offer, take time to review it. You can negotiate if you believe the offer is too low, especially for total loss claims. Provide comparable vehicle listings, recent maintenance records, and any upgrades that add value. If you feel the adjuster is not being fair, you can ask to speak with a supervisor or file a complaint with your state's department of insurance.
Step 4: Handle Repairs, Rentals, and Total Loss Settlements
Once the insurer approves the claim, repairs can begin. If your vehicle is drivable, you may be able to continue using it until parts arrive. If it is not drivable, your insurer may arrange a rental car if you have rental reimbursement coverage. Keep in mind that rental coverage has daily and total limits, so check your policy. For repairs, the shop will work with the insurer to get supplemental payments if they discover hidden damage after dismantling the vehicle. Stay in the loop and ask for updates.
If your vehicle is declared a total loss, meaning the repair cost exceeds a certain percentage of its value (often 70 to 80 percent), the insurer will pay you the actual cash value (ACV) of the vehicle minus your deductible. ACV is what your car was worth just before the accident, not what you paid for it or what it would cost to replace. You can dispute the ACV if you have evidence that your car was worth more, such as recent upgrades, low mileage, or comparable listings in your area. Some policies offer replacement cost coverage, which pays to replace the vehicle with a new one of similar make and model, but this is less common for auto insurance.
If you still owe money on a car loan or lease, the insurer will typically pay the lender first. If the ACV is less than your loan balance, you may be responsible for the difference unless you have gap insurance. Gap insurance covers the gap between ACV and what you owe. It is often offered at dealerships but can also be added to some auto policies. If you are in this situation, review your options carefully and consider whether gap coverage makes sense for your next vehicle.
Common Mistakes That Delay or Derail Claims
Even honest drivers can unintentionally jeopardize their claims. One of the most common mistakes is waiting too long to report the accident. Most policies require notice within a reasonable time, and state laws may impose deadlines. Another mistake is admitting fault at the scene or in a recorded statement. Fault is a legal determination, and your words can be used against you. Similarly, exaggerating injuries or damage can backfire and lead to a denied claim or even fraud allegations.
Failing to document the scene thoroughly is another pitfall. Without photos, witness statements, or a police report, it becomes your word against the other driver's. Also, ignoring medical symptoms can hurt you; some injuries like whiplash or concussions appear hours or days later. If you feel unwell, see a doctor and keep records. Finally, do not accept the first settlement offer without reviewing it. Insurers are businesses, and their initial offer may be lower than what you deserve. Negotiation is a normal part of the process.
Another frequent issue is not understanding your deductible. Some drivers assume their insurer will cover everything, then are surprised when they owe $500 or $1,000. Knowing your deductible upfront helps you plan financially. If you cannot afford your deductible, some repair shops offer payment plans, or you can ask your insurer if they can deduct it from the settlement. In some states, you can pay your deductible directly to the shop over time.
How to File an Auto Insurance Claim Step by Step: A Quick Recap
To summarize the process, here is a concise numbered list you can refer back to when you need it. Following these steps can help you stay organized and reduce stress.
- Ensure safety and call for help. Move to a safe location, call 911 if needed, and request a police report.
- Exchange information and document the scene. Collect other driver's details, take photos, and gather witness contacts.
- Notify your insurer promptly. Call your agent or claims hotline to start the claim and get a claim number.
- Understand your coverage and deductible. Review your declarations page so you know what is covered.
- Cooperate with the adjuster. Provide accurate information, submit documentation, and get repair estimates.
- Review and negotiate the settlement. Do not accept the first offer without checking comparables and asking questions.
- Complete repairs or accept total loss payment. Use approved shops, keep receipts, and follow up until the claim is closed.
Each claim is unique, and some may require additional steps, such as dealing with injuries, rental cars, or legal issues. But the core process remains the same. Being proactive and communicative will almost always work in your favor.
If you want to learn more about how insurance works and how to find better rates, independent resources like NewAutoInsurance offer educational guides and comparisons that can help you make informed decisions. They are not an insurer or broker, but they provide useful consumer information.
After the Claim: Protecting Your Rates and Your Future
Filing a claim can affect your insurance premium, but not always as dramatically as people fear. Many insurers offer accident forgiveness for a first at-fault accident, especially if you have been a loyal customer. If the accident was not your fault, your rates generally should not increase, though some insurers may still adjust rates based on overall claims experience in your area. If your premium does go up, you can shop around for a better deal. Comparing quotes from multiple carriers is the most effective way to save money.
After the claim is resolved, take time to review your policy. Did you have enough coverage? Was your deductible manageable? Would gap insurance or rental reimbursement have helped? Adjusting your policy now can prevent financial pain later. You can also ask about discounts for safe driving, bundling, or paying in full. Small changes can add up to significant savings over time.
Finally, keep records of the claim for at least a few years. If a dispute arises or you need to reference the claim when switching insurers, having documentation handy is invaluable. Most claims close within a few weeks to a few months, depending on complexity. Stay patient, stay organized, and do not be afraid to ask questions. You have the right to understand every step of the process and to receive fair treatment from your insurer.
Filing an auto insurance claim is rarely fun, but it is manageable when you know what to expect. By following the steps outlined here, you can navigate the process with confidence and focus on getting back on the road safely.