How to Get Free Auto Insurance Quotes Online Step by Step
Get free auto insurance quotes online step by step and avoid overpaying. Call 8332757533 for personalized help finding the lowest rates.
By Victor Langley
Getting free auto insurance quotes online is one of the smartest financial moves any driver can make. Whether you are buying a new car, adding a teenage driver to your policy, or simply tired of paying too much every month, comparing multiple quotes puts you in control. The entire process takes about 15 to 20 minutes, requires no payment information, and can realistically save you hundreds of dollars per year. This guide walks you through every stage, from gathering your documents to choosing the right policy, so you can shop with confidence and zero pressure.
Why Comparing Quotes Online Beats Calling One Insurer
When you call a single insurance company, you only see that company's rates. You have no idea whether a competitor would charge 30 percent less for identical coverage. Online quote platforms solve this problem by letting you request rates from multiple carriers at once. The result is a side-by-side comparison that reveals exactly where you can save money.
Another major advantage is speed. Traditional shopping means phone calls, hold music, and repeated explanations of your driving history. Online quoting flips that model. You enter your information once, and licensed agents respond with tailored options. You stay in control of the timeline, and you never face a high-pressure sales pitch in your living room.
Before you start, it helps to understand the full landscape of coverage types and state rules. For drivers in the Lone Star State, our guide on how to get the best auto insurance quotes in Texas explains how state minimums and local rating factors affect your final price.
Step 1: Gather Your Driver and Vehicle Information
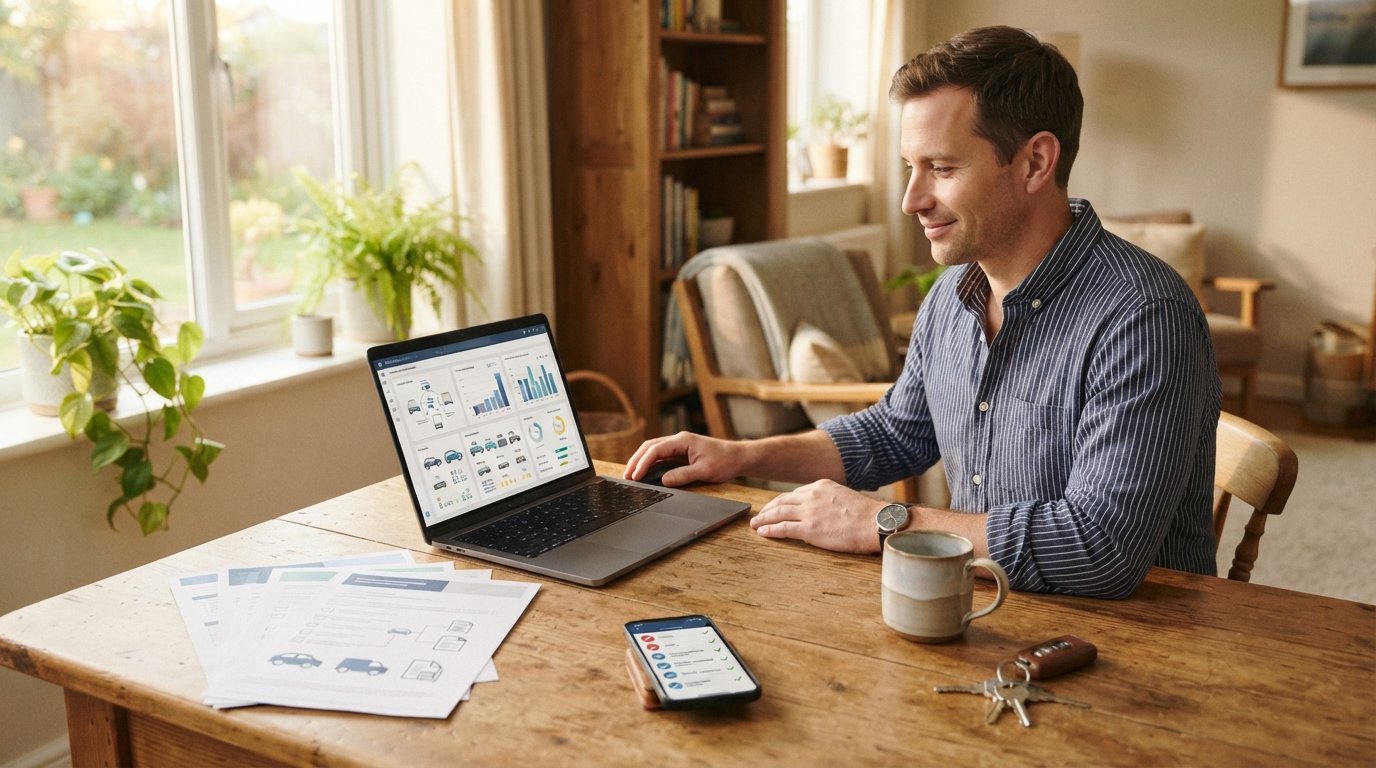
The quoting process moves fastest when you have everything ready before you sit down at the computer. Missing details force you to stop, hunt through paperwork, and start over. Spend five minutes collecting the essentials first, and the actual quote request becomes a smooth, one-pass experience.
Here is what you need within arm's reach:
- Your driver's license number and the license numbers of every driver in the household
- Vehicle identification numbers (VINs) for all cars you want covered
- Current insurance policy declarations page, if you have one
- Estimated annual mileage for each vehicle
- Garaging address (where the car is parked overnight)
Having these items ready does more than save time. Accurate information produces accurate quotes. If you guess at your mileage or forget to mention a teenage driver, the final premium after underwriting could jump significantly. Precision at this stage protects you from unpleasant surprises later.
Step 2: Choose a Reputable Quote Comparison Platform
Not every website that promises free quotes actually delivers them. Some sell your contact information to dozens of agents who bombard you with calls. Others show teaser rates that almost no driver actually qualifies for. Look for a platform that is transparent about how it works, connects you with licensed agents, and makes clear there is no obligation to purchase.
A trustworthy comparison service should offer several features. It should protect your data, explain exactly what happens after you submit the form, and present quotes from multiple carriers rather than a single insurer. It should also provide educational resources so you understand what you are buying.
For broader context on the insurance marketplace and how independent resources evaluate carriers, sites like NewAutoInsurance publish consumer guidance and educational articles that complement what you learn from quote tools. The more informed you are, the better your decisions become.
Step 3: Fill Out the Quote Request Form Carefully
This step is the heart of the process. The form asks for your personal details, driving history, vehicle information, and desired coverage levels. Every field matters because insurers weigh each factor when calculating your rate. Take your time and answer honestly.
Typical questions include your name, date of birth, address, marital status, occupation, years of driving experience, accident and violation history, current coverage, and whether you own or lease your vehicle. You will also choose a coverage level. State minimum liability is the cheapest option, while full coverage with collision and comprehensive costs more but protects your own car.
If you are unsure which coverage level to select, start with the state minimum and then request a full coverage quote as well. Comparing both side by side shows you exactly what the extra protection costs. Many drivers discover the difference is smaller than they expected.
Step 4: Review Your Quotes Side by Side
Once quotes arrive, resist the urge to simply pick the lowest number. The cheapest premium often reflects the thinnest coverage. A truly useful comparison looks at price and protection together, along with the carrier's reputation for paying claims.
Use this framework to evaluate each offer:
- Compare the monthly and six-month premium for identical coverage limits.
- Check the deductible on collision and comprehensive coverage.
- Verify whether roadside assistance, rental reimbursement, or gap coverage is included.
- Look up the insurer's complaint ratio and financial strength rating.
- Confirm any discounts that were applied and ask whether you qualify for more.
After you narrow the field, call or email the agents with follow-up questions. Ask about claims handling, local repair shop networks, and whether your rate will change after the first term. A carrier that answers clearly and promptly during the sales process often behaves the same way during a claim.
Step 5: Ask About Discounts Before You Decide
Discounts can shrink your premium dramatically, yet many drivers never ask about them. Insurers reward safe driving, loyalty, bundling, good grades, military service, and even paperless billing. The trick is knowing which ones you qualify for and confirming they appear on your final quote.
Common discounts worth asking about include:
- Multi-policy bundling (auto plus home or renters)
- Multi-vehicle discounts for households with two or more cars
- Safe driver and accident-free credits
- Defensive driving course completion
- Student away-at-school and good student discounts
- New car safety feature discounts (airbags, anti-theft devices)
When you speak with a licensed agent, mention every discount category that might apply to you. Even a 5 percent reduction compounds over years of coverage. The small effort at quote time pays off every renewal cycle.
Step 6: Verify Licensing and Finalize Your Policy
Before you hand over payment information, confirm that the agent and carrier are properly licensed in your state. Every state insurance department maintains a free online lookup tool. It takes two minutes and protects you from fraudulent operators.
Once verified, review the declarations page carefully. It lists your coverage limits, deductibles, premium, and policy period. Make sure the names, vehicles, and addresses are correct. If something looks wrong, ask for a corrected quote before you pay. After purchase, store your insurance card in your car and a digital copy on your phone.
Common Mistakes That Cost Drivers Money
The biggest mistake is accepting the first quote without comparison. Loyalty to a single carrier feels comfortable, but it frequently costs hundreds of dollars annually. Another frequent error is choosing state minimum liability coverage when the driver has significant assets to protect. Liability limits that seemed adequate years ago may fall far short of today's repair and medical costs.
Drivers also forget to re-shop at renewal. Insurance rates shift constantly as carriers adjust their risk models. A company that was expensive two years ago might now be the cheapest option. Setting a calendar reminder 30 days before each renewal keeps you from drifting into overpriced coverage.
Finally, never inflate or hide information on a quote form. Misrepresenting your mileage, garaging address, or driving record may lower the initial estimate, but it can void your policy after a claim. Honesty at the quoting stage is both ethical and financially smart.
How Often Should You Request New Quotes
Financial advisors generally recommend comparing auto insurance quotes once a year, plus any time your life changes. Events like buying a home, adding a driver, getting married, retiring, or moving to a new state all alter your risk profile. Each change is an opportunity to find a better rate.
Even without a major life event, annual comparison keeps carriers honest. Insurers use complex algorithms, and their pricing for your specific profile can move up or down without any obvious reason. A fresh set of quotes reveals whether you are still getting a competitive deal.
The entire process costs nothing but a few minutes. There is no obligation to switch, and no penalty for looking. The only guaranteed outcome is better information, and better information almost always leads to better financial decisions.
Start your search today, gather your documents, and let multiple licensed agents compete for your business. Drivers who compare consistently pay less, understand their coverage better, and face fewer surprises when they need to file a claim. Your wallet and your peace of mind will both thank you.