Does Auto Policy Cover a Rental Car After a Comprehensive Claim?
Rental reimbursement is an optional add-on, not automatic with comprehensive. Call (833)-275-7533 to compare quotes and avoid surprise rental bills.
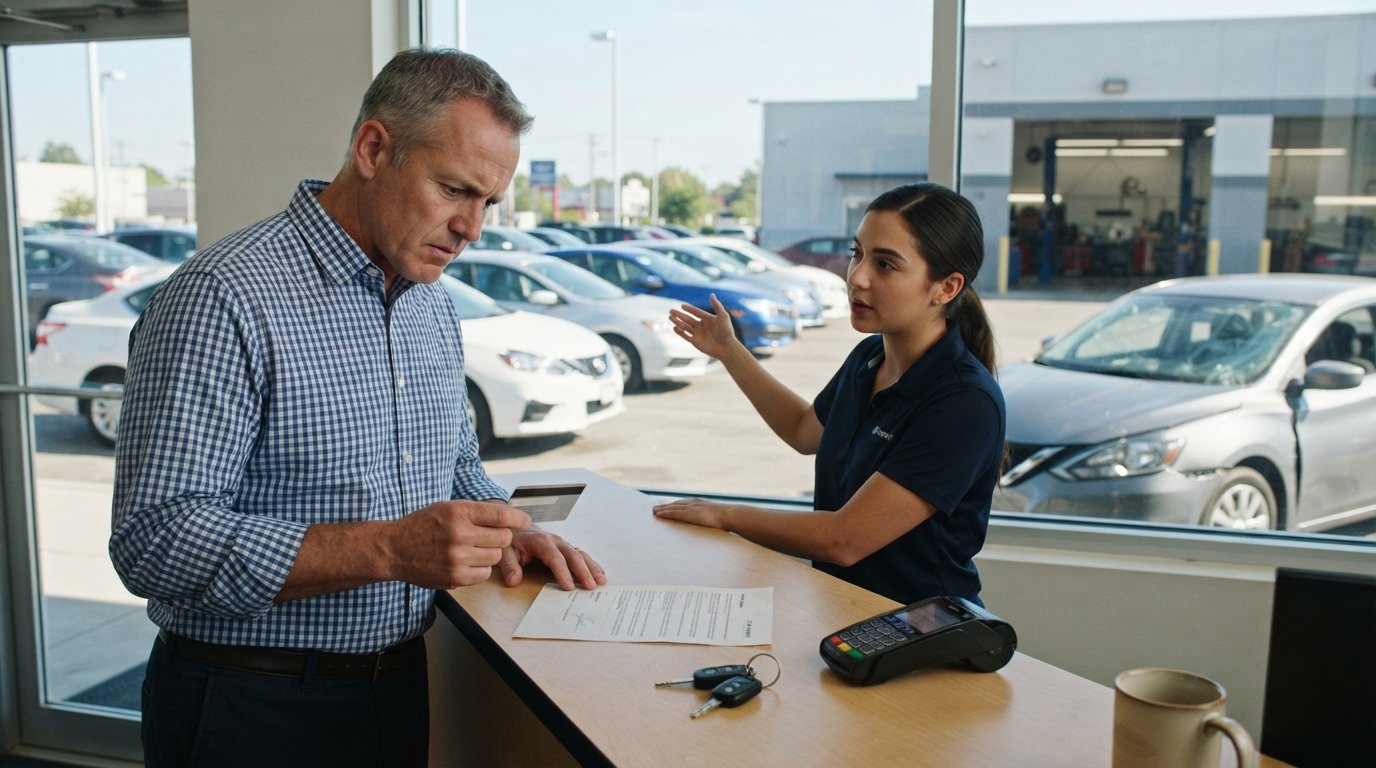
Your car is in the shop after a cracked windshield, a hail storm, or a collision with a deer. You are standing at the rental counter, and the agent asks for a credit card. Before you swipe, you need a straight answer to a simple question: does my auto policy cover a rental car after a comprehensive claim? The short answer is often no, not automatically. Comprehensive coverage pays to repair or replace your vehicle, but it does not automatically include a rental car. That benefit comes from a separate add-on called rental reimbursement coverage. Without it, you could be paying $40 to $100 per day out of pocket while your car sits in the body shop. This guide explains exactly how rental reimbursement works, what the caps look like, when the other driver's insurance should pay, and how to avoid surprise bills at the rental counter.
Comprehensive Coverage and Rental Cars: The Core Distinction
Comprehensive coverage is a physical damage coverage that pays for damage to your own vehicle from events other than a collision. That includes theft, fire, vandalism, hail, flooding, falling objects, and animal strikes. It is usually sold with a deductible, and it is often required by lenders or leases. What comprehensive does not do is pay for a substitute vehicle while yours is being repaired. The policy language is specific: comprehensive pays for direct and accidental loss to the covered auto. A rental car is a separate, indirect expense, and insurers do not pay it unless you bought a specific endorsement for it.
This is the single most common misunderstanding among drivers filing a comprehensive claim. You pay your deductible, the insurer pays the body shop, and then you assume a rental car is part of the deal. It is not. Rental reimbursement is an optional coverage, usually written as an endorsement on your policy. It is sometimes called transportation expenses coverage or loss of use coverage. If it is not on your declarations page, you do not have it, no matter how comprehensive your comprehensive coverage is.
To confirm what you have, open your policy declarations page and look for a line item that says rental reimbursement, transportation expenses, or loss of use. It will list a daily limit and a total per-claim limit. If you see nothing, call your agent and ask directly. Getting this answer before an accident is far cheaper than discovering it at the rental counter.
How Rental Reimbursement Limits Actually Work
Rental reimbursement coverage is not unlimited. It comes with two caps that work together: a daily maximum and a per-claim maximum. The daily cap is the most the insurer will pay for one day of rental. The per-claim cap is the total the insurer will pay for the entire claim. Typical policies offer daily limits between $30 and $100, with total limits between $900 and $3,000. A common mid-range choice is $50 per day with a $1,500 maximum, which works out to about 30 days of rental. Higher limits cost more in premium but give you more breathing room for longer repairs.
Here is how the math plays out in practice. Suppose you choose $40 per day with a $1,200 per-claim cap. Your car is in the shop for 20 days. The insurer pays $40 per day for 20 days, or $800 total, which is under the cap. But if the rental agency charges $65 per day, you pay the $25 difference out of pocket every day. If the repair takes 40 days, the insurer still stops at $1,200, and you cover the rest. The caps are strict, and they apply to the rental period that is considered reasonable for the repair, not to however long the shop happens to take.
Drivers often ask whether they can choose their own rental car class. Most policies reimburse for a vehicle similar to your own or a standard economy or mid-size car. If you upgrade to a luxury SUV, the insurer will typically pay only the daily cap, and you cover the upgrade. Keep receipts and confirm the rental agency bills your insurer directly if your policy allows direct billing. Otherwise, you may pay upfront and get reimbursed later, which affects your cash flow.
When you compare coverage options, ask for a rental reimbursement quote as part of the same conversation. It is usually inexpensive, often just a few dollars per month, and it can save you hundreds during a claim. Comparing quotes side by side makes the cost difference obvious. You can start by reviewing options through a comparison platform that shows multiple carriers at once, and you can also check educational resources such as a car loan refinancing guide if you are weighing the overall cost of ownership alongside insurance. For Texas-specific rate comparisons, see this guide on auto insurance quotes in Texas.
When the At-Fault Driver's Liability Pays for Your Rental
If your comprehensive claim is the only claim involved, your own optional coverage is the only possible source of rental payment. But many comprehensive claims are not the whole story. If another driver caused the damage and their liability coverage accepts fault, their property damage liability coverage may pay for your rental car as part of your damages. This is a liability claim against them, not a comprehensive claim under your policy. The distinction matters because the at-fault driver's insurer is responsible for your reasonable loss of use, and that can include a rental car while your vehicle is being repaired.
In that situation, you do not need rental reimbursement on your own policy, but you do need the other insurer to accept liability. That can take days or weeks. If you cannot wait, you can use your own rental reimbursement coverage if you have it and let your insurer pursue subrogation against the at-fault carrier. If you do not have it, you may have to pay out of pocket and seek reimbursement later, which requires keeping every receipt and documenting the repair timeline. Do not assume the other driver's insurer will hand you a rental car on day one. Confirm liability acceptance in writing before you rely on their payment.
There is also the question of fault in a comprehensive claim. Comprehensive claims are generally fault-neutral, meaning they do not involve another driver's liability. A deer strike, a hail storm, or a theft has no at-fault driver to pursue. In those cases, your own rental reimbursement coverage is the only practical source of payment. That is why the add-on matters most for comprehensive claims that do not involve another party.
Exclusions and Delays That Can Leave You Without a Rental
Even with rental reimbursement coverage, there are exclusions that can leave you without a car. The most common is a delay in parts or a backlog at the body shop. Insurers typically pay for a rental only for the reasonable repair time, not for extended waits caused by supply chain problems or shop scheduling. If the shop says the repair will take 10 days but the parts are backordered for three weeks, the insurer may pay for 10 days and stop. Some policies are more generous, but you should not assume it. Read the endorsement language and ask your agent how delays are handled.
Other exclusions to watch for include:
- Rentals needed for mechanical breakdowns or maintenance that are not part of a covered claim.
- Rentals during a period when your vehicle is drivable and the shop is waiting on authorization.
- Upgrades beyond the daily cap or rentals longer than the per-claim maximum.
- Rentals after a total loss beyond a short window, since the claim shifts to a settlement rather than a repair.
Total loss claims deserve special attention. If your car is declared a total loss, the rental reimbursement coverage usually ends within a few days of the settlement offer, not when you buy a replacement car. Some policies give you a set number of days after the total loss determination. Plan accordingly, because shopping for a replacement vehicle can take longer than you expect.
How to Confirm Your Coverage and Avoid Surprise Bills
The fastest way to answer the question for your own policy is to check your declarations page and call your agent. Ask three specific questions: Do I have rental reimbursement, what are my daily and per-claim limits, and does the coverage apply to comprehensive claims? Get the answers in writing if possible. Then ask how the insurer handles parts delays and whether direct billing to the rental agency is available. These details determine whether you will be standing at the counter with a credit card or walking out with keys.
If you do not have the coverage, you can usually add it mid-policy. It is an inexpensive endorsement, and adding it before a claim is far better than paying out of pocket afterward. When you shop for a new policy, make rental reimbursement part of your comparison checklist alongside liability limits, deductibles, and roadside assistance. A few dollars a month is a small price for avoiding a $1,500 rental bill during a repair.
Finally, keep your claim organized. Save the repair estimate, the shop's timeline, and every rental receipt. If the insurer disputes the length of the rental, documentation is your best argument. If you have to pay out of pocket and seek reimbursement from an at-fault driver's insurer, the same records support your claim. Being prepared turns a stressful situation into a manageable one.
So does my auto policy cover a rental car after a comprehensive claim? Only if you added rental reimbursement coverage, or if another driver's liability is paying for your loss of use. Check your policy today, confirm your limits, and ask for a rental reimbursement quote the next time you compare coverage. A few minutes of preparation now can save you hundreds of dollars and a lot of frustration later.