How to Add a Teen Driver to Your Car Insurance Policy
Learn how to add a teen driver to your car insurance policy and cut costs with the right discounts. Call 8332757533 for expert guidance.
By Imogen Clarke
Adding a teen driver to your car insurance policy is one of those tasks that feels simple until you see the premium increase. According to the Insurance Information Institute, adding a 16-year-old to a family policy can raise rates by 50% or more, depending on the state and carrier. That number alone makes most parents want to delay the call. But driving without insurance is not an option in any state, and letting a teen drive uninsured exposes your entire household to serious financial risk. The good news is that the process itself is straightforward once you understand the steps, the paperwork, and the discounts that can soften the blow. This guide walks you through how to add a teen driver to your car insurance policy, from notifying your insurer to choosing the right coverage structure and finding savings along the way.
When Should You Add a Teen Driver to Your Policy?
Timing matters more than most parents realize. You should add your teen to your policy as soon as they receive a learner's permit, not when they get their full license. Some insurers allow you to add a permit driver at no extra cost because they are always supervised by a licensed adult. Others charge a small fee. Either way, notifying your carrier early keeps you compliant and prevents gaps that could cause a claim denial later.
If your teen lives in your household and drives any vehicle you own, even occasionally, most insurers require you to list them on your policy. Failing to do so can give the company grounds to deny a claim if your teen causes an accident. That denial could leave you paying out of pocket for property damage, medical bills, and legal fees. The risk is simply too high to gamble on.
There are a few situations where you might not need to add a teen right away. If your teen has a license but lives at college more than 100 miles away and does not have a car on campus, many insurers offer a distant student discount that keeps them on the policy at a reduced rate. If your teen drives only a motorcycle or off-road vehicle, you may need a separate policy. But for the typical household where a teenager shares a family car, adding them to your existing policy is almost always the right move.
Step-by-Step: How to Add a Teen Driver to Your Car Insurance Policy
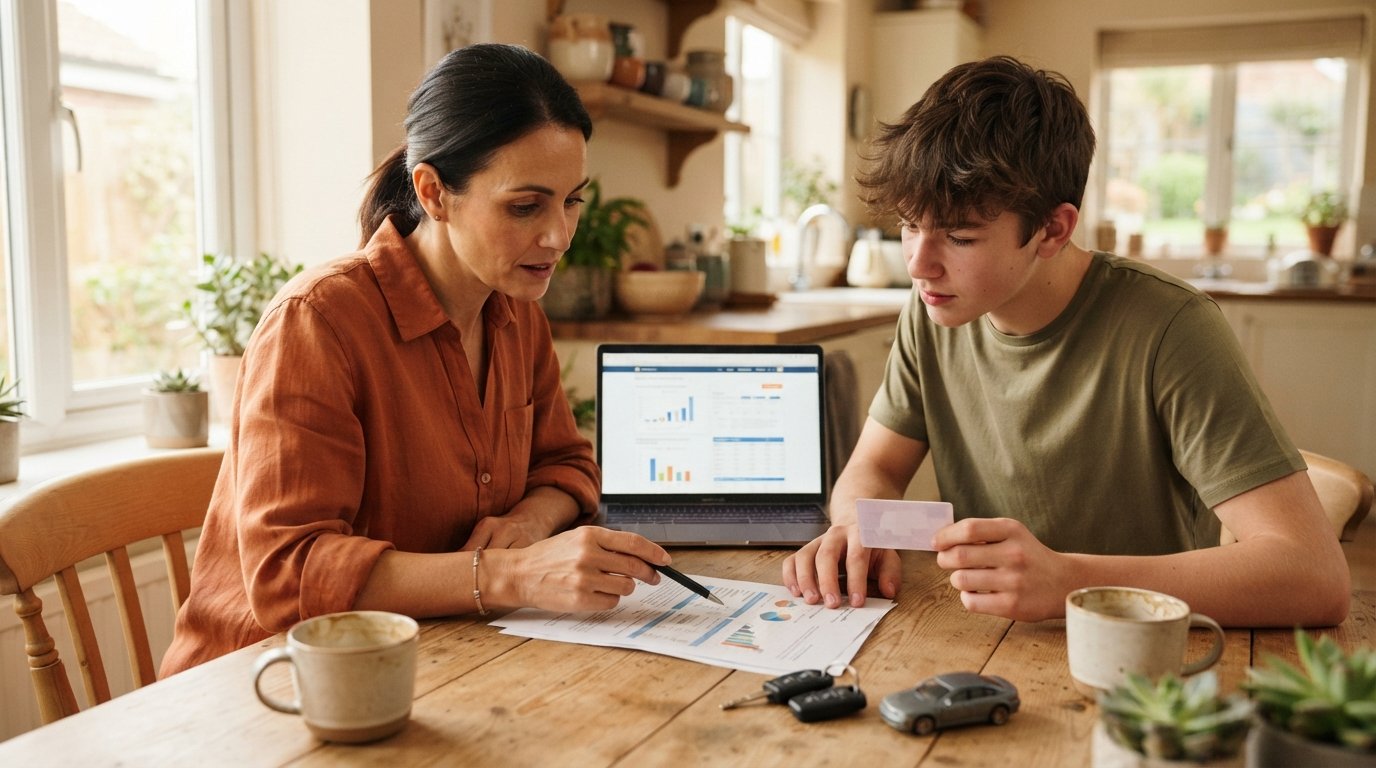
The actual process of adding a teen driver takes less time than you might think. Most carriers let you do it online, through a mobile app, or over the phone. Here is the sequence that works for nearly every insurer.
- Gather the required information. You will need your teen's full legal name, date of birth, driver's license or permit number, and the date they received it. Have your policy number and vehicle identification numbers handy as well.
- Contact your insurer. Log into your account, call the customer service line, or use your agent's portal. Tell them you need to add a newly licensed or permitted driver to the policy.
- Provide the details and confirm coverage. The representative will update your policy and tell you the new premium. Ask whether any discounts apply, such as good student or driver training credits.
- Review the updated declarations page. Once the change is processed, your insurer should send an updated declarations page. Check that your teen's name, license status, and vehicle assignment are correct.
- Set expectations for your teen. Explain the financial consequences of tickets and accidents, and consider a written agreement about safe driving habits.
After the policy is updated, you may also want to revisit your coverage limits. Adding a teen increases the likelihood of a claim, so raising liability limits or adding uninsured motorist coverage can be a smart move. If you are not sure which coverage types make sense for your household, a comparison platform like Free Auto Insurance Quotes Online can help you review options from multiple carriers without obligation.
One more thing: if you are adding a teen while also removing a vehicle from the policy, the order of operations matters. Removing a car first can change your rates, and then adding a driver can change them again. Handle both changes in the same call so the insurer can calculate the net effect accurately. For a detailed walkthrough on removing a vehicle, see our guide on how to remove a car from your auto insurance policy correctly.
How Much Does It Cost to Add a Teen Driver?
The cost varies widely based on your state, your carrier, your teen's age and gender, the type of vehicle they drive, and your household's claims history. On average, parents see increases between 50% and 100% of their current premium. In high-cost states like California, New York, and Michigan, the jump can be even steeper. In rural areas with lower accident rates, the increase may be more modest.
Several factors drive the number up or down. Teen males typically cost more to insure than teen females, though the gap narrows as drivers get older. A teen assigned to a sports car or a large SUV will cost more than one assigned to a midsize sedan with strong safety ratings. Teens with a clean record and good grades often qualify for discounts that can reduce the increase by 10% to 25%.
It also helps to understand how insurers rate young drivers. Most companies use a combination of age, driving experience, and claims data. A 16-year-old with a permit is rated differently than a 19-year-old with three years of clean driving. If your teen waits until 18 or 19 to get licensed, your premium increase will be smaller. That is one reason some families delay licensing, though the tradeoff is that the teen gains less driving experience before adulthood.
Ways to Lower the Cost of Insuring a Teen Driver
You do not have to accept the first quote your insurer gives you. There are several legitimate strategies to reduce the premium increase, and many of them stack together.
- Good student discount: Most major carriers offer 10% to 25% off for teens who maintain a B average or better. You will usually need to provide a transcript or report card each semester.
- Driver training discount: Completing a state-approved driver education course can earn 5% to 15% off. Some insurers also accept defensive driving courses for additional savings.
- Telematics or usage-based programs: Apps and plug-in devices that monitor driving habits can reward safe behavior with discounts of 10% to 30% at renewal.
- Distant student discount: If your teen attends college more than 100 miles away and does not have a car on campus, you may qualify for a significant reduction.
- Higher deductible: Raising your collision and comprehensive deductible from $500 to $1,000 can lower the premium, though you will pay more out of pocket if you file a claim.
Another option is to buy a separate policy for your teen. This rarely saves money because teen-only policies are expensive, but it can protect your own rates if your teen has an accident. Weigh the tradeoff carefully: a separate policy means your teen builds their own claims history, but you lose the multi-car discount and the convenience of one bill.
You should also shop around at renewal. Insurers use different rating formulas, and the company that was cheapest for you before adding a teen may not be the cheapest after. Getting quotes from multiple carriers is the single most effective way to find the lowest rate. You can start by requesting free quotes from several insurers at once and comparing the results side by side.
Should You Add Your Teen to Your Policy or Buy a Separate One?
This is one of the most common questions parents ask, and the answer depends on your priorities. Adding your teen to your existing policy is usually cheaper because you keep multi-car and multi-driver discounts, and you avoid paying two separate administrative fees. It also ensures your teen has continuous coverage, which matters when they eventually buy their own policy.
A separate policy makes sense in a few narrow situations. If your teen owns their own car and title, they may need their own policy. If your teen has a serious violation or accident on their record, keeping them off your policy can protect your rates. And if your teen lives in another state for school or work, a local policy may be more practical.
For most families, the math favors adding the teen to the family policy. The premium increase is real, but it is almost always less than the cost of a standalone teen policy. Plus, you keep control over coverage limits and can adjust them as your teen gains experience.
Common Mistakes to Avoid When Adding a Teen Driver
The biggest mistake is waiting too long. Some parents delay adding a teen until after an accident, hoping to avoid the premium increase. That strategy backfires badly. If the insurer discovers the teen was a household member who should have been listed, it can deny the claim, cancel the policy, or both. You end up paying for damages out of pocket and facing higher rates for years.
Another mistake is assuming your teen is automatically covered. Every policy has definitions of who is an insured driver, and household members who are not listed may not qualify. Even if your teen drives your car only once a week, list them. The cost of adding them is far less than the cost of an uncovered claim.
Finally, do not forget to update the policy when circumstances change. If your teen moves out, graduates, or buys their own car, tell your insurer. Keeping an inactive driver on your policy wastes money, and removing them incorrectly can create coverage gaps. Review your policy at least once a year to make sure it still reflects your household.
Frequently Asked Questions About Adding a Teen Driver
Does adding a teen driver always raise my premium?
In most cases, yes. Teen drivers are statistically more likely to file claims, so insurers charge more to cover them. However, discounts for good grades, driver training, and safe driving habits can reduce the increase significantly.
Can I add my teen to my policy if they do not have a license yet?
Many insurers allow you to add a teen with a learner's permit. Some charge a small fee, while others add permit drivers at no cost. Check with your carrier for specific rules.
What happens if my teen gets a ticket or causes an accident?
Your premium will likely increase at renewal. The amount depends on the severity of the incident and your insurer's rating rules. In some cases, your teen may be required to complete a defensive driving course to keep discounts.
Can my teen be covered under my policy if they drive a friend's car?
Yes, most policies extend liability coverage to a covered driver operating a non-owned vehicle with permission. However, the friend's policy may be primary, and your policy may apply as secondary. Review your policy language carefully.
How do I compare rates after adding a teen driver?
Use a comparison platform to request quotes from multiple carriers. Provide accurate information about your teen's age, driving record, and vehicle assignment. Compare the total premium, not just the monthly payment, and check each policy's coverage limits and deductibles.
Adding a teen driver to your car insurance policy is a milestone that comes with both responsibility and cost. By acting early, asking about every discount, and reviewing your coverage annually, you can keep the increase manageable while making sure your teen is properly protected. The steps are simple: gather your documents, call your insurer, confirm the details, and look for savings. Done right, this process takes less than an hour and gives you peace of mind for every mile your teen drives.
If you want to see how much you could save by comparing carriers, start by requesting free, no-obligation quotes from multiple insurers. A few minutes of comparison shopping can make a meaningful difference in what you pay each month. And as always, reach out to a licensed agent if you have questions about your specific situation. For independent consumer guidance and educational resources on auto insurance, you can also visit NewAutoInsurance.