How to Insure a Car You Only Drive Seasonally
Learn how to insure a car you only drive seasonally and avoid coverage gaps. Call (833)-275-7533 for expert guidance on storage policies and savings.
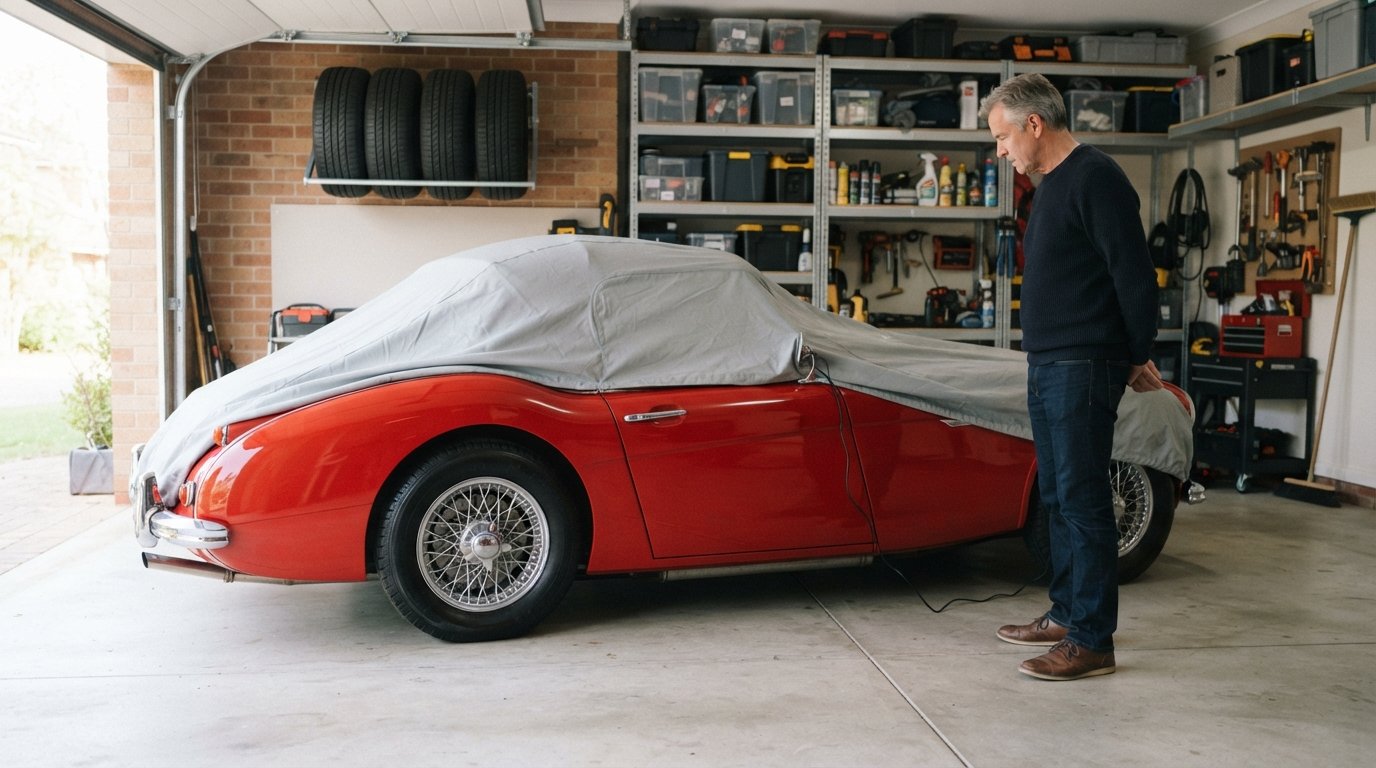
If your convertible hibernates from November to March or your classic truck only sees sunny weekend miles, you are likely paying for coverage you barely use. Seasonal vehicles sit idle for weeks or months, yet standard auto policies keep charging the same rate as if you were commuting daily. The good news is that insurers have built specific tools for this exact situation, and learning how to insure a car you only drive seasonally can cut your premium by 20 to 50 percent without leaving you exposed. The key is understanding which coverages to pause, which to keep, and how to restart full protection before the first spring drive.
Understand What Seasonal Insurance Really Means
Seasonal car insurance is not a single product. It is a strategy built around adjusting your existing policy or buying a specialized storage policy during the months your vehicle is off the road. Most insurers treat a car that is driven fewer than 5,000 to 7,500 miles per year as low-mileage, and some allow you to formally classify it as seasonal or pleasure-use. That classification changes the rating factors, reducing your annual premium because the insurer assumes lower accident exposure.
However, the term seasonal coverage gets used loosely. Some agents mean a full policy with a mileage restriction, while others mean a comprehensive-only storage policy that strips out liability and collision. Before you agree to anything, ask exactly which coverages remain active and which are suspended. A policy that saves you $60 per month but leaves you uninsured for a fire or hail claim is not a bargain. In most states, a stored vehicle still needs comprehensive coverage if you want protection against theft, vandalism, weather, and falling objects, because those risks do not disappear when the engine is off.
If you are unsure how your current carrier defines seasonal use, start by requesting a copy of your declarations page and comparing it to the quote options you receive. A side-by-side comparison makes it obvious whether a storage policy is genuinely cheaper or just shifting risk back to you. You can also read our guide on how to insure a car you rarely drive for additional strategies on low-mileage discounts and usage-based programs.
Choose Between a Storage Policy and a Low-Mileage Policy
There are two main paths for seasonal vehicles, and the right one depends on whether you plan to keep the car registered and legally parked on a public street or in a private garage. A comprehensive-only storage policy is the most aggressive money-saver. It removes liability, collision, and personal injury protection while keeping comprehensive coverage for theft, fire, and weather damage. Because the vehicle is not being driven, the insurer accepts that liability exposure is near zero. The trade-off is that you cannot legally drive the car on public roads while the policy is in storage mode, and some states require continuous liability coverage to maintain registration.
A low-mileage or pleasure-use policy is less restrictive. You keep full coverage year-round, but you agree to a mileage cap and confirm the car is not used for commuting. This option costs more than a storage policy but avoids the registration and reinstatement headaches. It also protects you if you take the car out for an unexpected winter drive or if a family member needs to move it during a storm. For many owners, the middle ground is the safest financial choice because it eliminates the risk of a coverage lapse and preserves continuous insurance history, which insurers reward with lower rates.
Here is a simple framework to decide:
- Store it off public roads and want maximum savings: comprehensive-only storage policy.
- Keep it registered and occasionally move it: low-mileage policy with full coverage.
- Live in a state that penalizes registration lapses: keep liability active year-round or surrender the plate.
- Own a classic or collector car: ask about agreed-value coverage with seasonal mileage limits.
Whichever path you choose, document your storage location. Insurers may ask whether the vehicle is parked in a garage, driveway, or storage facility, and the answer affects both eligibility and price. A locked garage usually earns a lower comprehensive rate than a carport or open lot.
Avoid the Registration and Insurance Lapse Trap
The biggest mistake seasonal drivers make is canceling insurance entirely and letting the registration go dormant without notifying the state. In most U.S. states, insurers are required to report cancellations to the DMV. If your registration remains active but your liability coverage is not, the state may flag you for an insurance lapse, impose fines, suspend your registration, and in some cases require you to file an SR-22 for years afterward. The savings from a few months of canceled coverage can vanish the moment you pay reinstatement fees and higher rates for a lapse on your record.
There is a cleaner way to handle this. If you plan to store the car and not drive it at all, surrender the license plate and registration before you cancel liability coverage. That tells the state the vehicle is off the road, so no lapse is recorded. When the driving season returns, you re-register the car and reinstate full coverage. If surrendering the plate is impractical, keep the minimum liability coverage active year-round and reduce only the collision and optional coverages. That preserves continuous insurance history and avoids the administrative headache.
State rules vary widely, so confirm the specifics before you act. Some states allow a seasonal registration or a planned non-operation status, while others require you to return the plate in person. A quick call to your DMV or a conversation with a licensed agent can prevent a costly surprise. Remember that a lapse in insurance can follow you for three to five years and raise your rates on every vehicle you insure, not just the seasonal one.
Reinstate Full Coverage Before the Driving Season
Timing matters when you switch from storage back to active driving. Do not wait until the morning of your first road trip to call your insurer, because reinstatement is not always instant. Some carriers require a signed form, a new photo inspection, or a reinstatement fee. Others may treat the gap as a new policy and re-underwrite the vehicle, which can change your rate. Give yourself at least one to two weeks before the season starts to confirm that liability, collision, and any optional coverages are active and that your registration is valid.
Use this checklist before the first drive:
- Confirm the effective date of reinstatement in writing, not just verbally.
- Verify that your registration and plates are current with the DMV.
- Ask whether the insurer requires photos or an inspection of the vehicle.
- Review the new premium and deductibles before you sign.
- Update your mileage estimate so the low-mileage discount is applied correctly.
If you are switching carriers at the same time, line up the new policy to start on the same day the old one ends. A gap of even one day can be reported as a lapse. For a broader look at how different carriers handle seasonal and low-mileage policies, you can compare informational resources at NewAutoInsurance consumer guides, which explain coverage options and savings strategies without acting as a broker.
Ask the Right Questions About Motorcycle and RV Storage
The same seasonal logic applies to motorcycles, scooters, travel trailers, and motorhomes, but the details differ enough that you should ask specific questions. Motorcycle policies often include a winter storage credit if you notify the insurer of the storage dates, and some carriers let you drop liability while keeping comprehensive. RVs and travel trailers may be covered under a separate policy that includes contents and awning coverage, and storage-mode reductions vary by carrier. Do not assume your auto policy extends to these vehicles.
Ask these questions before you store any seasonal vehicle:
- Does the policy offer a formal storage credit, and what dates does it cover?
- Which coverages remain active during storage (comprehensive, theft, fire, weather)?
- Is there a minimum liability requirement to keep the registration valid?
- Will the insurer require an inspection or photos when I reinstate coverage?
- Are accessories, contents, or attached equipment covered during storage?
Get the answers in writing, especially if you are relying on a storage credit to lower your premium. Verbal promises are difficult to enforce at claim time. If your carrier does not offer a seasonal program, ask whether a low-mileage discount or a usage-based telematics program can achieve a similar result. Many insurers now offer app-based monitoring that rewards drivers who log fewer miles, which can be a good fit for a car that sits for months.
Compare Quotes and Time Your Switch
Seasonal insurance is not one-size-fits-all, and the carrier that offers the best storage credit for a motorcycle may not be the cheapest for a classic car. The most reliable way to save is to compare quotes from multiple carriers using the same coverage assumptions, then time your policy change to coincide with your storage dates. Shopping at least 30 days before your renewal gives you room to negotiate and avoids a last-minute lapse. When you request quotes, state clearly that the vehicle is seasonal, provide an honest annual mileage estimate, and confirm that the quote includes comprehensive coverage during storage.
Finally, treat your seasonal policy like a financial calendar item. Mark the storage start and end dates, set a reminder to reinstate coverage two weeks before the driving season, and keep copies of every confirmation. That simple discipline protects your registration, preserves your insurance history, and keeps your premium low without exposing you to a catastrophic uninsured loss. Whether you drive a summer sports car or a winter-ready SUV that sits out the hot months, the right seasonal strategy lets you keep the vehicle you love without paying for miles you never drive.